Zero Hedge

Japan Sold Almost $90 Billion In Treasuries To Fund Record Yen Intervention

Japan Sold Almost $90 Billion In Treasuries To Fund Record Yen Intervention

At the end of July, the only question following Japan's record $90 billion yen intervention (which worked for about two weeks before the effects faded and Bessent had to engage in more market intervention), was whether and how much Treasuries Japan had sold as part of the intervention. 

We now now the answers: i) yes and ii) a lot

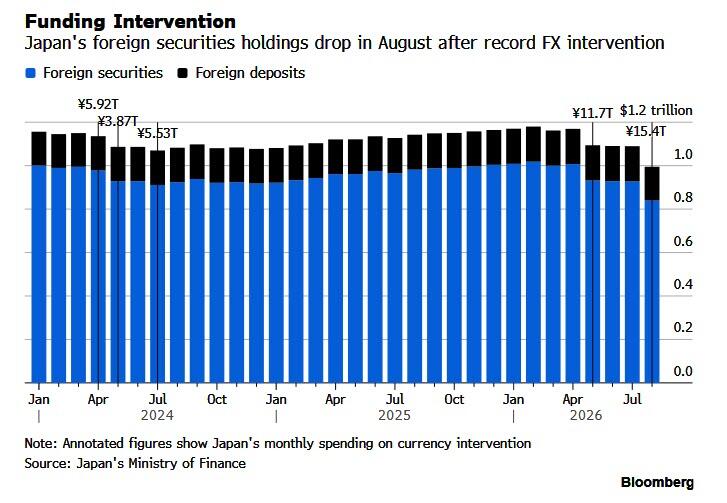
According to Finance Ministry reserve data released Monday, Tokyo’s holdings of foreign securities fell by $87.8 billion at the end of August from a month earlier. That decline was close to the scale of Japan’s recent intervention to support the yen. Analysts suggested Japan likely sold Treasuries at the short end of the maturity spectrum, Bloomberg reported.

Prior to the latest reserve release, the ministry had already confirmed that authorities spent the equivalent of ¥15.4 trillion ($98.6 billion) in the month through Aug. 26, with part of the operation conducted jointly with the US. And as we reported previously, te monthly intervention was also the largest on record.

A ministry briefer said intervention was a factor behind the fall in foreign reserves, but did not confirm that Treasuries were offloaded. Another intervention financed through sales of US Treasuries could potentially further anger Bessent as it would show that Tokyo is still willing to go down that route even as US officials, including Treasury Secretary Scott Bessent, have become increasingly focused on Treasury-market stability, particularly ahead of the midterm elections.

“Japan may have used both foreign securities and deposits, but it most likely sold US Treasuries,” said Atsushi Takeda, chief economist at Itochu Research Institute.

As we noted then, the US participated in Japan’s intervention campaign at the end of July by stepping into the market on July 31 in the first coordinated move between the nations to support the yen since 1998. That, according to Bloomberg, shows the two sides are still likely on the same page for now.

“Bessent has also repeatedly said that the yen has weakened too much, so the US probably shares that view and that’s why it’s cooperating with Japan,” Takeda said.Still, long-term US yields are still firmly placed on Bessent’s radar. He recently announced that the government would double the size of its buybacks of longer-dated debt for two months through Nov. 4, a move likely aimed at keeping a lid on longer-term yields.

The data do not provide a detailed breakdown of securities holdings or maturities, though market participants estimate that roughly 70% of Japan’s foreign reserves are invested in US Treasuries.

“Japan still has room to intervene given the amount of securities it holds, but given comments from Bessent, selling US Treasuries to fund further intervention could end up attracting pressure from the US,” said Akira Nishimura, economist at the Japan Research Institute. “That would make it difficult for the ministry and the BOJ to act going forward.”

Analysts suggested that Treasury sales were likely focused at the short end of maturities, limiting their impact on long-term yields and the potential for irritation in Washington.

“Japan’s Treasury holdings would span the curve, but the first port of call to fund intervention would be to liquidate assets with maturities of 5 years and under,” said Prashant Newnaha, senior Asia-Pacific rates strategist at TD Securities, flagging their greater liquidity. “It’s unlikely the MOF would have offloaded longer dated securities - maturities of 10 years or more - given the potential for significant pressure on long-end yields.”

Not only are shorter-term Treasuries the easiest to sell, foreign reserve managers tend to invest at the short end anyway as that is their “preferred habitat,” said Macquarie strategist Gareth Berry, adding that  “conveniently, selling short-dated Treasuries is probably something the US side would be less concerned about, and better able to live with, as US attention seems mainly focused on the long-end."

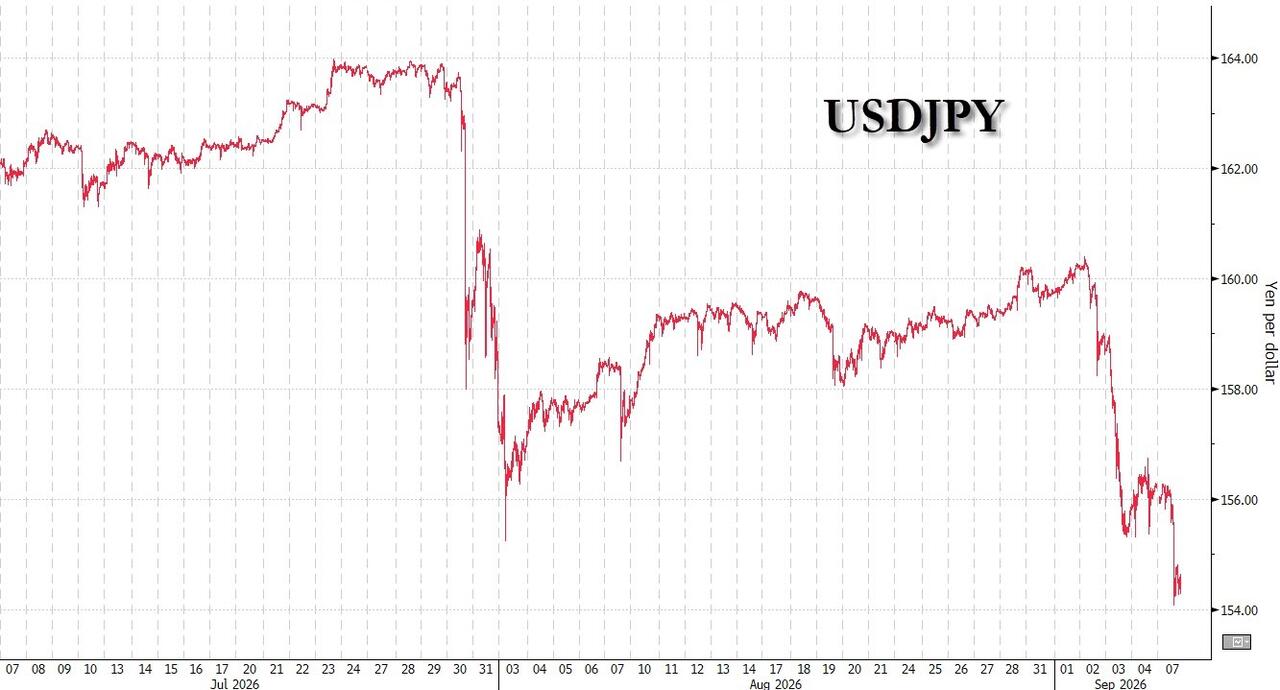
Markets have remained jittery since last week as investors recalibrate their rate expectations and positions. The yen strengthened from around 160.39 per dollar on Wednesday to as much as 155.30 on Friday. The currency further strengthened to around 154.50 on Monday amid ongoing speculation Japan’s Government Pension Investment Fund may boost allocations toward domestic assets.

That suggests no further intervention for the time being, especially with the BOJ expected to do the heavy lifting from now on. Following Bessent’s call for higher Japanese interest rates in North Carolina last week and recent signaling from BOJ officials, markets are now fully pricing in a BOJ rate hike in September. Some investors are even starting to consider whether the central bank could accelerate the pace of tightening after a series of hawkish signals, a stance that would offer further support for the yen.

Finally, while Monday’s report showed Japan’s foreign currency reserves fell $94.6 billion to $995 billion at the end of August, the remaining amount still shows the substantial resources available to authorities should they need to intervene again. Foreign currency deposits, another potential source of intervention funds, fell $6.9 billion.

In addition to selling securities and drawing on foreign deposits, Japan can also tap the Foreign and International Monetary Authorities Repo Facility in future interventions, Finance Minister Satsuki Katayama suggested after the US-Japan joint intervention. The facility introduced during the pandemic enables Japan to access up to $60 billion per day without selling Treasuries, limiting any impact on US yields and expanding the potential scope for intervention. Still, there is no record of Japan using FIMA.

“The lack of any precedent would be a significant hurdle to actually using it,” Nishimura said. “So I view the comments on FIMA as more of a signal that Japan still has ample resources available to fund intervention, rather than actually using the facility.”

Tyler Durden Mon, 09/07/2026 - 12:15

The Copper Chart Causing Alarm

The Copper Chart Causing Alarm

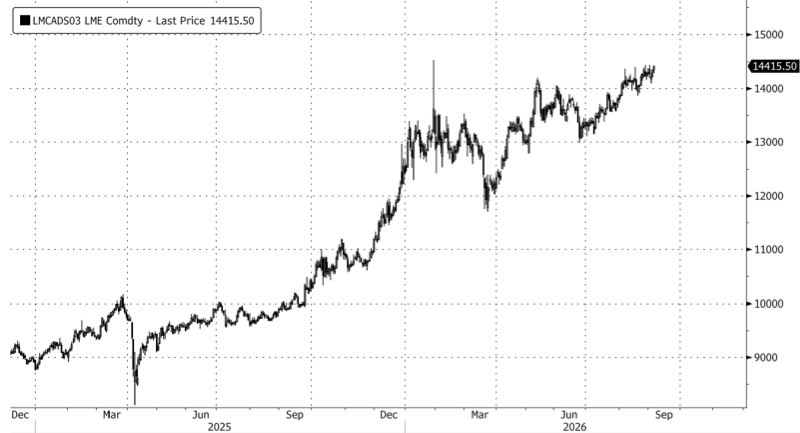
Copper futures in London continue to move higher, once again approaching record highs, as US buyers purchase record volumes from the seaborne market, with imports reaching 200,000 tons in July. A phased US tariff would keep that buying in motion for longer, further tightening the ex-US market and limiting any near-term price correction in London trading.

Rafael Barcellos, head of Latin American Metals & Mining and Pulp & Paper Equity Research at Bradesco BBI, wrote in a note last week that global mine supply is deteriorating. He warned that severe weather in Chile has forced Antofagasta and Lundin to cut their production guidance, further tightening an already stressed physical market.

Barcellos explained:

Copper prices extended their July rally into August, running above US$14,000/t throughout the month and reaching ~US$14,450/t as of August 30. Momentum has been driven by near-term physical tightness, as refined copper continues to flow into the US ahead of a potential import tariff.

While market consensus frames the policy as a binary outcome for copper — a tariff being supportive for prices and a no-tariff decision being negative — we would argue instead that both outcomes are ultimately bearish, and that it is the uncertainty around the tariffs that is intensifying the current upward momentum. Should tariffs not be implemented, the massive inventories accumulated in the US would be redirected elsewhere, increasing global supply availability. However, should the US instead move ahead, US buyers would likely reduce near-term procurement given the elevated stocks already built ahead of the decision, ultimately reducing regional demand and easing tightness elsewhere. That said, a phased tariff (e.g. an incremental rate over the coming years) — which we do see as the most likely scenario — should help keep US buyers in the seaborne market for longer, smoothing rather than removing the demand adjustment and limiting the near-term downside to prices.

On the supply side, the concentrate market remains tight, further exacerbated by extreme weather in Chile, which led Antofagasta and Lundin Mining to lower their 2026 production guidance ranges to 625-655kt (from 650-700kt) and 300-325kt (from 310-335kt), respectively, reflecting disruptions at Los Pelambres and Caserones. On the refined side, amid persistent concentrate tightness, Chinese smelters have increasingly turned to secondary feedstock, with copper scrap imports rising +15% YoY in July (+9% YTD)

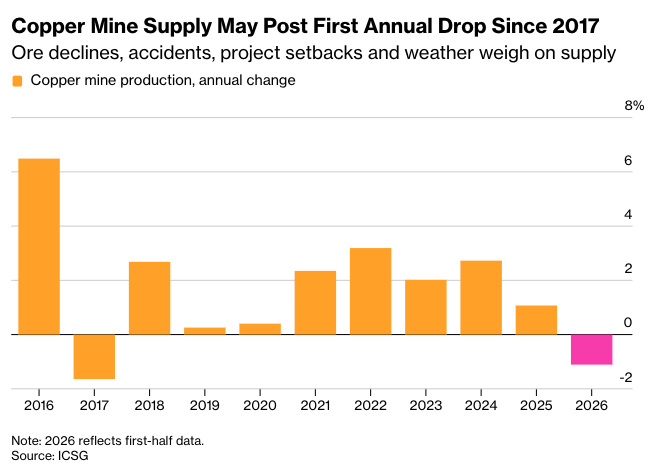
Barcellos' view of the copper market was echoed in a Bloomberg report on Friday, which cited International Copper Study Group data showing that global mine production fell 1.1% during the first half of 2026, with output at industry giants Codelco and Freeport-McMoRan declining by double digits.

Separately, Morgan Stanley, which began the year forecasting supply growth, now expects mine production to finish roughly unchanged or slightly lower, potentially marking the first annual decline since 2017.

Producers representing roughly two-thirds of global supply recorded a 3.5% decline during the first half and a 4.1% drop in the second quarter, according to Jefferies data cited by SP Angel. Chile, the world's largest copper-producing country, suffered its weakest second quarter in nearly two decades and now expects annual output to fall 2.6%.

Related:

Copper has now advanced for 10 consecutive weeks on the London Metal Exchange.

To sum up, all of this only suggests a structurally bullish period for copper. Demand from electric vehicles, power-grid expansion and artificial-intelligence data centers is accelerating just as physical-market tightness constrains supply and pushes London prices higher.

Tyler Durden Mon, 09/07/2026 - 11:35

GOP Bets On Trumpapalooza To Defy Midterm History

GOP Bets On Trumpapalooza To Defy Midterm History

Authored by Carolina Lumetta via RealClearPolitics,

Texas-based Republican strategist Rebecca Trahan is excited to see the first-ever GOP midterm convention come to Dallas next week. More specifically, she hopes it will bring yet more national attention and dollars to the Senate campaign for state Attorney General Ken Paxton.

"I think [the convention] can be very motivating. I hope that the event does encourage and get people to get out and vote," Trahan told RealClearPolitics. "I hope that it drives a lot of money to the Paxton campaign because they really need it, and I know that Texas really needs Ken Paxton as the next senator considering our options."

Trahan says Paxton's Democratic opponent James Talarico is a more formidable challenger than many Republicans realize. She said the convention is a welcome burst of energy onto the scene but would be better if it were more accessible. The two-day event will not be aired in full on national television networks, and it competes with the beginning of the school year and the start of football season on the two nights of speeches.

"I really applaud the RNC for doing everything that they can to help Texas candidates, and especially to help Ken Paxton, because we need it," Trahan said.

But she's not attending the convention either.

"For me, if I'm going to a fundraiser, I prefer that it be a little bit more private," Trahan said. "I love conventions, but there is so much work to be done just this weekend alone, and block walking and phone banking. So I chose to stay back and do that."

The Republican National Committee promised a "Trumpapalooza" as the president takes the stage on both convention nights. Several Republican candidates have hemmed and hawed on whether they'll attend the rally-like event, and the RNC has opened attendance to the public, hoping to gin up both base and prospective voter support.

"We are trying to reach those low- and mid-propensity voters that came out for President Trump in 2024, and we're trying to communicate to the American people the contrast that they have on the ballot this cycle," RNC spokeswoman Natalie Baldassarre told RCP.

Vice President JD Vance previewed the party's message during a White House press briefing Thursday. For the past year, the Trump administration has highlighted the One Big Beautiful Bill, rebranded as the Working Families Tax Cuts. In recent weeks, they've argued that Democrats who opposed the legislation would essentially be raising taxes if they win and would try to reverse Trump's actions over the past two years.

"My elevator pitch is actually very simple," Vance told reporters. "Do you want to live in a country that has safety and security and prosperity? If the answer is yes, and I think most Americans do, then vote for congressional Republicans over congressional Democrats on every single issue. The Democrats have taken the side of fraudsters, of criminals, and of far-left interest groups over the side of the American people."

But the strategy of hosting a midterm convention in Texas in September could be a double-edged sword.

"I don't know how much I want to be part of this," one Republican House member told RCP. "It's just going to be a highly orchestrated Trump thing where they'll trot out some members."

Many Republican candidates, particularly those in tight races, have either declined to attend the convention due to scheduling issues or have not revealed their plans, according to reporting from Politico and CNN. During a midterm year, even one or two days spent away from the campaign trail is considered wasted time. To that effect, House Speaker Mike Johnson already canceled the final weeks of the House session this month so that members may remain in their districts.

The low level of enthusiasm does not appear to be worrying the White House. Vance said the point of the convention is to bring the full force of the Trump administration to help the GOP, which does not necessarily require candidates to be on the stage.

"That doesn't concern me," Vance said during the briefing. "We can make the argument as much as possible that if you elect congressional Democrats, you're going to see higher prices, worse energy, higher taxes, and more fraud. The president and I can go and make that argument on national TV. We don't need a congressman in a tight race to be there in all cases."

Conventions in midterm years are often glorified revelries with little concrete purpose, especially when the identity of the party's eventual presidential nominee is unknown. Trump first publicly floated the idea of a midterm convention last year. Then, the RNC voted during its January annual meeting to change the charter rules to allow for such an event. Trump confirmed the date and location in another Truth Social post in June.

While the GOP has never done something like this before, Democrats were once quite practiced at it. The party would often host a mid-cycle convention until the mid-1980s, when then-Democratic National Committee chairman Paul Kirk shuttered the tradition. He complained that would-be presidential candidates used the stage to attract attention for themselves rather than all the races down-ballot that needed support. The entire event he summed up as "places for mischief."

This year, the DNC again teased that it might return the practice, but in its own annual meeting, members shot down the idea. DNC Executive Director Roger Lau said in a statement that the party had "baited" the GOP into throwing money down the drain for a midterm convention, giving the DNC an advantage in spending. But that strategy might not have panned out. The RNC reported a record $130.3 million in cash on hand by the end of July. The DNC reported roughly $16 million at the same time, along with nearly $18 million in debt.

Most congressional Republicans are paying roughly $25,000 each to attend the convention, though each state party manages its own ticket packages. Other affiliated organizations, such as the National Republican Congressional Committee, are offering additional perks like breakfast with House leadership and special access for up to $100,000, according to an NRCC flyer first reported by Politico. The RNC also designated tickets for state parties, which then determined how to distribute them. Instead of delegates, the seats will be filled with members of the public, according to the RNC.

RNC Chair Joe Gruters told Newsmax this week that the convention will be a landing place for the party's messaging. He appeared optimistic that of the 35 competitive House races this cycle, Republicans can defy conventional wisdom and defend the congressional majority.

"We think we can defy history and we have the right candidates," Gruters said. "We have the messaging, we have the resources to put behind that messaging, and so, we're well on our way."

The messaging will focus on key portions of the president's agenda, including last year's tax cuts, border enforcement, energy policy, trade, and more. But it will have to dodge some pitfalls, such as the ongoing war with Iran, high inflation and gas prices, a controversial deal to subsidize Venezuelan beef, concerns about data centers, and the president's sinking approval ratings. Vice President JD Vance will keynote the first night, and the president will close out Thursday night with his own address.

Tyler Durden Mon, 09/07/2026 - 10:25

Huawei Crashes Apple's Big Launch Week With $3,000 Trifold Smartphone

Huawei Crashes Apple's Big Launch Week With $3,000 Trifold Smartphone

Two days before Apple's big launch event on Wednesday, when the company is expected to debut its long-awaited foldable iPhone, Huawei Technologies and Xiaomi are unveiling their premium foldable smartphones.

Huawei on Monday unveiled its Mate XT 2, a trifold smartphone that unfolds into a 10.2-inch tablet. The starting price is $2,980, representing a 10% increase over its predecessor.

Huawei Executive Director Richard Yu attributed part of that increase to the big memory squeeze that has sent prices skyrocketing. Despite its premium price, the entry-level device comes with 16GB of memory and 256GB of storage. 

Xiaomi is set to launch a rival foldable phone later today, while Apple's foldable iPhone, expected to debut on Wednesday, could be called the iPhone Ultra and cost upwards of $2,500.

Yu told reporters earlier that the "real challenge right now is pricing, because memory costs have risen sharply. We adopted a lot of new technology, and the cost pressure has been enormous."

The launches of premium foldable phones from the three major brands this week come amid mounting headwinds across the global handset market. Counterpoint forecasts a 14% drop in global smartphone shipments this year. Chinese manufacturers are particularly exposed because of their reliance on budget handsets.

Counterpoint analyst Ivan Lam said Apple has the "world's biggest premium device installed base," adding, "Its foldable will sell well and rapidly grab market share." He also noted that the new handset could spur broader consumer demand, giving rivals a lift.

Smart Analytics Global forecasts that Apple could capture 41% of worldwide foldable sales next year. Its entry will undoubtedly intensify competition across the foldable space.

However, Nikkei Asia reported last week that production of foldable iPhones remains limited ahead of this week's launch.

"Apple has very high quality requirements and added an extra trial run in August ahead of actual production. However, production is ramping up slowly, with output currently at only a few hundred units a day in late August. That initial volume could be challenging to meet market demand," one supply chain manager told the Japanese news outlet.

With U.S. gasoline prices averaging above $4 a gallon nationally and squeezing household budgets, the iPhone Ultra's high price tag could pose a major test of consumers' willingness to spend on premium upgrades. For Apple, under new leadership with John Ternus at the helm, the key question is whether the foldable design offers enough value to persuade consumers to upgrade. Then again, there are always buy-now, pay-later options.

Tyler Durden Mon, 09/07/2026 - 10:00

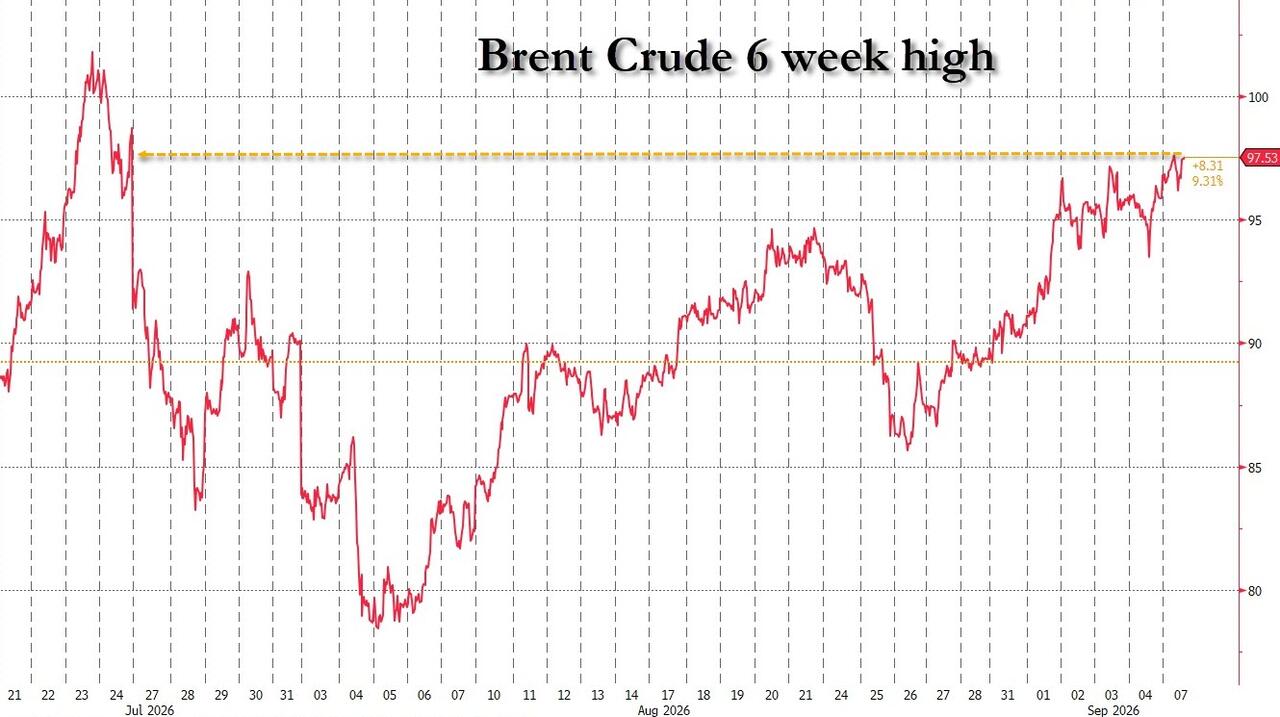
Futures Drop As Iran Hostilities Send Brent To 6 Week High Above $97

Futures Drop As Iran Hostilities Send Brent To 6 Week High Above $97

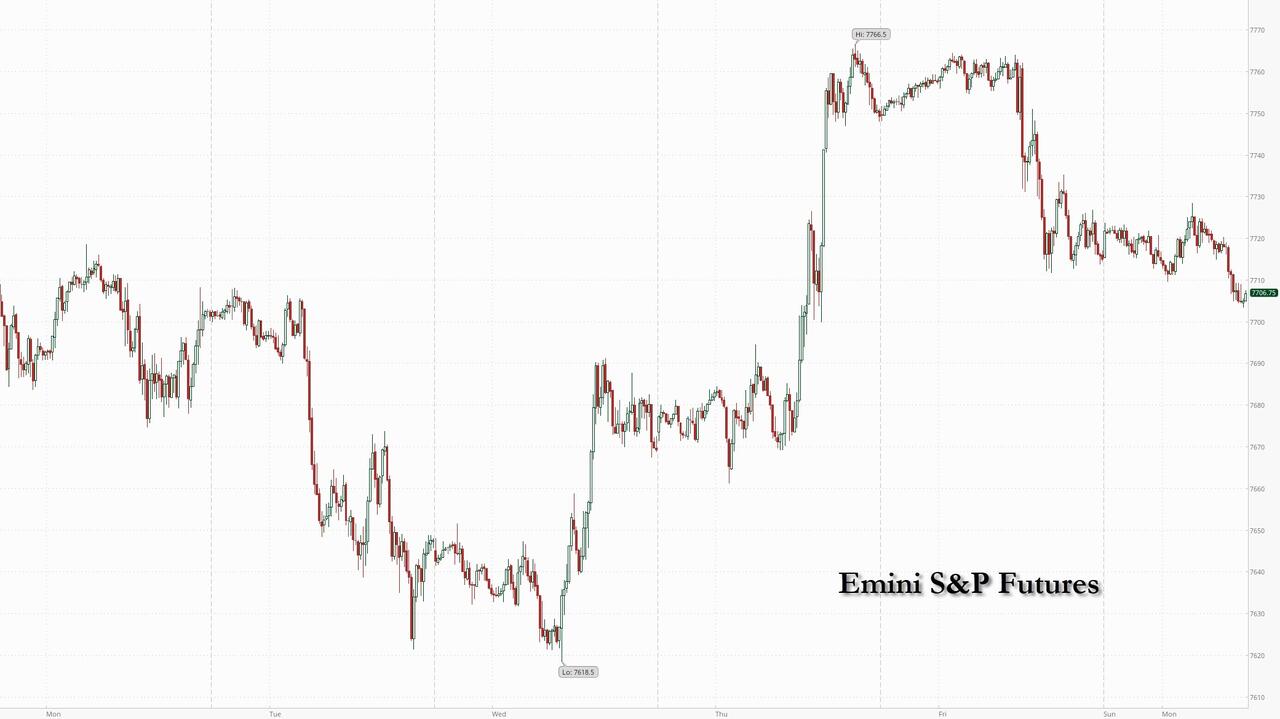
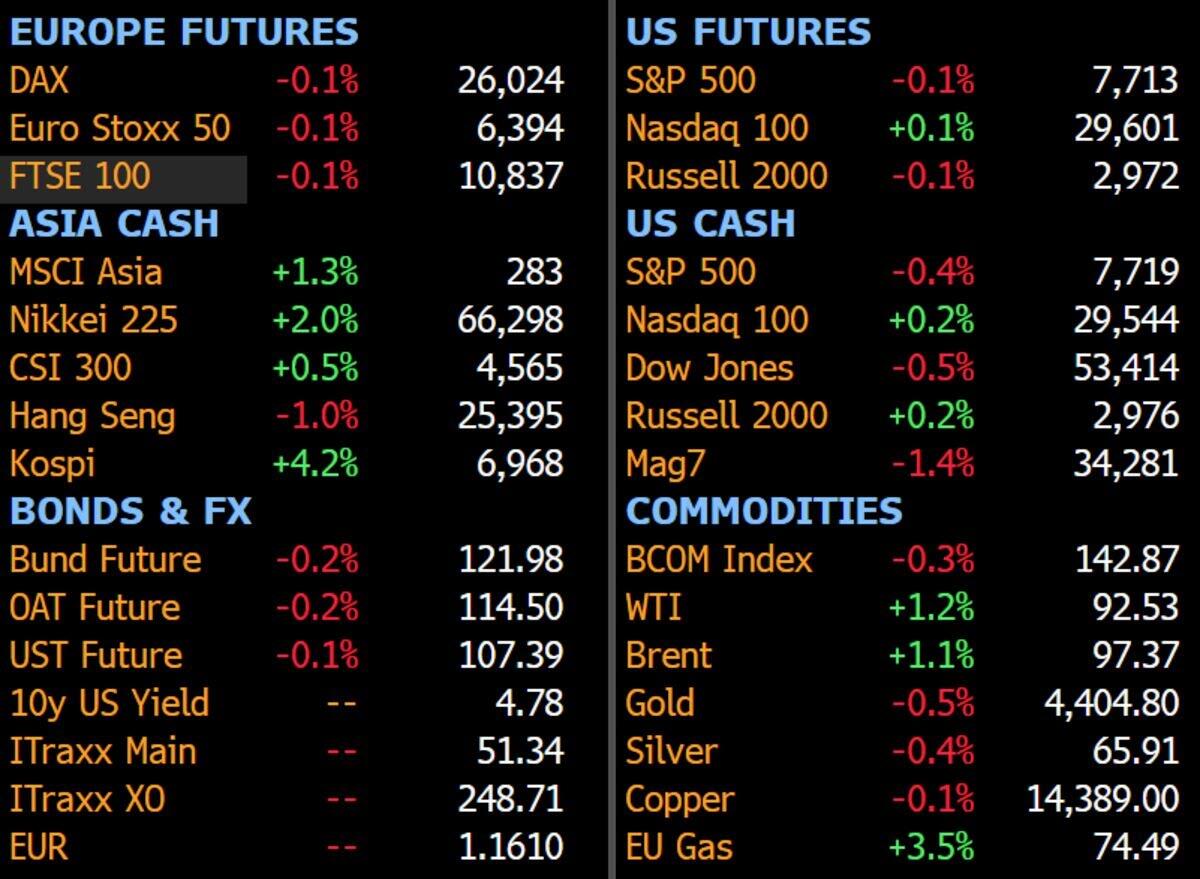
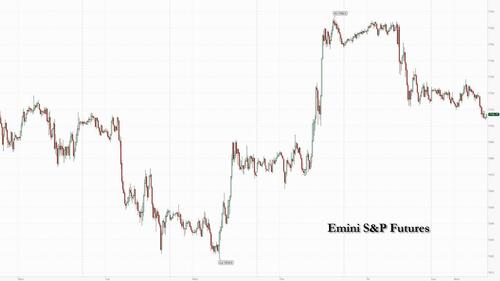
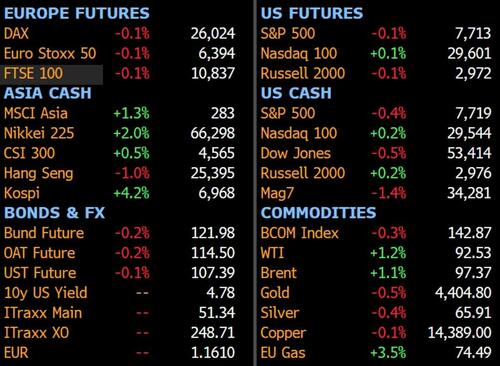
US stock futures slipped in cautious, low volume trading as the latest Middle East escalation pushed oil prices higher, lifting bond yields in Europe and Asia. As of 9:00am ET, S&P futures were down 0.2% with Nasdaq futures modestly in the red despite solid performance for tech stocks earlier in the session, which helped the Kospi surge more than 4.6% - its second biggest jump since the Situational Awareness takeover by Citadel - and Nikkei jumped almost 2% as OpenAI’s GPT-6 Astra debut reinvigorates the Asian semiconductor rally. Taiex climbs about 1.5% and ChiNext soars 2.6% (as discussed overnight, China may be the next Gamma Squeeze target). Hang Seng underperformed peers with a 1% loss as Chinese tech stocks retreat in Hong Kong. Brent crude rose above $97 a barrel following the largest exchange of tanker attacks yet between Iran and the US. Traders also assessed reports of hits on Saudi Arabian oil infrastructure and a potential accord between Iran and Oman to manage shipping through the Strait of Hormuz. In FX, the yen strengthened to its highest level since February, surpassing the peak reached after July’s intervention. The dollar fell 0.2%. Cash trading in Treasuries and US equities was closed for Labor Day. US markets are closed for Labor Day. 
In corporate news, an Amazon.com Inc. cargo plane overran a runway at Miami International Airport and burst into flames on Sunday, killing at least five people and temporarily shutting down the airport’s runways.

  • Jaguar Land Rover Automotive Plc will slash some 4,000 jobs as Britain’s largest carmaker grapples with US tariffs, the fallout of a crippling cyberattack and intense competition.
  • Novo Nordisk A/S stopped two more trials for its experimental heart disease medicine, in a further blow to the drug’s prospects.
  • Abu Dhabi National Oil Co. is in talks with the biggest refining companies in Thailand and Africa to invest in their businesses.
  • Uber Technologies Inc. has hired banks to hold calls with investors this week for a debut euro bond sale.
  • Novartis AG suffered a second trial disappointment within a week after the Swiss pharma group’s potential blockbuster heart drug failed in a final-stage study.

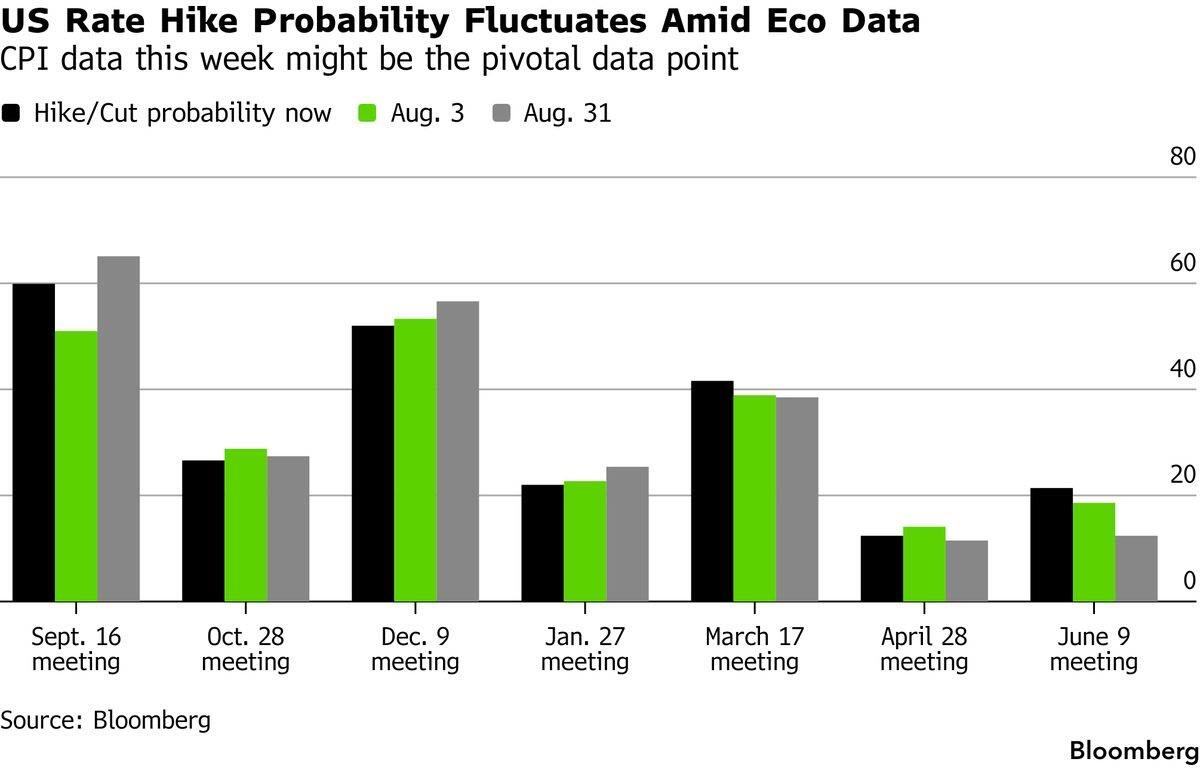
US cash trading and individual stock futures are shut today for the Labor day weekend. For anyone catching up after a break, Friday’s US jobs report did the early work on this week’s story. Payrolls rose 162,000, blowing past estimates, and pushed the market-implied odds of a Federal Reserve rate hike on Sept. 16 to a little above 60% from around 50% before the print.
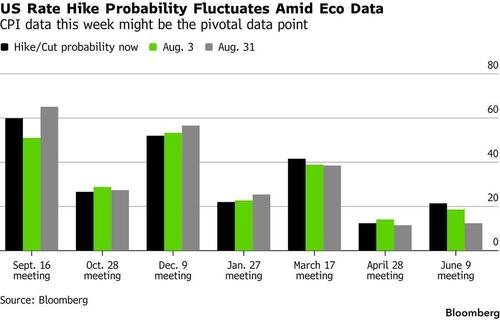
That leaves Friday’s CPI (and to an extent Thursday’s PPI) as the real swing factor for a Fed that’s held steady for five straight meetings. The European Central Bank adds its own test Thursday, with markets pricing a near-certain quarter-point hike to a 2.50% deposit rate. Between the two central banks and Friday’s CPI, this is the week Europe has to trade around.

“Markets will be adjusting their positioning heading into the Fed’s blackout period. The risk is the Fed turning hawkish and that will be reflected in equities,” said Geoff Yu, a senior macro strategist at BNY. “Bond markets will remain nervy and we remain focused on fixed-income volatility.”

While economic data will likely be the biggest catalyst for markets this week, earnings will also help shape the outlook for key equity sectors. Results from Oracle Corp. and Adobe Inc. on Thursday will give investors a fresh read on AI infrastructure demand and the threat the technology poses to software makers. For now, the earnings backdrop remains supportive. Investors should buy any dips in equities given a robust earnings outlook, said JPM strategists. Even moderate central bank tightening would be unlikely to derail the positive backdrop for stocks unless inflation expectations change materially, said the team led by Mislav Matejka. “As corporate profits remain on an uptrend, any bout of weakness in equity prices would leave them cheaper,” the strategists wrote. “We believe one should continue using the dips to add.”

The Stoxx 600 struggled for direction, with economically sensitive sectors among the biggest decliners as inflation concerns drove bond yields higher. Novartis AG shares fell 2.6% after a heart drug failed in a final-stage study. Energy stocks outperformed, while the real estate and insurance sectors were among the biggest laggards. Here are the biggest movers Monday:

  • Nordex shares rose as much as 12%, the most in over four months, after being upgraded to buy at BofA Global Research
  • SigmaRoc rose as much as 13%, the most since March 2021, after the lime and minerals group released its interim results and announced the acquisition of Lithuanian dolomite business AB Dolomitas
  • Lottomatica shares gained as much as 8.2%, hitting the highest since June, after the Italian gaming company quantified the boost to online earnings it expects from the proposed acquisition of Spanish rival Cirsa Enterprises
  • Infineon shares rose as much as 3.9% as MP Capital Markets upgraded the stock to buy from hold
  • Burkhalter shares rose as much as 6.7%, the most since March 2022, after the Swiss building technology services company reported results
  • Novartis shares fell as much as 3.9% after the Swiss pharma group’s potential blockbuster heart drug, pelacarsen, failed in a final-stage study
  • Schindler dropped as much as 3.6% after Goldman Sachs gave the elevator and escalator specialist its only sell rating, downgrading from neutral, citing lower growth and earnings progression compared to the wider sector
  • Tomra shares fell as much as 10%, while Norwegian-listed peer Envipco also slumps, after France abandoned plans to impose a mandatory deposit return system for plastic bottles, introducing doubts over a potential growth catalyst for the stocks
  • Hollywood Bowl shares dropped as much as 6%, the most since May 2025, after analysts at Deutsche Bank cut their price target and warned the summer drought created “less-than-ideal conditions” for the provider of indoor family entertainment

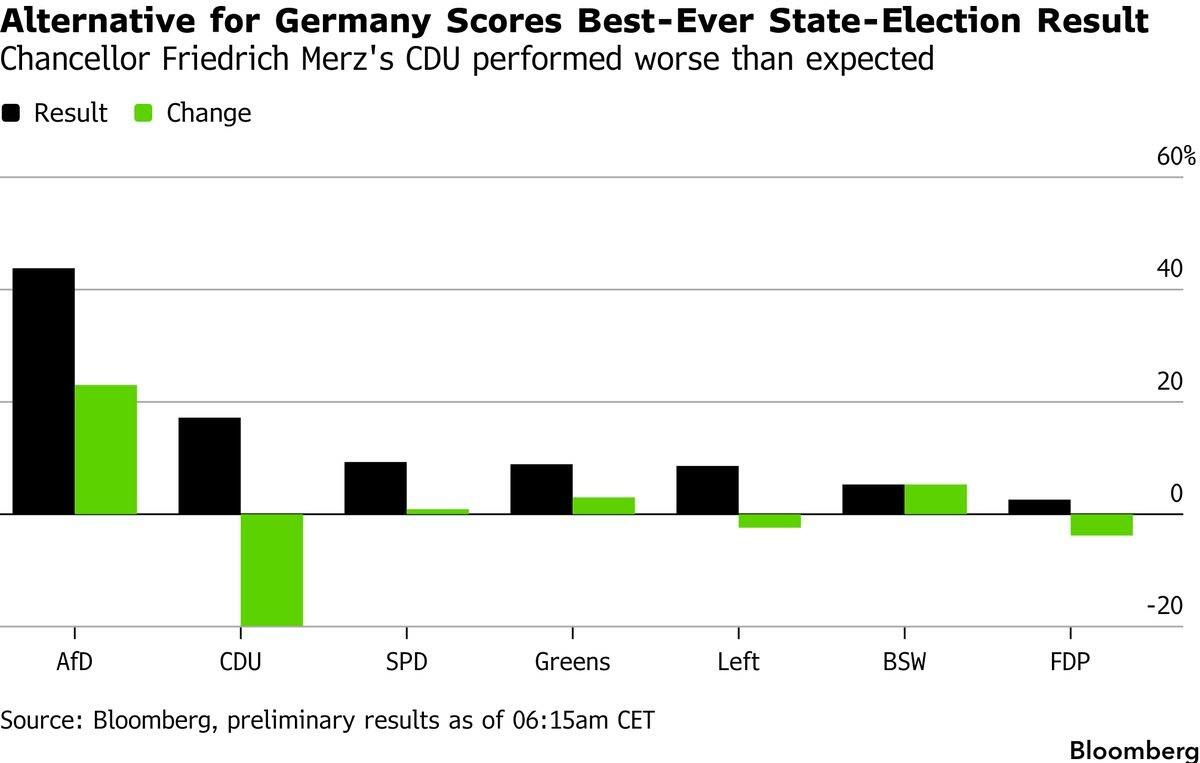
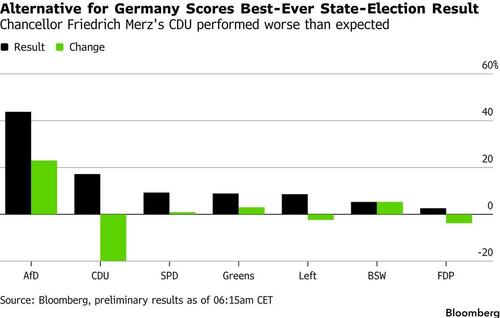
German establishment politics, and specifically Merkel's pro-immigration legacy, suffered a crushing blow over the weekend, after the conservative Alternative for Germany scored its best-ever result in a state election on Sunday, delivering a powerful blow to liberal Chancellor Friedrich Merz. The AfD secured 44% of the vote in Saxony-Anhalt. In the UK, the government signaled it won’t provide financial support to limit job losses expected to be announced at Jaguar Land Rover this week.
South Korea’s memory heavyweights were standouts in Asia as the release of OpenAI’s GPT-6 model continued to fuel renewed enthusiasm for AI. Driving the tech rally is OpenAI’s plan to release a new model, GPT-6, pitched as a milestone toward artificial general intelligence. That pushed the Philadelphia Semiconductor Index up 3.4% on Wall Street Friday and has SK Hynix and Samsung leading the advance in Asia Monday. The enthusiasm isn’t universal though. Hong Kong’s Hang Seng and its tech gauge both slipped into the red despite the Nikkei and Kospi seeing solid gains.

The dollar initially ticked higher, but then retreated following another surge in the yen which pushed the USDJPY as low as 154, down almost 200 pips overnight. The Korean won extended winning streak to around two-year high. T-note futures are about 1/32 softer near 107-14 with cash Treasuries closed for Labor Day. Bund futures are ~15 ticks lower after German far-right party AfD wins state election. Aussie curve bear flattens with 3-year yield ~3 bps higher. WTI crude futures climb 1% to near $92.40; gold sheds almost $30 to below $4,400-handle.

The notable overnight mover was again the yen, which strengthened to its highest level since February, surpassing the peak reached after coordinated intervention by Japan and the US. The Japanese currency suddenly extended gains, up as much as 1.4% to 154.06 against the dollar in London trading. There was no clear driver for the move, with some traders pointing to the US holiday helping to exaggerate the moves while others mentioned the break of the key 155 per dollar level as a reason.  The yen’s break below 155 is significant given the level previously acted as a floor following past intervention episodes,” said Masahiko Loo, senior fixed income strategist at State Street Investment Management.

Large stop-loss orders below the 155-per-dollar level were triggered and options dealers were forced to sell dollars, adding to the yen’s gains, according to a trader familiar with the transactions who asked not to be identified because they aren’t authorized to speak publicly.

China, separately, said it’s injecting 300 billion yuan ($45 billion) into its largest banks and insurers, its biggest recapitalization in almost two decades, with only a modest share reaction so far. 

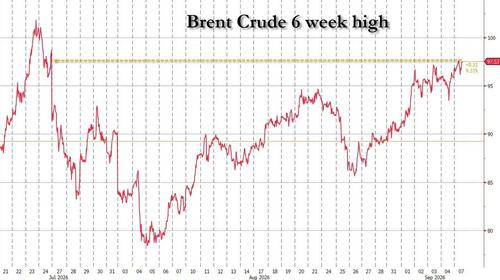
In commodities, oil advances, with Brent futures are trading at a 6 week high, above $97 a barrel, after US attacks on Iranian tankers and Tehran’s threat of a new restricted zone outside the Strait of Hormuz. Over the weekend, Iran said it hit three US-linked ships in retaliation for American attacks on Iranian tankers. The US military earlier said it struck three Iranian crude tankers, in response to the IRGC targeting two US Navy warships with ballistic missiles. European natural gas prices surge. Meanwhile, Ukraine is resigned to Russia’s war dragging on through another tough winter.
In rates, japan likely sold a portion of its holdings of foreign securities, including US Treasuries, to finance its record currency intervention over the past month. Treasury futures edge down. There’s no trading of cash Treasuries worldwide on Monday because of a US public holiday.

Market Snapshot
Top Overnight News

  • Saudi Aramco’s oil facilities in the Saudi Arabian city of Jizan have been attacked only a month after a separate strike temporarily knocked out some production at its refinery.: FT
  • Iran says US energy companies' facilities are 'exposed': RTRS
  • UAE says its energy exports will not be 'held hostage' by Iran war: RTRS
  • Several Qatari liquefied natural gas tankers are heading back toward the Persian Gulf, a sign the supplier may be positioning vessels for a resumption of exports through the Strait of Hormuz: BBG
  • The Alternative for Germany scored its best-ever result in a state election on Sunday amid growing public discontent with the political establishment, delivering a powerful blow to Chancellor Friedrich Merz: BBG
  • AI could pose 'existential' risk to humanity, UN rights chief warns: RTRS
  • From dance floor to war: China readies humanoid robots for combat: RTRS
  • Japan likely sold a portion of its holdings of foreign securities, including US Treasuries, to finance its record currency intervention over the past month, despite concern in Washington over the impact of Treasury sales on long-term yields: BBG
  • The South Korean won advanced to its strongest level in nearly two years Monday, helped by a rally in semiconductor stocks and continued foreign inflows into the country’s benchmark equity index: BBG
  • Nepal rescuers focus on 900 hydropower workers, 121 could be trapped in tunnels, officials say: RTRS
  • German industrial production declined the most in almost a year, marking an unexpected setback to the recovery of Europe’s biggest economy: RTRS
  • Fed's Hammack (2026 voter) said on Friday that Fed policy is not restrictive and inflation is too high, while she stated local contact views indicate now is the time for a Fed hike to control inflation.
  • Huawei launches new foldable smartphone; Xiaomi and Apple set to follow: RTRS
  • Warning signs abound for Republicans as midterm campaign begins final sprint: RTRS
  • President Trump said on Friday that they are taking action to help cattle ranchers and signed an order that allows ranchers to process their own beef, while small, medium, and large ranchers can sell to consumers, and he also stated that meatpackers have been charging unsustainable prices.
  • There were multiple casualties after an Amazon (AMZN) cargo plane overran the runway and struck vehicles whilst landing at Miami International Airport, while the Miami-Dade County Sheriff announced that at least five people have been confirmed dead.

Iran Headlines

  • US launched strikes against three Iranian crude oil tankers on Saturday, which destroyed one, in retaliation for the IRGC targeting US Navy warships with ballistic missiles.
  • Iran’s navy said it targeted three oil tankers that were travelling through unauthorised routes in the Strait of Hormuz and three additional US vessels in other areas.
  • US President Trump said on Friday that they do intermittent strikes in Iran and that the Iran issue is a military conflict, while he added that they may hit Pickaxe Mountain very soon. Trump warned that if anything goes badly with Iran, they may hit them hard and have essentially taken over Iran. He also claimed there have been no shootings for days and there are no mines in the Strait.
  • US Energy Secretary Wright said a nuclear deal with Iran may not be achievable in the near term and military action may be needed to address threats from Iran, according to ABC News.
  • Iran's top security official Rezaei said Iran and Oman will sign agreed Strait of Hormuz passage maps in the coming days and that Iran will commit to keeping the Strait of Hormuz open when the US neither threatens Iran nor attacks it. Rezaei also stated that they will announce in the coming days and weeks a restricted zone outside the Strait of Hormuz that starts from the US Navy's blockade line and extends through the strait into the Persian Gulf, and any ship identified entering this zone with the intention of passing through the strait will be added to the sanctions list. Furthermore, he said that Iran tested an Iranian anti-ship missile above a US warship for the first time and claimed the missile created 'hell' for the Americans 'and they fled'.
  • Iranian Parliamentary Speaker Ghalibaf warned that Iran’s response to any attack against its interests and security would be faster, heavier and more painful.
  • Iran's Foreign Ministry said the US-led war is disrupting global oil trade and costs, while it added that US aggression is causing instability in the Strait of Hormuz.
  • Israeli military announced that it struck southern Lebanon after Hezbollah launched drones towards Israeli soldiers in the security zone. Israel's army also issued an evacuation warning to residents of a building in Deir Zahrani, southern Lebanon.
  • Israeli Finance Minister Smotrich said PM Netanyahu ordered the evacuation of certain settlement outposts in the West Bank. It was separately reported that Israel conducted an airstrike on eastern Gaza City with four missiles.
  • Joint statement by UAE, Saudi Arabia, Qatar, Jordan, Indonesia, Pakistan, Turkey and Egypt Foreign Ministers strongly condemned statements made by Israel's National Security Minister Ben-Gvir and Defence Minister Katz regarding the displacement of Palestinians.
  • Yemeni armed forces said they thwarted an attempt by Houthis to infiltrate the Dabab front, while they announced that warplanes struck Houthi positions in Balhaf and south of Hodeidah.

A more detailed look at global markets courtesy of newsquawk

APAC stocks traded mixed as the region reflected on the recent strong US jobs data and subsequent Fed rate hike bets, as well as the US and Iran tit-for-tat attacks on vessels in the Strait of Hormuz. ASX 200 was little changed as resilience in the energy, resources, materials and mining sectors is offset by underperformance in tech, utilities and telecoms, but with downside in the index cushioned by support at around the 9,000 level. Nikkei 225 gapped above the 66,000 level with tech-related stocks heavily represented in the list of biggest gainers in the index. KOSPI outperformed amid firm gains in the semiconductor giants, including SK Hynix, which is said to be sharply increasing the production share of its sixth-generation 10nm-class 1c DRAM. Hang Seng and Shanghai Comp lagged with the Hong Kong benchmark pressured amid underperformance in the likes of Baidu and Xiaomi, while the big banks also declined after reports that ICBC and AgBank plan large A-share placements to raise CNY 100bln and CNY 160bln, respectively, as part of a Beijing-led CNY 360bln capital injection in financials.

Top Asian News

  • US President Trump said on Friday that he will be hosting a state dinner for Chinese President Xi when he comes and that China has very little involvement with Iran.
  • China’s Finance Ministry announced it will lead a capital injection of CNY 360bln in state banks and insurers, with ICBC (601398 CH) planning to raise CNY 100bln to bolster its capital, and Agricultural Bank of China (601288 CH) to raise CNY 160bln through a private placement of A shares, while the insurers include China Life Insurance (601628 CH), China Taiping Insurance (966 HK) and People’s Insurance Company of China (601319 CH).
  • China unveiled a plan to strengthen rural investment and will boost rural revitalisation investments to boost agricultural productivity, while it will enhance bond and credit support for qualified agricultural initiatives.

European stocks were subdued and oil crept higher after tit-for-tat tanker strikes between the US and Iran. Novartis AG shares fell 2.6% after a heart drug failed in a final-stage study. The Stoxx Europe 600 Index was little changed by 1:10 p.m. in London. Energy stocks outperformed, while the real estate and insurance sectors were among the biggest laggards. 

Top European News

  • UK Chancellor Healey said Britain’s economic growth must extend beyond the largest cities as he prepares to outline his economic agenda in a major speech on Monday. He is reportedly to set to announce a GBP 150mln fund for northern firms, aiming to boost growth.
  • UK recruiters saw hiring pick up for the first time in four years in August, according to the FT citing a survey by KPMG and the Recruitment and Employment Confederation.
  • Hundreds of masked anti-immigration protesters blocked roads leading to Britain’s busiest ferry port in Dover on Saturday.
  • German Chancellor Merz warned about further losses of industrial jobs and said that they are losing industrial jobs on a large scale, although he welcomed the latest agreement on Volkswagen’s supervisory board.
  • Germany’s far-right AfD is set to win the election in the eastern German state of Saxony-Anhalt with 44.5% of the vote.
  • German police discovered 12 explosive devices near overhead powerlines in two districts in east Germany, which is the latest spate of incidents targeting Germany’s electricity infrastructure.
  • Greek PM Mitsotakis unveiled a package of economic measures including tax breaks and wage increases for pensioners and employees, with the measures costing EUR 3.5bln by 2030.
  • Fitch raised Portugal's sovereign rating from A to A+; Outlook Stable.

Tariffs/trade

  • US President Trump said Canada’s dollar imbalance with the US is unacceptable.
  • US President Trump said on Friday that they have the right to put tariffs on nations like Switzerland and have the right not to trade with financial elite countries, while he also stated that he gets along very well with Mexico's President.
  • Japanese Trade Minister Akazawa said progress was made on the USD 550bln investment initiative that was set up as part of a trade deal with the US.

FX

  • DXY struggled for direction after ultimately fading the knee-jerk uplift from the stronger-than-expected NFP report on Friday, with price action not helped amid the holiday closures in North America on Monday and with the Fed currently on a blackout period, while market participants will have to wait till much later in the week for US CPI data.
  • EUR/USD traded little changed just above the 1.1600 level, with the single currency unfazed by news that the German far-right AfD is set for a big election win in the eastern state of Saxony-Anhalt, but will fall short of achieving a majority. Separately, German Chancellor Merz warned about further losses of industrial jobs.
  • GBP/USD marginally softened although held on to the 1.3500 status, with participants looking ahead to comments from UK Chancellor Healey, who will outline his economic agenda in a speech today.
  • USD/JPY was range-bound on both sides of the 156.00 level in the absence of fresh catalysts from the US or Japan to begin the week, with both their central banks scheduled for key meetings next week.
  • Antipodeans conformed to the uneventful trade across the FX space amid the ultimately mixed risk appetite and with no tier-1 data to spur price action.
  • PBoC set USD/CNY mid-point at 6.7795 vs Exp. 6.7086 (prev. 6.7787)

Fixed Income

  • 10yr UST futures lacked direction after whipsawing in the aftermath of last Friday's blockbuster jobs report, while price action is contained with US cash markets closed on Monday for Labor Day.
  • Bund futures trickled lower and returned to beneath the 123.00 level amid mild gains in oil prices and with German Industrial Production data due later, while there was little impact from news that Germany's far-right was set for a major victory after elections in the eastern state of Saxony-Anhalt.
  • 10yr JGB futures were subdued in the absence of any major fresh drivers or tier-1 data from Japan.

Commodities

  • Crude futures mildly gained after the US and Iran conducted tit-for-tat attacks on vessels in the Strait of Hormuz during the weekend, but with upside capped as it was also reported that Iran's top security official Rezaei said Tehran will declare a restricted zone near the Strait of Hormuz and announce a new shipping route agreed on with Oman in the coming days and weeks.
  • Major OPEC+ countries stuck with the plan to keep oil output quotas unchanged for October.
  • Iraq raised oil export capacity to over 3mln bpd, according to state media.
  • US Energy Secretary Wright said the Trump administration is focused on boosting crude and fuel supplies rather than curbing US exports, as a way to reduce prices. Wright also said that US Navy escorts that are assisting tankers across the Strait of Hormuz are vital in sustaining crude flows and suggested they will continue to do so until Iran backs down.
  • Russia’s Vostok Oil project loaded its first crude for shipment via the Northern Sea route.
  • Iran is to increase gasoline prices for heavy consumers using more than 110 litres per month, effective on Tuesday.
  • Spot gold retested the USD 4,400/oz level to the downside following last week's stronger-than-expected US jobs data, which supports the case for the Fed to hike rates this month.
  • Copper futures ultimately declined with early indecision on the recent key market themes including US data, Fed rate expectations and ongoing geopolitical tensions.

Geopolitics: Ukraine

  • Ukrainian President Zelensky sees no quick end to the war with Russia following a meeting with US envoys Witkoff and Kushner, and is seeking a package from allies that would cover defence reinforcements, as well as energy, including US LNG.
  • Russian President Putin ordered troops not to fire on Kyiv for three days during US envoys Witkoff and Kushner's visit to Ukraine’s capital, according to Kremlin spokesman Peskov. However, it was reported that Russia and Ukraine exchanged a wave of strikes prior to the US envoys’ visit to Kyiv.
  • Russian Kremlin aide said talks between Russia and the US were highly useful and lasted for over three hours, but gave no indication of a breakthrough.
  • White House official said US and Russian officials discussed substantive plans for the next steps in talks aimed at ending Russia’s war in Ukraine, which will be announced in the coming weeks.
  • France’s far-right National Rally chief Bardella wants Ukraine to pay for Europe’s help and said France’s unconditional support for Ukraine should be replaced by a more transactional relationship.

Geopolitics: Other

  • North Korean leader Kim said North Korea's navy nuclear armament will put nuclear combat systems to practical use and will restrain the enemy's invading fleet, while he added that their new warship can carry out annihilating retaliatory strikes on the enemy at any time.

DB's Jim Reid concludes the overnight wrap

Morning all. Tough times in our house this weekend with 8 nine-year-old boys sleeping over for our twin's birthday party. They were very noisy. However, we were kept awake not by them but by an illegal rave in a field a few hundred yards away. I say we but my hearing isn't the best so I didn't hear it. My wife has the hearing of an owl and couldn't sleep through it and felt that I should be woken up to be made aware of the noise I couldn't hear. So I could do with the weekend to start again. Thankfully it's US Labor Day so it should be relatively quiet.  

I was asked to do an op-ed for the FT today on the recent yield sell-off in bond market. As I said in the piece, the moves over the summer are just another leg to the normalisation trade that has been going on post Covid. In the unlikely event that you'd been on a desert island since just before the GFC and came back ashore today, I'm sure you'd look at current yields as pretty normal given all the spot info and history of bond markets you had at your disposal. I also don't think the recent concerns are fiscal related, even if the higher yields go the more worries we will have further down the line for several countries. Finally while the pressures that have been there for higher yields are likely to continue, we have to accept that bonds are being bonds again. That is the coupon is helping maintain returns even in the face of yield rises. For example, its been nearly 4 years since the UK mini-budget crisis and 10yr Gilt yields are +65bps than the peak, while index returns are up around 12%. Clearly not spectacular but its getting harder to get outright negative returns in government bonds over the medium-term. So while the news flow will likely to continue to be negative, at least bonds are being bonds again. See my op-ed at the FT here for more. 

The main headline this morning is Germany’s political landscape shifting further to the right after the AfD secured around 44% of the vote in the Saxony-Anhalt state election yesterday, its strongest result in any German election to date and more than double its support from 2021. Chancellor Friedrich Merz’s CDU slumped to roughly 17%, its weakest showing in the state, as voters expressed growing frustration over economic stagnation, energy costs and migration policy. While the AfD fell just short of an outright parliamentary majority, the result nonetheless marks a major symbolic breakthrough for a party that remains shunned by mainstream rivals under Germany’s long-standing political “firewall”. The outcome will intensify pressure on the federal government and is likely to reinforce concerns about political fragmentation. More broadly, it underlines how anti-establishment and populist parties continue to gain traction across parts of Europe despite robust labour markets and relatively subdued inflation.  

The main focus in the Iran conflict over the weekend was a tit-for-tat escalation targeting commercial shipping in and around the Gulf. According to Reuters and other major news agencies, several tanker incidents and maritime attacks heightened concerns about the security of energy supplies moving through the Strait of Hormuz, with both sides accusing each other of responsibility. Brent is up +1.05% this morning to $97.29/bbl so we remain a distance from a resolution.

Elsewhere in overnight markets, tech is lifting most boats with the KOSPI (+4.18%) leading gains, followed by the Nikkei (+1.87%). Chinese equities are mixed, with the CSI 300 (+0.19%) edging higher, while the Hang Seng (-0.97%) and Shanghai Composite (-0.34%) are underperforming and bucking the broader regional trend. S&P 500 futures (-0.11%) are trading slightly lower but activity will be light today due to the Labor Day holiday. The Yen is fairly flat after another hectic week of intervention stories.

Looking forward now and the coming week offers a busy mix of central bank decisions, inflation data and growth indicators across the major economies. The main global focus will undoubtedly be on the US inflation reports (including CPI on Friday) and the ECB policy meeting (Thursday) with the former likely to heavily influence the FOMC next week. Elsewhere, investors will look to China’s trade (tomorrow) and inflation data (Wednesday), UK monthly GDP (Friday), and industrial production releases in Germany (today) and France (Wednesday). Corporate earnings are relatively light but Oracle (Thursday), Adobe and Inditex are among the notable releases.
As noted above, the biggest event is likely to be the US August CPI report (Friday), arriving just days before the September 16 FOMC meeting. The release follows a stronger-than-expected August employment report last Friday that reinforced the view that the labour market remains resilient. Nonfarm payrolls rose by 162k, with a further 55k of upward revisions to the previous two months. Private-sector hiring remained firm (127k) and job gains continued to broaden beyond healthcare, while measures of labour demand improved further.

Although the unemployment rate edged up to 4.14%, the broader U-6 measure fell to 7.7% and participation increased to 61.6%, suggesting the labour market remains on a relatively stable footing. Overall, the report corrected some of the softer signals seen in July and supports the view that employment growth remains at or slightly above breakeven levels.

Attention now turns to inflation. Our US economists expect headline CPI (Friday) to rise by +0.38% month-on-month in August, up from +0.07% previously, while core CPI is expected to print at +0.21% month-on-month, broadly unchanged from July’s +0.22%. Higher gasoline prices are likely to support the headline reading, while core inflation should continue to benefit from gradually moderating shelter costs. If realised, the forecasts would leave headline CPI broadly unchanged at 3.38% on a year-on-year basis while core inflation edges 10 bps lower to 2.38%.

Ahead of that, the PPI (Thursday) will provide another important input into the inflation outlook. Our US economists expect PPI to imply a +0.21% month-on-month increase in core PCE, down from +0.25% in July, leaving the annual rate broadly stable. The remainder of the US calendar is relatively quiet, with markets closed today for the Labor Day holiday. However, the preliminary University of Michigan consumer sentiment survey (Friday) will also attract attention. Our US economists expect sentiment to improve to 52.5 from 51.7 in August, while the survey’s inflation expectations measures will be closely watched.

In Europe, the ECB policy decision (Thursday) will be the key event. Our European economists expect a 25bp rate increase, taking the deposit rate to 2.50%, and investors will focus on any guidance regarding the likelihood of further tightening. Our economists now expect an additional hike in December with the reasons explained in their preview note here. They have also upgraded their 2026 and 2027 economic forecasts by 0.3pp and 0.1pp to 0.8% and 1.2% respectively. See their note on it here.  Economic data will also be closely monitored, including German industrial production (today) and trade data (tomorrow), French industrial production (Wednesday), and UK monthly GDP (Friday). Inflation releases from Sweden (today) and Norway and Denmark (Thursday) will provide additional insight into regional price pressures.

In Asia, China will dominate the calendar. Our economists expect the August trade balance (tomorrow) to show stronger activity, with exports and imports forecast to grow a significant 27% and 29% year-on-year respectively. Inflation data (Wednesday) are expected to show CPI accelerating to 0.8% year-on-year from 0.5%, while PPI inflation moderates to 3.2% from 3.5%. In Japan, key releases include labour cash earnings and the Economy Watchers survey (tomorrow), followed by PPI data (Friday).  A reminder that the BoJ has an important meeting on Friday week, less than 36 hours after the FOMC conclusion.

Beyond the economic calendar, the US Treasury’s expanded long-end buyback programme begins on Wednesday, increasing support operations in longer-dated maturities. In politics, the US Republican Party will hold its first midterm national convention in Dallas on Wednesday and Thursday, while Canada’s counter-tariffs on US imports come into force tomorrow. Corporate earnings highlights include Inditex (Wednesday) and Adobe and Oracle (Thursday). Oracle will be the key given all the focus on AI capex.  

Recapping last week now and risk assets struggled to gain much traction, as a fresh rise in energy prices raised fears about more persistent inflation. That came amidst no signs of progress on reopening the Strait of Hormuz, with Brent crude oil up +7.80% last week (+0.80% Friday) to $96.28/bbl, their highest in six weeks. Moreover, the relentless rise in European natural gas futures continued, with a 4th consecutive weekly gain (+7.42%) last week (+0.20% Friday) to €72.00/MWh. So for Europe in particular, investors were pricing in a growing probability of a more inflationary shock.   

That backdrop helped push yields up to multi-year highs around the world. For instance in Germany, the 10yr bund yield was up +6.1bps last week (-0.4bps Friday) to 3.34%, and it even reached a post-2011 high of 3.37% on Wednesday. Meanwhile in the US, the 10yr yield was up +6.3bps last week (+1.4bps Friday) to 4.78%, and on Tuesday it closed at 4.80%, its highest since October 2023.   
The yield moves got further momentum on Friday from a very strong US jobs report, which showed payrolls up by +162k in August (vs. +55k expected). In addition, there were +55k of upward revisions to the previous two months, and the unemployment rate held steady at 4.1%. So that raised investors’ confidence that the Fed would likely hike rates at their September meeting, with futures pricing in a 62% chance of a hike by the close on Friday.   

With inflationary pressures mounting and yields rising further, that generally put pressure on risk assets around the world. That was particularly clear in Europe, where the STOXX 600 fell -0.81% last week (+0.12% Friday), whilst the DAX fell -1.97% (+0.17% Friday). Elsewhere, Japan’s Nikkei also fell -2.09% (+1.26% Friday), while the MSCI EM index rose +0.24% (+1.35% Friday). In the US, equities saw a relative outperformance, but even there, the S&P 500 was still barely up last week with a +0.09% gain (-0.38% Friday). That slight risk-off tone was seen in credit as well, as US IG (+2bps) and HY (+7bps) spreads both widened, as did Euro IG (+2bps) and HY (+8bps) spreads.

Tyler Durden Mon, 09/07/2026 - 09:22

Hartnett: A Democratic Sweep Will Trigger A Stock Market Rout, And Pop The AI Bubble

Hartnett: A Democratic Sweep Will Trigger A Stock Market Rout, And Pop The AI Bubble

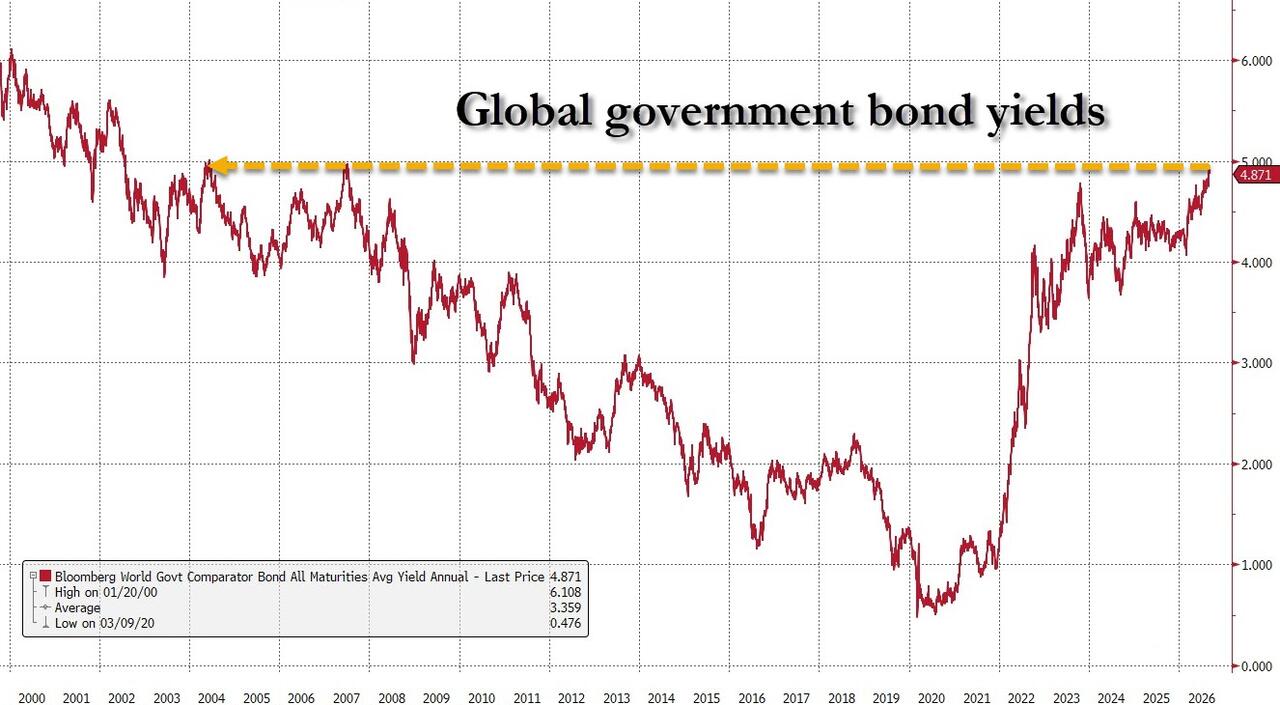
The biggest story last week was not the unexpectedly hot jobs report which, unfortunately, will be revised sharply lower next month as the labor market reverts to its deteriorating, AI-enhanced, trendline: Instead, what everyone was - or should have been focusing on - was the bottom falling out of the bond market with global yields jumping to the highest level in 2 decades, to wit: 

  • 10Y Treasury yields jumping to 4.81%, near 2008 crisis levels
  • 30Y Treasury yields jumping to 5.31%, highest since 2007
     
  • Japan 10Y JGB  >3.0%    First time since 1996
  • Japan 30Y JGB  4.2%, or 4x the BoJ policy rate
     
  • German 10Y Bund  3.38%, post-2011 high
  • France OAT-Bund spread 88bps, 2012 crisis highs
  • Italy BTP-Bund spreads, 84bps, 2012 highs

A Bloomberg index of global bond yields just rose to the highest since 2007, and is just 1% away from the highest levels this century.

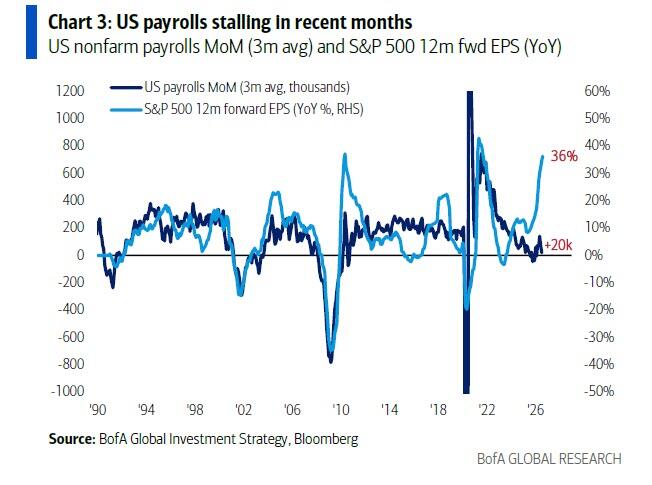
Appropriately, the topic of soaring bond yields is also the kick-off theme of the latest weekly Flow Show (available to pro subs) from BofA's Michael Hartnett, who writes that with a 99% probability the ECB hikes Sept 10th, 53% Fed hikes on 16th, 98% BoJ hikes 18th (per Bloomberg futures pricing), the hikes are coming fast and furious as central banks try to restore credibility to ward off surge in bond yields (which, as we have discussed extensively, is now the biggest threat to AI capex and the K-shaped consumer booms). In light of this, Hartnett says that if the Fed does hike despite stalled payrolls...

... then it will restore credibility and make sure the current "peak yields" don't go higher, it's also why to Hartnett, duration (RTY, XBI, KRE, REIT) keeps working despite surging yields and why "nouveau-leveraged" Mag7s are on the cusp of upside breakout. On the other hand, if the Fed does not hike - as Trump made painfully clear he will not approve - or even merely keeps rates on hold, then all bets are off, as is the Fed's credibility because for all his rhetoric, Warsh will prove to be "just one more of the guys."

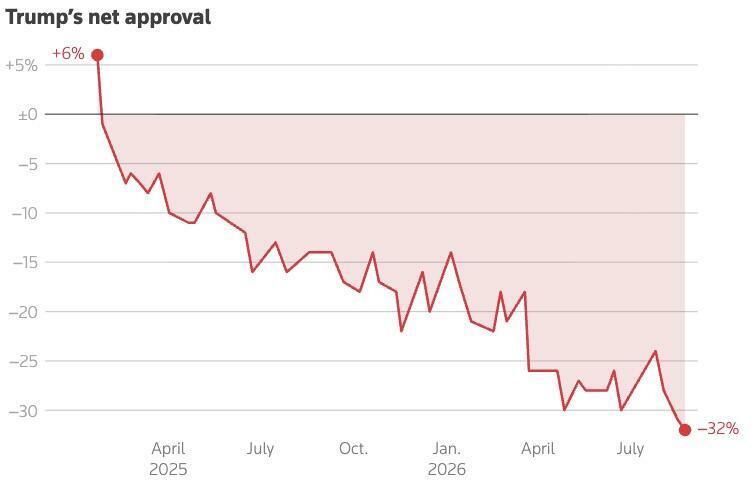
Of course, it's not just the Fed: with Trump approval ratings the lowest on record...

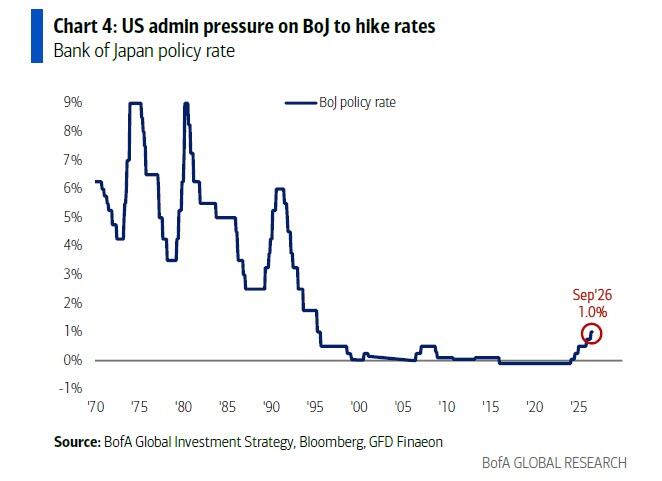
... as a plurality of Americans say the most important problem facing the country is "the economy, unemployment and jobs" (followed in distant second place by those who said "threats to democratic values and norms"), Hartnett says that the White House is realizing that $4/gallon gas, 160 dollar-yen, 5% Treasury bond yields are "Maginot Lines" for the US admin, hence policy interventions via FX, bond buybacks, monetary policy (pressure on BoJ to raise policy rate that’s averaged 0.1% this century)...

... and why the policy panic working for now (see the surging Japan yen); or, as Hartnett described a month ago, global markets are subject to “whatever it takes” policies to maintain nominal macro boom and asset price bull...  and why Hartnett says to stay long commodities and debasement hedges, e.g. gold.

To be sure, this observation doesn't exist in a vacuum, and sits neatly inside a coherent set of themes Hartnett has been pushing over  the past several weeks: 

  • "Bonds boss the bubble." His view is that long-dated yields - not equity stories - now dictate the AI trade, captured in his line from a week ago that "bonds trade information, equities trade ideas." He argues AI spenders and builders will keep underperforming AI adopters until global 30-year yields fall below 5%, and that the market is currently priced for a "perfect consensus": no landing, no Fed hike, no AI capex cut, and no Democratic sweep (which will inevitably disappoint).
  • Stay long commodities and gold. With "whatever-it-takes" fiscal intervention holding down long-end yields, Hartnett has kept commodities and gold as the core inflation/geopolitical hedge. 
  • The midterms are the contrarian flip. His base stance is long equities / short bonds, but he carves out a tactical exception: if Democrats look poised to sweep both chambers, a 10%+ equity selloff becomes likely, making bonds the contrarian Q4 buy. Investors have largely shrugged off election risk so far, which is exactly why he sees the asymmetry.
  • The AI bubble is "fit to burst." In related commentary he laid out a post-bubble playbook — "long humiliation, short hubris" — favoring long bonds plus defensives (consumer staples, mining/materials, healthcare) over the crowded AI-buildout names, noting hyperscaler free cash flow has turned negative under buildout commitments.

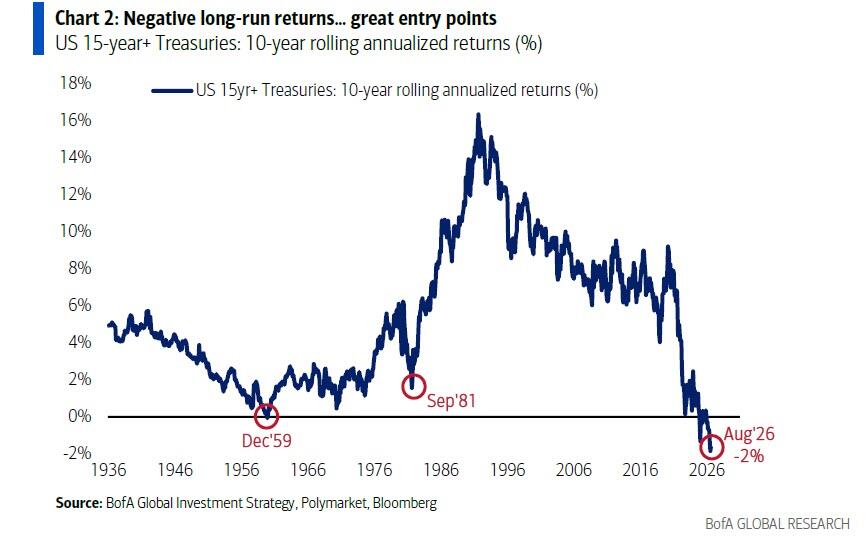
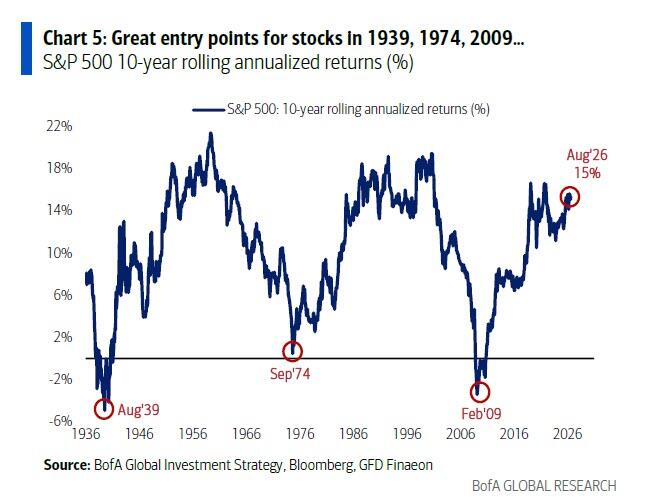
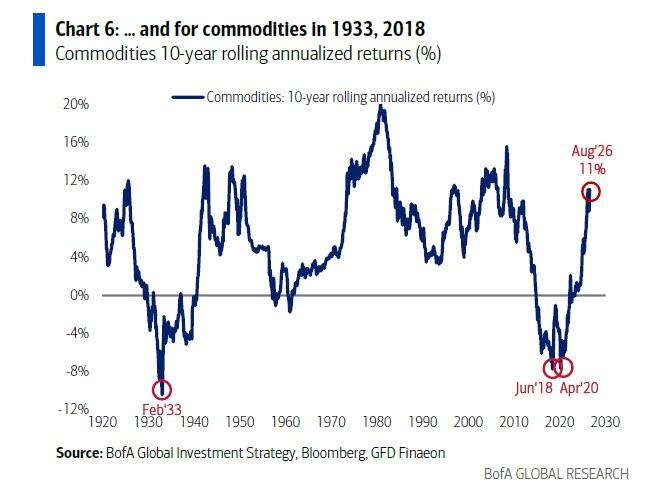
As Hartnett continues to hammer the rising bond yield theme, he next takes a somewhat contrarian view, and notes that the 10-year rolling return from US stocks is 15%, commodities 11%... while Treasuries are -2%, the worst of the past 100 years.

For bond bulls (if any are still left, now that even career bond bull Lacy Hunt turned bearish) this is a good sign: as the next two charts show, negative long-run returns have been a great entry points for stocks in 1939, 1974, 2009...

... and commodities in 1933, 2018.

And while the US midterms are not a “regime change” election like Thatcher/Reagan in 1980, or BREXIT/Trump 2016, a Fed hike, TSY buybacks, signal a rising risk the midterms show the biggest voter priority is “affordability” not lower taxes, faster AI data center expansion... which is why to Hartnett lower Q4 yields remain a very good contrarian play.

Hartnett's latest Flow Show then pivots away from bond yields, and to the main topic of the week, namely the upcoming midterms (appropriately just as we penned "Democrat Sweep? Here Are JPMorgan's Midterm Trades - And Why Gridlock Pays"). The BofA strategist believes that for all the posturing, the midterms are not a “regime change” election, e.g. Thatcher/Reagan in 1980 = end of inflation/start of bond bull, BREXIT/Trump in 2016 = end of globalization = start of commodity bull;

Alas the coming midterms are unlikely to change the trajectory of US government spending (which will keep rising until it is forced to stop); Hartnett views that 2020s as a decade of political populism as MAGA (Reform party in UK) and Democratic Socialists of America (Greens in UK) represent the culmination of post-GFC Tea Party and Occupy Wall St insurgents. 

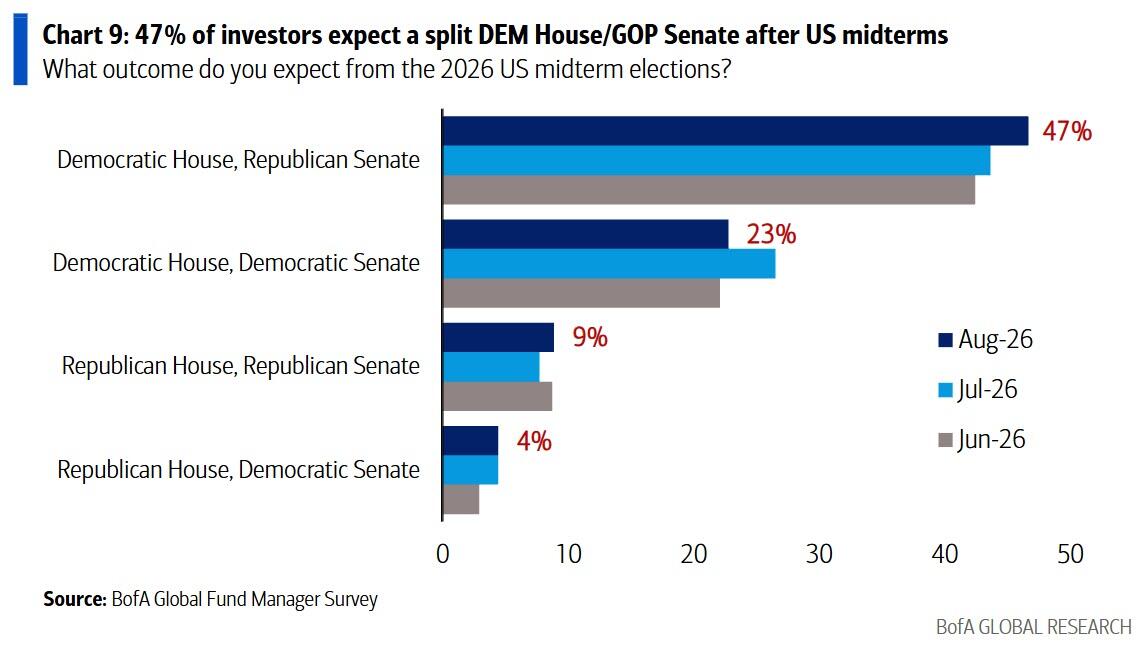
More importantly, the populists (right or left) are spending a lot to stay popular... which is why 2020s is a decade of fiscal excess, nominal GDP boom (past six years up 63% in US from $20tn to $32tn) and “Anything But Bonds” strategic asset allocations (TSYs up 74% in past six years, from $23TN to $40TN). Meanwhile, as the latest BofA Fund Managers Survey shows, investors are not fearful of midterms saying POTUS governs through Executive Orders not Congress (277 thus far, on track for most since Truman), and say a Democrat sweep is unlikely given tough Senate “map”; when asked about the most likely outcome from midterms in August BofA Fund Manager Survey (see report), 47% said GOP Senate & DEM House, 23% said DEM sweep, 9% said GOP sweep/maintains control of Congress (current GOP Senate majority is 53-47, in House 218-212).

Source: BofA FMS
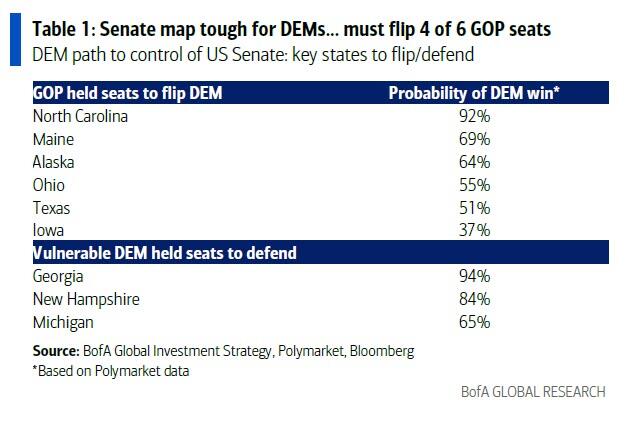
To be sure, the Senate map is tough for Dems: they must flip 4 of 6 most vulnerable GOP seats in North Carolina (current probability of DEM flip = 92%), Maine (69%), Alaska (64%), Ohio (55%), Texas (51%), Iowa (37%); and DEMs must defend vulnerable seats in Georgia (94% = current prob of DEM hold), New Hampshire (84%), Michigan (65%); the key battleground states for investors to watch are Ohio, Texas, Iowa, Michigan.

Note that Wall Street is already focused on Texas Governor race between GOP incumbent Abbott (currently polling 49% according to Real Clear Politics) and his Democrat challenger Hinojosa (45%); the clash is seen as big referendum on AI data center expansion (Abbott was recently forced to announce a data center moratorium to arrest decline in polling numbers).

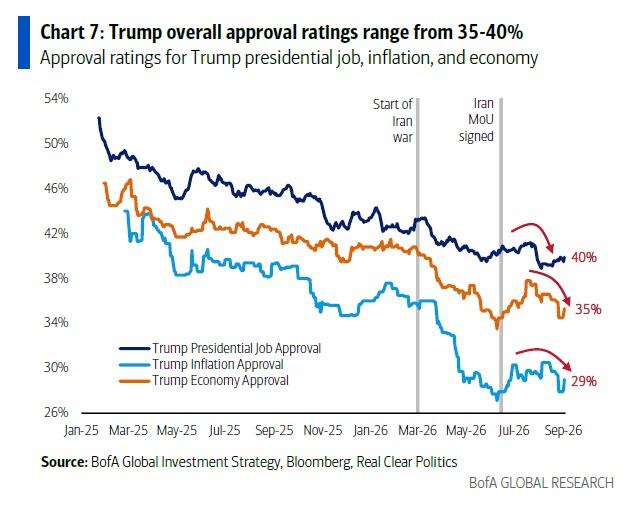
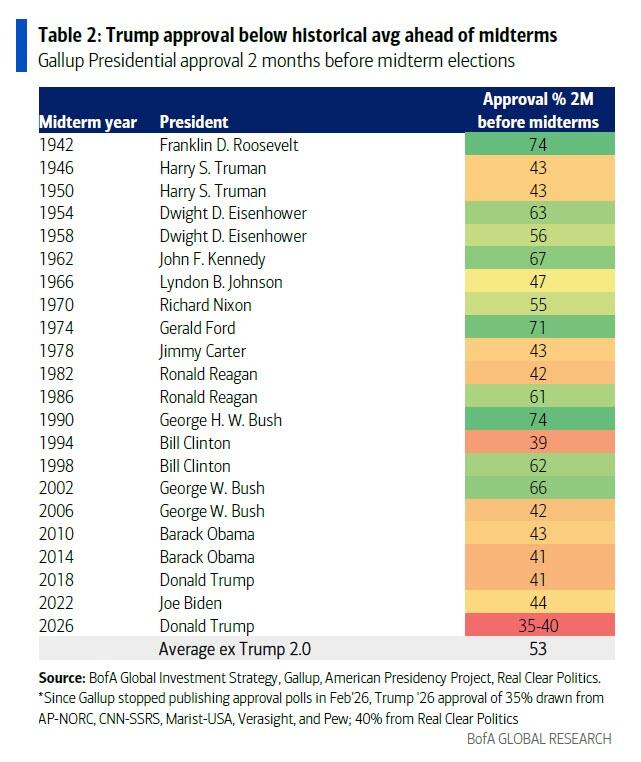
But as Hartnett's next chart shows, the Democratic sweep likelihood is rising, with Trump's Presidential approval number ranges from 35-40%, significantly below historical average 2 months ahead of midterms (53% as shown below).

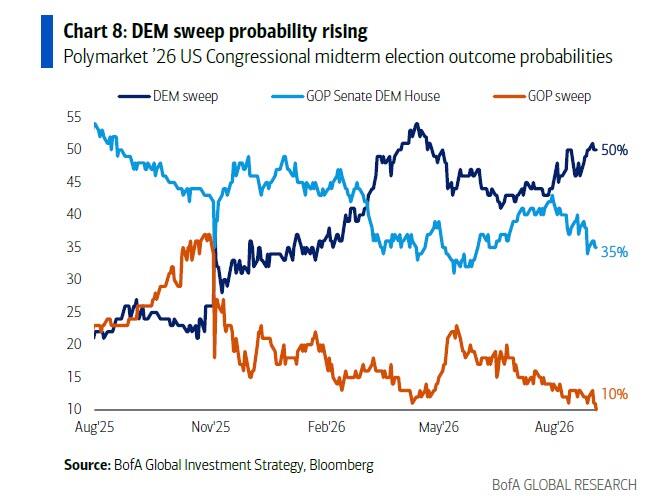
Furthermore, the BofA strategist points to the latest Polymarket probabilities, which show odds of a Democratic sweep at 50% (vs., GOP Senate/DEM House at 35%, and a GOP sweep at just 10%).

This matters because for Hartnett, a Democrat sweep is a threat to asset prices: an electoral shift from populist capitalism to populist socialism, means the next big direction in tax & regulation is up not down (and EPS negative), and would be accompanied by policies to lower inflation, healthcare, improve affordability challenge K-shape wealth boom, AI capex boom, stocks "too big to fail" Wall Street zeitgeist.

Additionally, loss of political capital = less ability for Trump to coerce resources, corporations, foreign governments into support for policy priorities of AI war with China, resource monopolization.

Putting all this together, Hartnett says a Democrat sweep = big risk-off: it would lead to a slump in i) stocks (more than 10%), ii) the dollar, and iii) bond yields into year-end, while international stocks outperform on less trade & military wars... but Europe outperforms Asia (loses Trump AI friend); the BofA strategist says the best hedge for a Democrat sweep is short financials & US dollar. In contrast, a surprise GOP sweep (maintain House/Senate) control = big risk-on, and more importantly a green light for AI bubble and positive US dollar (“exceptionalism returns").

Finally, the largely priced-in scenario of a “GOP Senate/ DEM House” translates into more of the same: modest risk-on... “gridlock = goldilocks”.

More in the full BofA Flow Show note available to pro subs.

Tyler Durden Mon, 09/07/2026 - 08:30

New York Rediscovers Nuclear Power, With Plenty Of Political Fine Print

New York Rediscovers Nuclear Power, With Plenty Of Political Fine Print

Five years after Indian Point’s last reactor shut down, Albany rediscovered the appeal of electricity that runs around the clock without burning fossil fuels.

Governor Kathy Hochul wants 5 gigawatts of new nuclear capacity, with at least 1 GW developed by the publicly owned New York Power Authority, plus a separate 4 GW initiative. 

There haven't been any announcements for the technology of choice, but the most likely candidates are the large Westinghouse AP1000 and the smaller 300 MW BWRX-300 from GE Vernova Hitachi.

As Canary Media reports, the reversal follows this spring’s weakening of New York’s climate law. The state’s difficulties with delivering large renewable projects also hasn’t helped keep them on the pure-play renewables path, which was made worse with the Trump administration’s assault on offshore wind.

The construction of new nuclear power generation offers a governor facing re-election a unique win-win opportunity: nuclear offers dependable low-carbon generation alongside renewables while also offering industrial investment, construction jobs and promises of lower bills.

Eight upstate communities have expressed interest in hosting projects. With strongly Republican-leaning counties on the list of possibilities, including Jefferson, Oswego, and Schuyler, Gov. Hochul could use the new mega-projects to score political points.

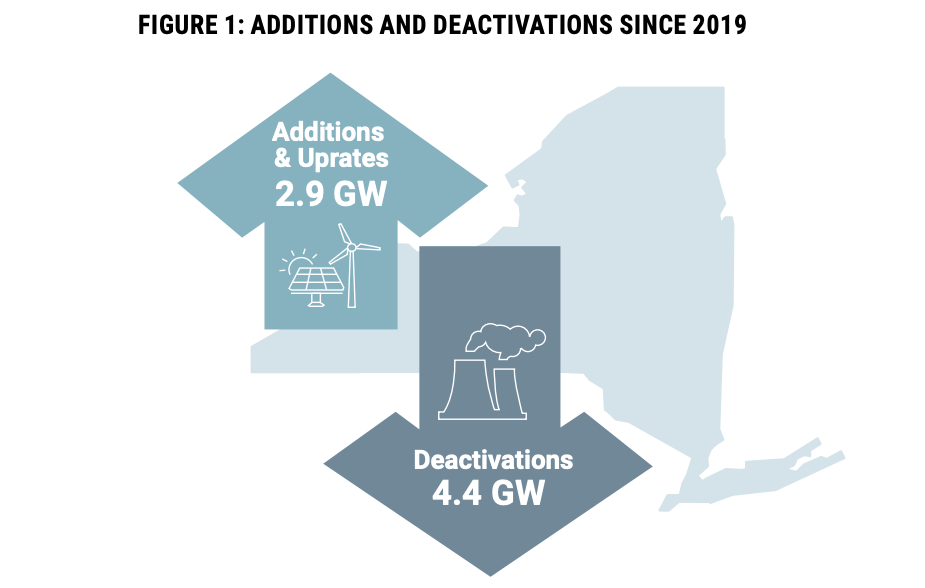
NYISO’s 2026 Power Trends warns in their recent report that trying to replace over 4 GW of something that's almost always on (nuclear) with less than 3 GW of something that's almost always off (renewables) isn't exactly how you set the state up for future success.

The report from NYISO does highlight a common problem between nuclear and other sources of generation, which is the issue of actually getting the power where it needs to go. If most of the energy demand is downstate, then additional dependencies and bottlenecks come into play. Transmission capacity becomes a problem to get the power from upstate.

Then there is Indian Point. As we previously reported, Energy Secretary Chris Wright has pushed to revive the roughly 2 GW facility, whose retirement increased reliance on fossil generation. Hochul opposes reopening it while championing new construction upstate.

A restart would require substantial work, however, a precedent is already being set with other restarts around the country, most notably at the Palisades. If there is true concern in the state for meeting baseload needs, then outright rejecting the restart of a nuclear facility becomes confusing.

Opponents are arguing nuclear spending could crowd out faster alternatives, so Senator Kevin Parker’s pending legislation would impose a 30-month pause on taxpayer and ratepayer support for new or restarted nuclear facilities while a task force studies costs and alternatives.

As we have highlighted a few times now, selective nuclear enthusiasm extends well beyond Albany.

Texas committed $350 million to advanced nuclear development in 2025. Yet Greg Abbott fought the proposed Andrews County spent-fuel storage facility, and Texas enacted restrictions in 2021 on offsite high-level waste storage.

New Mexico similarly committed almost $5 million in development assistance and workforce support for Kairos Power’s Albuquerque expansion. Meanwhile, state officials battled Holtec’s proposed HI-STORE spent-fuel facility. Holtec abandoned the New Mexico project in 2025.

The common thread is an appetite for nuclear generation capacity accompanied by arguments over who carries the liabilities. New York’s pivot could strengthen its grid for decades, potentially even the next century, if it can follow through with its swing.

Tyler Durden Mon, 09/07/2026 - 08:30

The 10-Year Treasury Yield Over 5%? Some Thoughts

The 10-Year Treasury Yield Over 5%? Some Thoughts

Authored by Wolf Richter via WolfStreet.com,

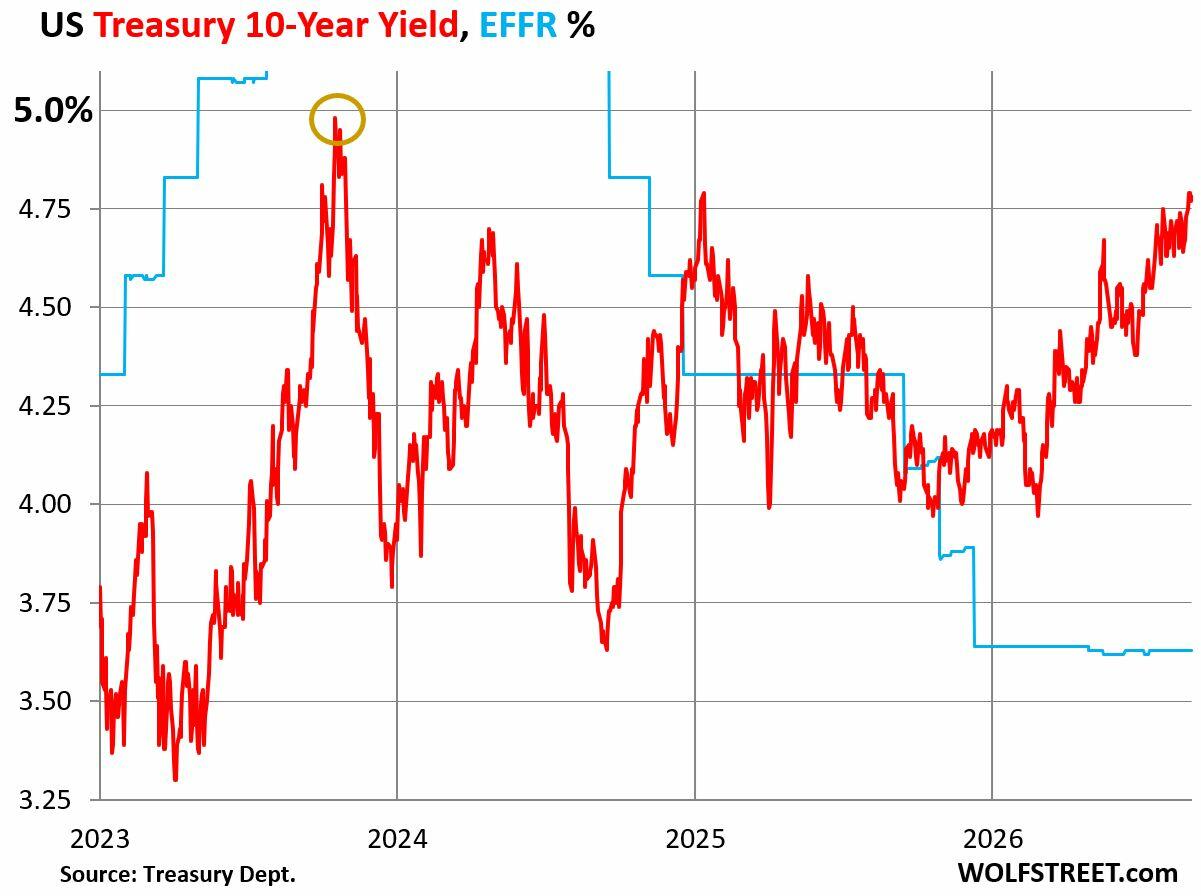
The 10-year Treasury yield has been zigzagging higher since mid-November when the Fed cut its policy rates again despite accelerating inflation. Since that rate cut, followed up by another rate cut in December, the 10-year yield has risen by 80 basis points, heading, apparently inexorably, for the 5%-line.

On Friday, it closed at 4.78%, within spitting distance of 5%, despite Bessent's three hocus-pocus shows to try to bring it down. Sure, they might have helped keeping a lid on long-term yields, as Bessent pointed out; who knows where the 10-year yield would be by now without the hocus-pocus shows. Maybe already over 5%?

The 10-year yield is now 115 basis points above the Effective Federal Funds Rate (EFFR, blue line), which the Fed targets with its policy rates. Note the November rate cut - the drop in the blue line - despite accelerating inflation. That's when the zigzag higher began.

Buyers and sellers in the bond market have good reasons for pushing up the 10-year yield: Inflation refuses to go back into the bottle. The Fed refuses to force inflation back into the bottle, triggering loose financial conditions in most areas of the economy, except in real estate. And the government refuses to even entertain a modicum of spending cuts and tax hikes to contain the deficits. It's been the opposite: tax cuts and spending hikes, and they're still talking in those terms.

The government's unwillingness to contain the deficit causes a flood of supply of new debt needed to fund the deficits. The bond market has to absorb that new debt by luring in new buyers with higher yields - investors that are now sitting on the sidelines watching this play out. If yields move high enough, these investors will begin to nibble, and if yields move higher still, these investors will nibble some more, and if yields move a lot higher still, investors might take big bites. Some of those investors have been nibbling, but the supply keeps coming, and so the 10-year yield keeps rising.

Those reasons for pushing the 10-year yield higher aren't going away anytime soon as neither the Fed nor the government is willing to do what it takes.

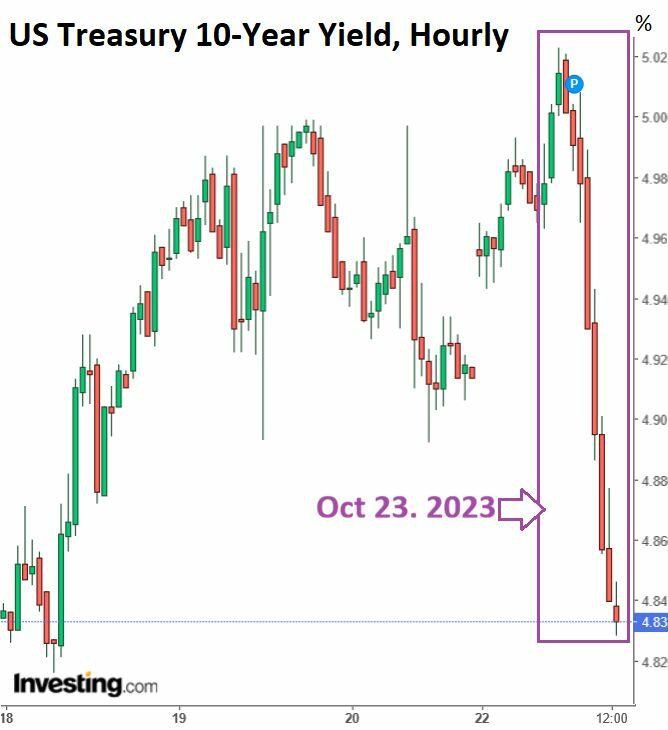
The 10-year yield had already breached the 5%-line for a few moments intraday on October 23, 2023, but that was too fast too soon, after a massive surge of 170 basis points in six months. And at 5%, the nibblers started taking out huge bites, and the sellers stopped selling, with the spectacular effect that the yield plunged by 19 basis points intraday, from 5.02% to 4.83%.

That day is circled in the chart above, showing only the closing yields. The yield then continued to plunge for the next two months, and that's how that run for 5% ended.

Here is the hourly spectacle on October 23, 2023:

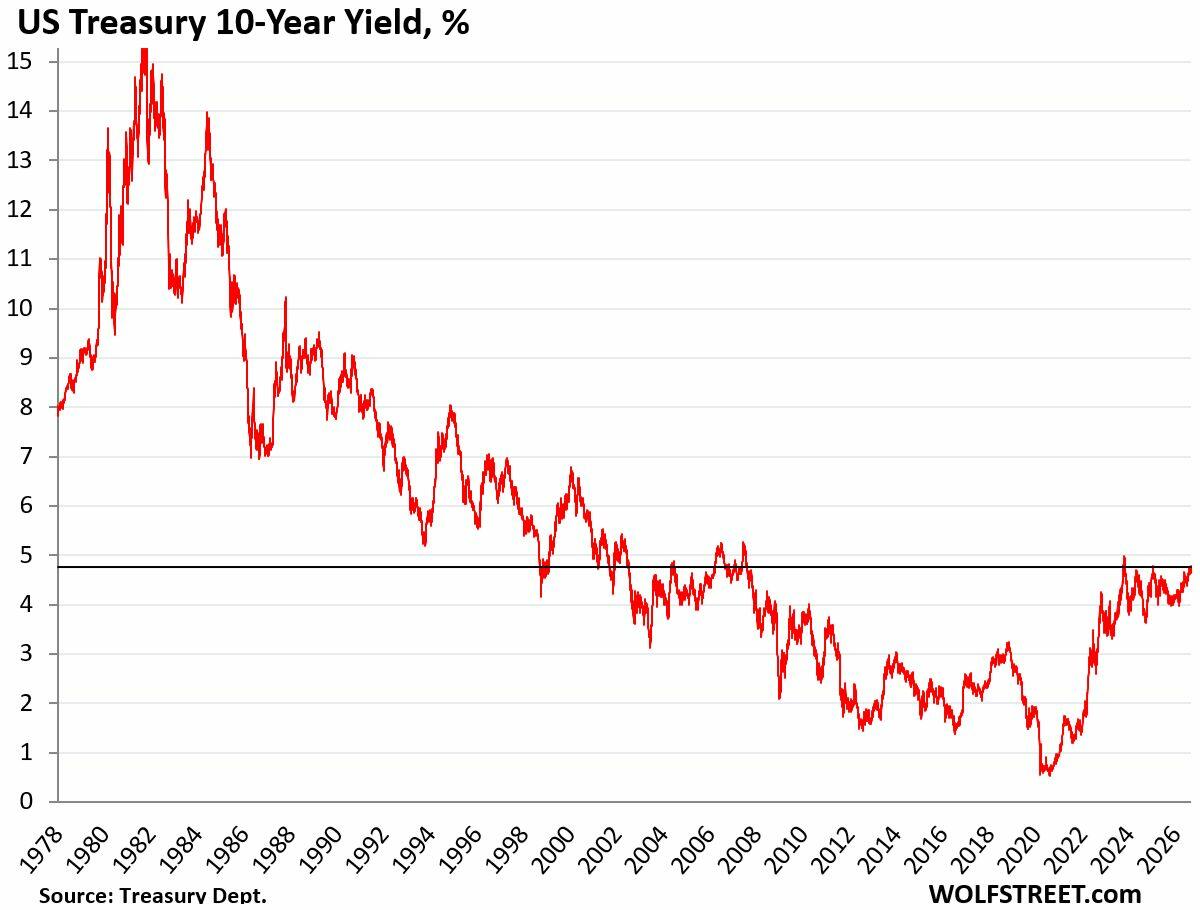
A 10-year Treasury yield above 5% and well-above 5%, was essentially the norm in the decades before 2008, before QE. Between the mid-1960s and the Dotcom Bust recession, the 10-year yield was nearly always higher than 5%, going as high as 15%. So 5% isn't anything unusual or unheard of. For several decades, it used to be considered low.

The exception occurred during the Dotcom Bust that was hitting the economy, to which the Fed responded by cutting its policy rates as low as 1%, and kept them there too long, causing Housing Bubble 1 to bloom, which ended in the Housing Bust, which triggered the mortgage crisis, which triggered the Financial Crisis. During that time, starting in June 2002 through April 2006, the 10-year yield dropped below 5%, and stayed mostly below 5%, and for part of the time even below 4%. Then it went back over 5% again, when the Housing Bust and the Fed's reaction to the budding Financial Crisis pushed the yield back below 5%. But it didn't drop below 4% until the Fed started QE in 2008.

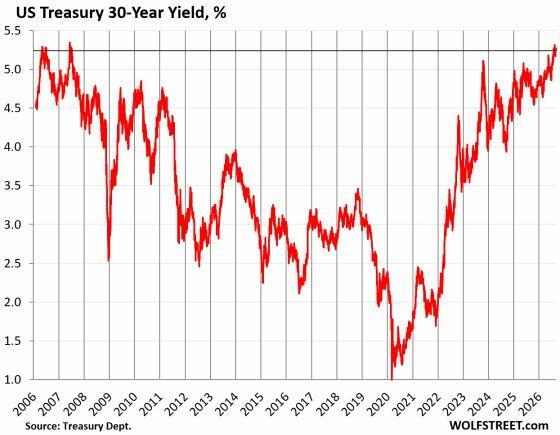
The 30-year Treasury yield hasn't been so constrained by an imaginary line that formed some kind of ceiling, where the masses come out and buy. It has zigzagged past its October 23, 2023 high, to a two-decade high. On Friday, it closed at 5.24%.

The 10-year Treasury yield looks like it wants to break out - it looks like it already made the first step to breaking out, by leaving behind its two-month range from 4.62% to 4.72%. At some point, sooner or later, given the history of the 10-year yield, the buyers and sellers in the bond market will make another run at 5%.

The big question that arises is this: Will the same thing that happened on October 23, 2023, happen all over again, when huge demand suddenly comes off the fence at that long-awaited 5%, while sellers, shocked and appalled, pull back, thereby causing the yield to plunge again?

Or will the 10-year yield blow through the 5% - with fretting sellers burning through the worried and careful buyers - and head higher, and remain above 5%?

The government's fiscal policies are asking for it. The Fed's policies of being soft on inflation are asking for it. The $40 trillion in Treasury debt outstanding is asking for it.

A 10-year yield of 5%+ is obviously not the end of the world. The US economy has done fine with a 5%+ yield, including during the Dotcom Bubble, which generated a very tight labor market, big pay increases, and lots of economic growth despite a 10-year yield mostly in the range between 5-8%.

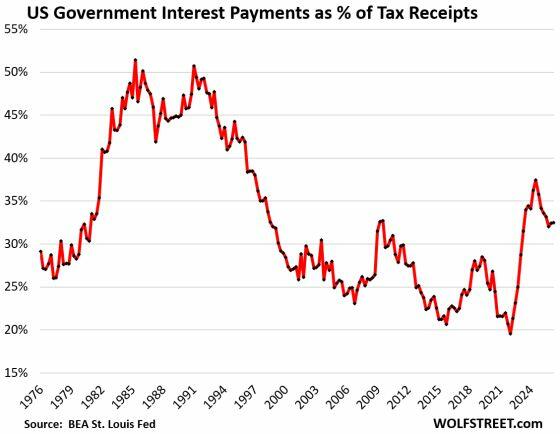
And the ratio of interest payments to tax receipts that are available to pay for them was much higher from the mid-1980s through the mid-1990s (see my analysis: Quarterly Update on the Ugly Fiscal Condition of the US in Q2 2026).

Tyler Durden Mon, 09/07/2026 - 08:10

AfD's Historic Win Shocks German Political Establishment: Here's What Happens Next

AfD's Historic Win Shocks German Political Establishment: Here's What Happens Next

The pro-Germany, anti-globalist, anti-mass migration right-wing populist party known as Alternative für Deutschland delivered its strongest election result ever in Saxony-Anhalt on Sunday, dealing a sharp blow to Germany's political establishment. 

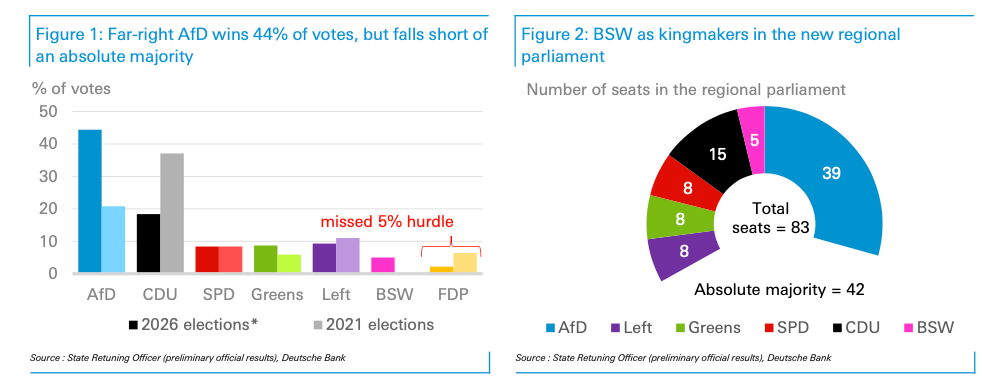
On Sunday, AfD secured 43.8% of the vote in Sunday's regional election, exceeding polling estimates. Chancellor Friedrich Merz's Christian Democrats lost about 19 percentage points, while turnout surged to 77.8% from 60.3% in 2021.

According to Marion Mühlberger, a senior economist at Deutsche Bank, AfD's weekend win leaves the party holding 39 seats in the 83-member legislature, three short of an absolute majority. The CDU, Social Democrats, Greens and Left also have a combined 39 seats. 

Mühlberger said there are two possible outcomes of what comes next: an AfD minority government tolerated by BSW, or a political stalemate that leads to a snap election, which would only give AfD a new opportunity to secure outright control.

 Mühlbergere explained:

At the time of writing, the two most likely options are i) an AfD minority government (supported by the BSW) or ii) a stalemate resulting in snap elections, with the AfD hoping to reach an absolute majority rather than attempting a minority government. AfD leadership for now appears undecided on their preference: while national co-leader Chrupalla last night indicated a willingness to try a minority government, AfD's lead candidate in Saxony-Anhalt, Ulrich Siegmund, already suggested a snap election as his preferred option, saying that "the AfD is not prepared to make far- reaching compromise to form a coalition."

We believe that even an AfD (minority) government supported by the BSW would have materially detrimental ramifications for the economic prospects of Saxony-Anhalt over the coming years. Direct investment in the state would likely decline amid significant policy uncertainty, and skilled worker shortages would likely become even more pronounced. However, Saxony-Anhalt contributes less than 2% of German GDP, and any structural damage done to the regional economy is unlikely to spill over to the rest of the German economy. While an AfD state government might test some of Germany's federal institutions, it will have no leverage over national economic or fiscal policy, not even via the constitutional court.

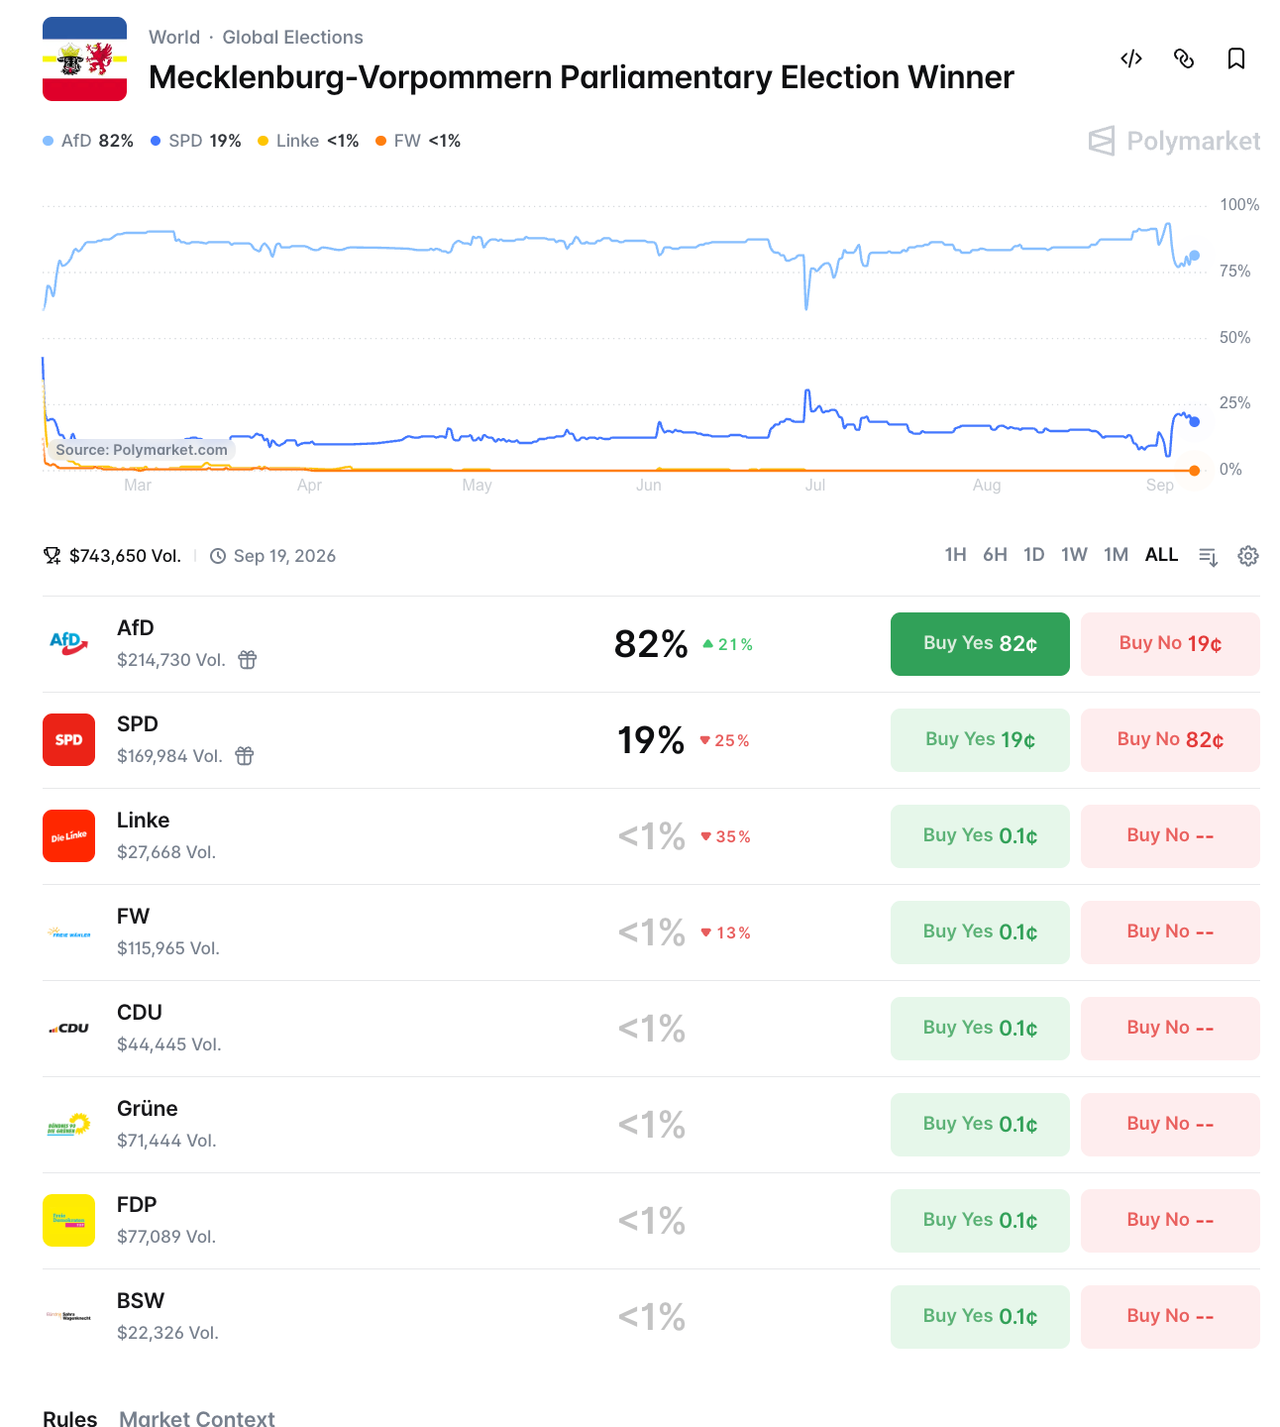
Over the course of today, we will see leaders of the coalition parties in Berlin officially react to their parties' weak electoral performance. Chancellor Merz is expected to give a press statement today at 13.30 CET. There will likely be considerable political noise over the couple of weeks ahead of the state elections on 20 September in Berlin and Mecklenburg-Vorpommern. There may be some criticism of party leadership and reform proposals. However, once these final state elections of the year are over, we believe that an AfD government in Saxony-Anhalt is likely to provide an additional impetus for the federal government coalition to double down on reforms

Mühlbergere said the five seats held by the populist BSW will be decisive: 

Thus, the populist BSW, with its 5 seats, has a key role to play in the upcoming coalition negotiations as potential kingmakers. While the AfD missed their 45+% / absolute majority election target, they missed it so narrowly that it seems difficult for them to not aim for governing Saxony-Anhalt

The BSW is the potential kingmaker

As no single party reached an absolute majority needed to govern alone, coalition negotiations for entering a formal coalition or receiving ad hoc support for a minority government will kick off today. 

The BSW has theoretically three options once the new parliament has convened and the next state premier is to be elected. First, they could elect the AfD lead candidate as state premier (without entering a formal coalition), second they could elect the CDU lead candidate or third they could abstain in the first two ballots for state premier. 

Judging from statements of BSW co-leaders (at the federal level) Wagenknecht and Ali yesterday night,1 we deem the first option the most likely.

What comes next? There are two options:

Option 1 - BSW abstains in third round facilitating an AfD minority government 

This morning, BSW leader Wagenknecht called for a "political reset" in Saxony- Anhalt, especially when it comes to energy policy, sanctions against Russia (which however are set at the EU level), education, and public broadcasting. Thus, there is a certain overlap of political priorities with the AfD. However, the BSW does not want to enter a formal coalition with the AfD. 

With the AfD rejecting the BSW's proposal for an independent state premier, an AfD minority government tolerated by the BSW seems to be a possible outcome. This means that the BSW would not enter a formal coalition with the AfD, but elect the AfD lead candidate as state premier in an informal cooperation.

Option 2 - The route to snap elections 

The newly elected parliament must convene for the first time by 6 October at the latest. But the regional constitution does not set a deadline for electing a state premier. Until a new government is elected, Sven Schulze will remain in office leading the caretaker government. 

As government formation could turn out to be complex, snap elections may be a possible way out. The AfD's lead candidate Siegmund already suggested this as a potential option, saying that the AfD is not prepared to make far-reaching compromise to form a coalition.

There are three routes to snap elections:

  1. If the newly elected parliament does not elect a state premier with an absolute majority after two ballots, it can decide with an absolute majority to dissolve itself before a third ballot. 
  2. Six months after the election, the new parliament can decide with a two- thirds majority to dissolve itself. 
  3. A newly elected state premier could call a vote of confidence. This could be a viable option for an AfD minority government, confident of winning an absolute majority in snap elections.

It is highly uncertain that snap elections would generate clear majorities. What could help the AfD is the narrative that the other parties want to keep them out of power, and that they now need a clear mandate. Moreover, smaller parties would again be at risk of not making the 5% hurdle, which would help the AfD. On the other hand, the strong AfD performance could again mobilise the centrist forces to avoid the AfD winning an absolute majority.

Mühlberger's assessment was that an AfD majority in Saxony-Anhalt could weaken investment and aggravate skilled-worker shortages. She cited policy uncertainty, the party's anti-mass migration agenda, and potential conflict with the civil service.

For Merz, the most consequential challenge is containing AfD's momentum in the upcoming elections in Berlin and Mecklenburg-Vorpommern on Sept. 20.

Polymarket's "Mecklenburg-Vorpommern Parliamentary Election Winner" market puts AfD's odds of winning at 82%.

AfD's odds of winning the Berlin election are much lower, at around 18%.

While Deutsche Bank was considerably less favorable toward AfD, Nomura analyst Andrzej Szczepaniak's recent report said that markets are less concerned about right-wing populism and more concerned about "populist left-wing parties being elected due to their desire to increase spending."

Tyler Durden Mon, 09/07/2026 - 07:45

Oh Look, Yet Another Church Up In Flames...

Oh Look, Yet Another Church Up In Flames...

Authored by Steve Watson via Modernity News,

Another week, another historic church reduced to smoke, rubble. The former Saint Agnes Church on Martha Avenue in Toledo, Ohio went up early Saturday morning. The 116-year-old landmark's steeple came down. The roof burned out. Nearby homes were evacuated. Once again the cause is listed as currently unknown.

Toledo Fire & Rescue was called around 6:30 a.m. Saturday after reports of heavy black smoke pouring from the roof of the vacant church in the Five Points neighborhood. Crews arrived to find the building already heavily engulfed.

Officials warned of collapse risk and alerted people in surrounding homes. The steeple later fell. By Saturday afternoon excavators were tearing the ruined structure down.

Saint Agnes opened in 1910. It was among 29 parishes closed or merged by the Roman Catholic Diocese of Toledo in 2005. The parochial school shut the same year. The diocese no longer owns the property. A charter school now occupies the old school building next door and reported only minor smoke, water, and a cracked window.

One neighbor told local television: "About 6:45 we heard fire trucks and I peeked out my window and it literally looked like the whole street was on fire."

Investigators in Toledo have not named a suspect, a motive, or even a cause. Vacant churches do burn by accident. They also burn because someone wants them gone. The public is asked, week after week, to accept "unknown" as the last word while the buildings keep falling.

In the U.S. hostility against churches has jumped to hundreds of incidents a year - vandalism, arson or fires of uncertain origin, gun incidents, bomb threats.

Churches are not supposed to be disposable scenery. They are the markers of the civilisation that built the towns around them. When those markers keep mysteriously burning to the ground what does that say about our civilisation?

This is now happening every week all over the world.

Historic London Church BURNS To The Ground Amid SILENCE From Government

ANOTHER Historic UK Church TORCHED; Cause “Unknown”

Another Day Another Church BURNED To The Ground

Another TWO Historic Churches Explode Into Flames…

Historic Buffalo Church TORCHED TWICE In Four Days Following Sale To ISLAMIC Group

NYC Historic Church TORCHED in Confirmed Arson — City REJECTS Save Plan As Demolition Ordered

NYC Church BURNS; Cause “Unknown”

Yet Another HISTORIC CHURCH TORCHED In Canada

Yet MORE Churches Torched; Sustained Attack On Christianity Gathers Pace

Your support is crucial in helping us defeat mass censorship. Please consider donating via Locals or check out our unique merch. Follow us on X @ModernityNews.

Tyler Durden Mon, 09/07/2026 - 07:20

Pages