Individual Economists

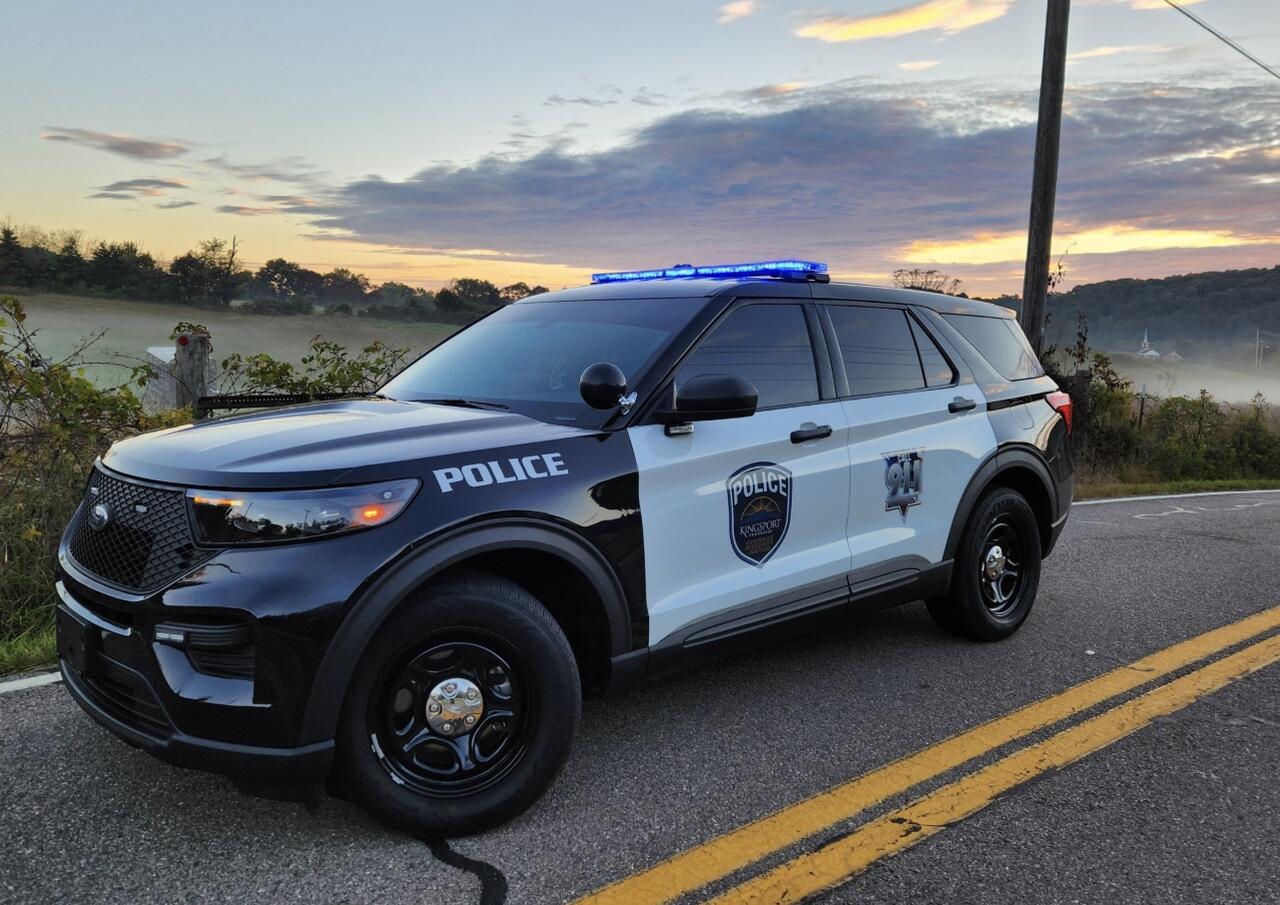
Tennessee Man Who Recorded Police Sues After Eight Armed Officers Raided His Home

Zero Hedge -

Tennessee Man Who Recorded Police Sues After Eight Armed Officers Raided His Home

A Tennessee man has taken legal action against the Kingsport Police Department after a yearslong criminal case that began with him recording an officer on the road and ended with an appellate court throwing out his conviction, according to Fox News.

Joshua Gibbons says police targeted him because he publicly called attention to an officer’s behavior. His lawsuit, brought with the Foundation for Individual Rights and Expression, or FIRE, names the city of Kingsport, its police chief and individual officers and alleges that the department retaliated against speech protected by the First Amendment.

The confrontation began in October 2022, when Gibbons saw a Kingsport police SUV traveling quickly at night without its emergency lights activated. He recorded the vehicle, eventually catching up with the officer at a fast food restaurant and questioning him about his driving. Nothing came of the encounter at the time, and the officer simply continued on his way.

The situation escalated after Gibbons put the footage online. Gibbons frequently records police activity and publishes the videos, and FIRE contends the department began scrutinizing his YouTube account after another person complained about separate footage in which an officer appeared to give Gibbons the middle finger.

According to the lawsuit, police soon turned their attention to the earlier driving video. Authorities secured a warrant accusing Gibbons of disorderly conduct as well as traffic violations related to his own driving while recording. FIRE says the warrant was obtained through a court clerk rather than presented to a judge.

The response that followed was far more aggressive. Before sunrise the next morning, eight armed officers showed up at Gibbons’ home and took him into custody in front of his daughter and elderly mother. The arrest occurred nine days after his original encounter with the officer.

Gibbons says the raid had a lasting impact on his family and believes its purpose was to frighten him into silence. He has said he intends to continue pursuing the case because his family no longer feels secure in its own home.

Fox News writes that the resulting prosecution stretched across nearly four years. Gibbons was cleared of the traffic-related accusations during his first trial but convicted of disorderly conduct. After challenging that decision, he was again convicted by a jury in circuit court.

Tennessee’s Court of Criminal Appeals eventually reversed the result. In a unanimous June decision, the appellate court concluded that the evidence did not establish disorderly conduct and dismissed the remaining charge altogether.

The judges found that Gibbons had neither threatened anyone nor behaved violently and that his comments did not stop anyone from carrying out a lawful activity. The ruling also underscored that offensive or insulting language directed toward police does not, by itself, amount to criminal conduct.

FIRE argues that the timing is central to the civil case. Attorney Adam Steinbaugh said the officer who initially encountered Gibbons did not treat his criticism as criminal behavior. It was only after Gibbons published the encounter and drew attention to the department, FIRE contends, that police decided to pursue him.

Gibbons is now seeking to hold the city and department officials accountable for what he alleges was retaliation against constitutionally protected activity. Beyond his own case, he says he wants the lawsuit to force changes in how Kingsport police respond to citizens who record or criticize officers.

Tyler Durden Thu, 10/01/2026 - 16:40

Remembering The False Gloom And Doom Of The 1992 Elections... And The Upcoming Midterms

Zero Hedge -

Remembering The False Gloom And Doom Of The 1992 Elections... And The Upcoming Midterms

Authored by Victor Davis Hanson via American Greatness,

Republicans risk repeating 1992 by failing to counter economic pessimism with the facts about strong growth, falling inflation, rising incomes, and a recovering economy.

In 1992, Bill Clinton won the presidential election partly on the basis of his campaign's false accusation that George H. W. Bush had overseen "the worst economic performance since the Great Depression." Or so claimed Clinton's running mate Al Gore.

James Carville, chief campaign adviser to Clinton/Gore, amplified that message with the constant refrain: "It's the economy, stupid."

That strategy worked for three reasons.

First, third-party candidate Ross Perot siphoned off nearly 19 percent of the vote. Most of his supporters would otherwise likely have gone to Bush. Perot allowed Clinton to win with a mere 43 percent of the popular vote, in part by echoing the false narrative of a crushing Bush recession.

Second, the brilliant Bush campaign strategist Lee Atwater, who had virtually destroyed the Dukakis campaign in 1988 - remember the tank ad, the Boston Harbor ad, and the Willie Horton ad? - had died in 1991 at the age of 40 from a brain tumor.

Atwater's canny but hardball 1988 tactics had turned off establishment Republicans. So in 1992, Republicans reverted to the notion of losing nobly rather than winning ugly and resumed unilaterally playing by the Marquess of Queensberry rules. The result of Democratic demagoguery was that the sober and competent elder Bush was branded a heartless elitist who had wrecked the economy and defended Kuwait only for "blood for oil." And without Atwater, the Bush team utterly failed to refute such caricatures and counterattack.

Third, and most important, the anemic Bush reelection campaign never refuted the Clinton-Gore economic hysteria. That "recession" deception had drowned out the historic foreign policy achievements of Bush's four years, from the successful policies that followed the fall of the Berlin Wall in 1989 to the decisive 1991 Gulf War.

Despite overwrought claims about a recession or even a new Great Depression, in truth, the recession had ended in March 1991. In fact, final GDP growth for 1992 was a robust 3.52 percent. That was hardly a recessionary indicator. Indeed, the election-year growth proved even stronger than in Clinton's first year of governance in 1993.

While unemployment was still high at 7.5 percent, the 1992 stock market nonetheless grew by 7.6 percent. And the 1992 inflation rate had stayed moderate at 2.9 percent.

In other words, the economy had already begun to recover from the 1990-91 recession, which - to reiterate - had officially ended 20 months before the 1992 election.

One cause - eerily now familiar - of the earlier 1990-91 downturn was that oil prices had initially doubled after the 1990 Iraqi invasion of Kuwait and the U.S. military response. But prices collapsed as soon as Operation Desert Storm began, despite the later torching of the Kuwaiti oil fields and continued uncertainty in the Gulf. Yet by the November 1992 election, oil prices had long been back to pre-invasion levels.

In short, the Democrats' charge that 1992 saw the worst recession in 60 years was absurd. (The 1973-75 and 1981-82 recessions were far worse than the 1990-91 recession.)

Fast forward to the present. The economy today is far better than in 1992. But Democrats' successful 1992 demagoguery should remind Republicans that the perception of the economy peddled by campaign rhetoric can often decide elections more than the reality does.

Take the just-released 2025 poverty rate. It hit an all-time low of 10.2 percent. Child poverty also fell to a historic low. Such amazing news refutes wild leftist charges that uncovering vast welfare fraud, deporting thousands of illegal aliens, and cutting 400,000 federal jobs would spike poverty. In fact, those actions more likely contributed to reducing poverty, as did an astounding lowest violent crime rate in some 70 years.

Median household income also hit a record high of $87,460. That is the highest median household income in the world, dwarfing all other large industrial nations that are not petro-states or tax havens. The same holds true for our GDP per capita - which, incidentally, was already over $34,000 higher than in Canada.

New business reports show that this past August manufacturing achieved its largest monthly increase since 2022. And service-sector growth jumped to its highest level since 2021. New orders for metals, machinery, computers, appliances, communications - in truth, almost everything - continue to rise every month, especially and most recently in August.

Despite the Iran war and its global petroleum interruptions, the Atlanta Federal Reserve now predicts that third-quarter GDP growth will finish at a blistering 5 percent. The Dow and the S&P have grown by a strong 8.1 percent and a staggering 13.5 percent, respectively, in 2026.

Take away the climb in gas prices from a January 2026 average of $2.81 a gallon to $4.50, and the inflation rate was only 2.5 percent - below the 2025 yearly average of 2.7 percent - and Wall Street estimates put the annual rate at around 2.2 percent once the Iran war ends and a huge influx of oil hits the global market. The United States is now the greatest producer of oil and the greatest producer and exporter of natural gas in history - and is still increasing output.

August unemployment was a low 4.1 percent, while 162,000 new jobs were created in that month alone. Consumer spending remains strong.

The U.S. economy is entering a boom cycle. Its growth ensures that it remains the largest in the world and continues to outpace all competitors.

Many of the dire predictions at the millennium about the supposedly superior collectivist paradigm of the European Union - or the inevitable rise of a China of 1.4 billion people - surpassing the United States simply did not come true.

The EU has about 100 million more people than the United States. China's population is four times larger than America's. Yet both have fallen further behind the United States in terms of economic production.

Indeed, the U.S. economy is roughly $10 trillion larger than either China's or the EU's. Far from some predictions of a decade ago that within 10 years China would overtake the United States, the opposite has occurred. America's nominal GDP of $18.8 trillion in 2016 soared to $32.4 trillion in 2026 - as the American share of global GDP increased to 26 percent. In contrast, the EU's share of global GDP actually shrank, and China's still stayed well behind the United States.

In key categories such as digital media, software, AI, bioengineering, and space technology, American companies remain the world's largest and most successful. They usually dominate global top-ten rankings, with eight or nine U.S. corporations among the top slots.

If the Republicans broadcast this positive news about the economy, it will in turn complement Trump's unambiguous foreign policy successes, which are largely underappreciated, if not unknown, among the public.

But they remain impressive: the rebooting of NATO by getting its members to rearm and take up their fair share of collective defense; the acquisition of new treaties ensuring an American military presence in the Greenland to monitor the contested Arctic; the radical transformation of much of the Western Hemisphere from leftist and anti-American nations into pro-American, tough-on-crime, free-market countries; the expulsion of the Chinese bad actors from the Panama Canal and the extradition of the anti-American communist Maduro from Venezuela; the restoration of Pentagon recruitment; and the change in Pentagon procurement to emphasize quantity of weaponry along with quality.

The verdict on the unpopular war against the Iranian theocracy is still out. But the idea that the last seven months of on-again, off-again strikes and negotiations amount, in terms of human and material costs, to a "forever war" is absurd and a lie.

While all our soldiers' deaths are tragic, the conduct of the war against the terrorist powerhouse of the Middle East had deliberately been waged to limit the loss of American lives. Indeed, the average daily fatality rate due to accidents in all branches of the military during the seven months of the Iran conflict is some eleven times greater than the number of those killed fighting Iran.

The roughly $40 billion cost of the war so far, while substantial, amounts to about 25% of the conservative estimates of recently discovered welfare corruption and fraud in California alone - involving theft of Medi-Cal, unemployment insurance, in-home services, and hospice funding.

The war will be judged by historians, fairly or not, on whether it delays for years or, if not, ends Iran's quest for nuclear weapons altogether, and on whether it so weakens the theocracy that it permanently loses its terrorist leverage over the Middle East - if not eventually implodes from popular resistance. If such a regime collapse should follow the conflict, the Middle East miasma of the last 70 years would largely end, marking the most profound American achievement abroad since the fall of the Berlin Wall.

So much is at stake.

Nevertheless, the Republicans have not yet developed a strategy to inform the public that the economy is sound and improving - and will likely soon take off, after the Iran conflict is over, oil becomes plentiful again, and tax cuts, foreign investment, deregulation, and productivity gains from AI take their full effect.

Most importantly, Republicans have still not articulated why the "affordability" issue persists. Under Joe Biden, average prices were nearly 21 percent higher than when he took office, with a yearly average increase of more than 5 percent.

The Trump administration nearly halved that annual rate in 2025. It will reduce Biden's yearly inflation rate substantially again in 2026.

But neither Trump nor any other president could or would wish by design to engineer radical deflation to restore prices to the pre-Biden levels of 2020 during Trump's last year in office.

Trump's first-term total four-year inflation rate was under 8 percent, averaging about 2 percent per year - far less than half the yearly inflation average of the subsequent Biden years.

In 2025, wages still climbed higher than the rate of inflation. But it would require a damaging recession to undo Biden's 20 percent rise in prices. And worse still, the cost of staples such as food, shelter, vehicles, fuel, and insurance rose nearly 30 percent over Biden's four years.

Nor have Republicans made the easy case that the midterms are no longer merely a matter of liberal versus conservative, Democrat versus Republican, or even progressives versus MAGA.

Rather, November 3 represents normality and common sense pitted against an unrecognizable "Democratic" revolutionary party that is driven by Islamist-sympathizing socialist zealots who are not fond of the United States as it has existed for 250 years. They are not shy about planning to remake America along the lines of, at best, radical European socialism and, at worst, something resembling Cuba.

Needless to say, if they get their way, even the most lurid false liberal claims about our current alleged economic problems will pale by comparison.

We publish a variety of perspectives. Nothing written here is to be construed as representing the views of ZeroHedge.

Tyler Durden Thu, 10/01/2026 - 16:20

"Showings Have Stopped": Housing Market Freezes As Mortgage Rates Soar To 7.28%, Highest In 3 Years

Zero Hedge -

"Showings Have Stopped": Housing Market Freezes As Mortgage Rates Soar To 7.28%, Highest In 3 Years

The American dream has never been more out of reach.

Mortgage rates posted their largest increase in four years this week, one of the clearest signs of how the recent bond-market selloff is spilling into the broader economy - if not memory and chip stocks which continue to trade entirely on the highly efficient circular financing and junk bond markets.

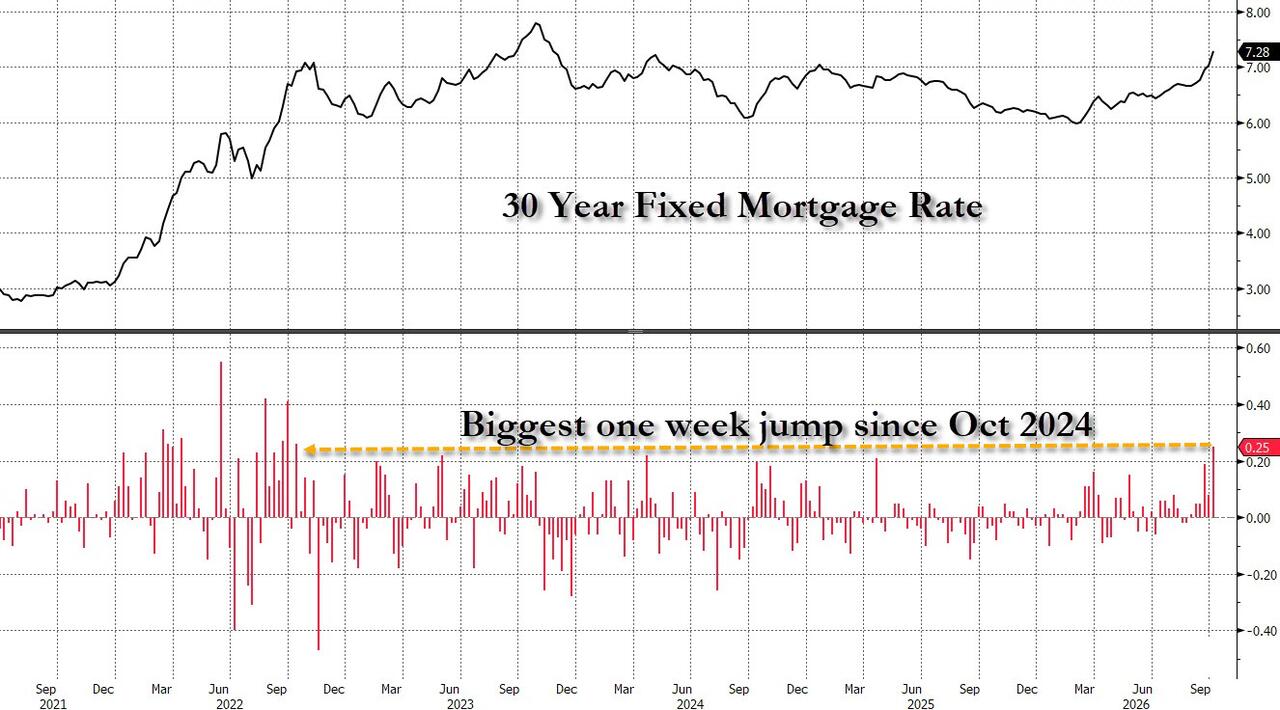
30-year fixed-rate mortgages rates surged 25bps in one week, to 7.28% from 7.03%, the biggest jump since October of 2022, according to Freddie Mac.

Mortgage rates have risen to the highest since November 2023 as inflation, a surge in government debt and heavy corporate borrowing for the build-out of AI (not to mention the latest European sovereign debt crisis) push up bond yields. The recent sharp selloff in the bond-market has risen borrowing costs for home buyers and dealt a blow after blow to a limping housing market.

“Showings have stopped basically,” said Don Wessel, a real-estate agent in Greenville, S.C, quoted by the WSJ. "I’ve got good listings in downtown Greenville, which is one of the hottest areas, and nobody’s looking at them."

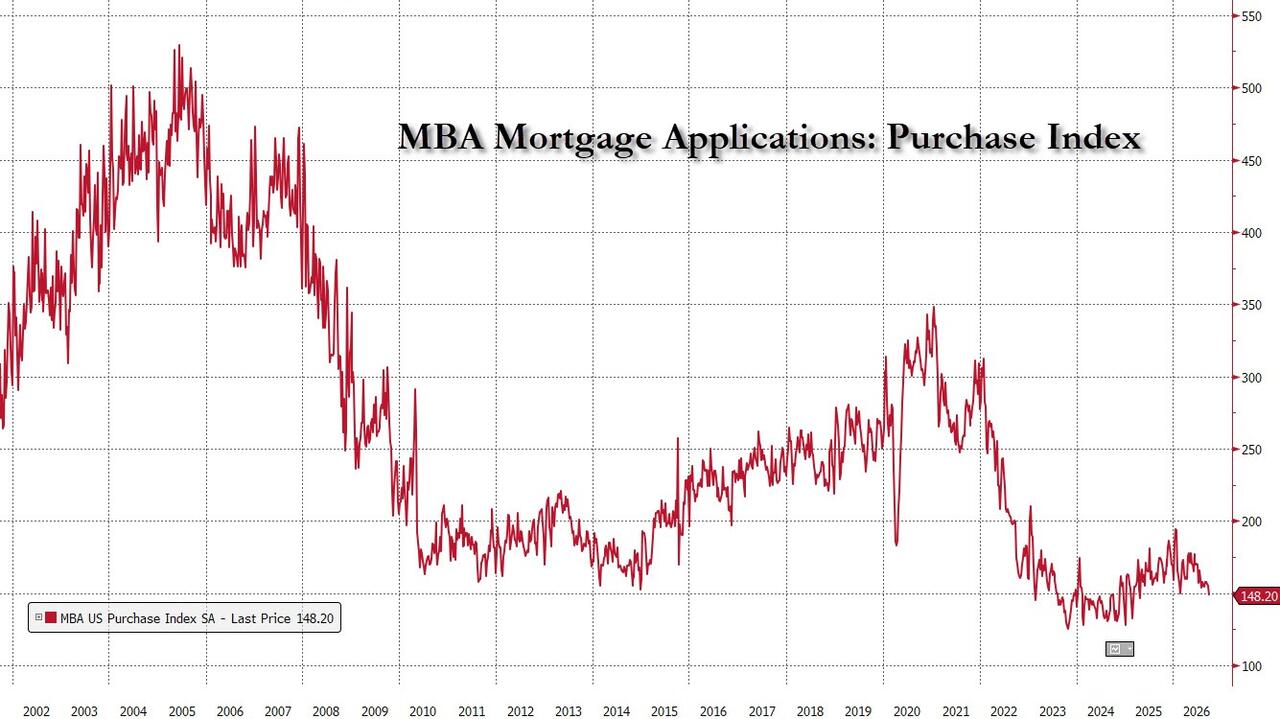
In 2022, rates surged as part of postpandemic inflation that ended years of below 5% mortgage rates and ground the housing market to a halt. Home sales still haven’t recovered from that rapid freeze four years ago. With rates now at their highest point since 2023, buyers are likely to stay planted on the sidelines, while sellers may take their homes off the market.

The market may not be completely frozen - yet - but it's getting these: for the week ending Sept. 25, mortgage applications plunged 6%, the fourth consecutive week of declines, according to the Mortgage Bankers Association. 

At the start of the year, mortgage rates touched below 6%, but the beginning of the war in Iran caused them to jump. As the conflict has drawn on, fears of sticky inflation have driven rates higher and higher. Rates began September at 6.71% before a historic bond selloff sent them surging more than 50bps higher. 

With the 10Y TSY today hitting the highest yield in 24 years, Americans have been feeling the pain of the bond selloff most directly and rapidly through the housing market, where mortgage rates closely follow 10Y Treasury yields. 

As the WSJ reports, the recent run-up in mortgage rates has brought sales activity in the housing market to a standstill, as buyers have already been coping with record home prices and stretching to afford down payments. Plus, with sky-high homeowners association fees and property taxes, the math has become impossible for first-time buyers to work out.

Now, the end of 2026, a year that was expected to launch the market’s recovery, is likely to be a slog.

“I still see it declining and you’re coming into the slow part with the holidays,” Wessel said. “I think there’s a short window now for sellers to sell and then buyers get out of the market.”

That said, buyers in the upper end of the market, many of whom transact in all cash and don't need mortgages and are generally less constrained by affordability, are continuing to show interest, said Anthony Rael, an agent in Denver. “They seem to be flush with cash, bringing 20%, 30% down payments into the mix,” he said. “Whereas the lower market, let’s just say closer to a half a million and below, is really struggling where we’re getting lots of showings and no activity, no offers.” 

Higher mortgage rates could also halt progress the market has made in freeing up inventory. For years, homeowners have been wary of selling their homes to preserve their low mortgage rates from years ago. That sent inventory plummeting, which has allowed home prices to continue hitting new records, despite weak demand.

While there were a few scattered signs that the lock-in effect was starting to ease as sellers lost patience and gave up their low rates to move for family reasons or new jobs, as inventory approached prepandemic levels in August, but now, rates well above 7% are sure to drive sellers away.

In July, Adam Wharton and his wife bought a new house in Georgia but haven’t been able to sell their old house, which they listed at the beginning of September. There initially was a flurry of interest, and they accepted an offer, before the buyer backed out.

“We were getting multiple showings a day. Within four days, we had a full-ask offer on it,” he said.

But then after rates jumped, the buyers disappeared. Their last showing was two weeks ago. “Since that, it’s been nothing, no scheduled showings, no offers, no nothing from people who have looked at it before,” he said.

The mortgage they have on the house, with a rate of 3.35% and a monthly payment under $1,000, is extremely cheap, and so Wharton isn’t in any rush to sell. Now, they are considering taking it off the market and renting it out if they don’t get any offers, waiting for the market to loosen up before listing it again.

“Everybody has in their minds these two and three and four percent mortgages,” he said, but he will have to wait until the next recession - or depression - before those come back again. 

With mortgage rates breaking through 7%, some home buyers are considering the familiar strategies for lowering their monthly payments: putting more money down, using adjustable-rate mortgages and even buying in cash.

While increasing the size of the down payment would help offset the monthly bill that comes with a higher mortgage rate, home prices are up more than 50% since 2019, and many buyers are struggling to find the cash to boost their deposits above the typical 10% to 15% down.

That has scrambled the usual buyer playbook for adjusting to higher borrowing costs. Typically, when mortgage rates rise, sellers have to cut prices to keep buyers in the market. But for years, supply has lagged behind as many homeowners have opted to stay put to preserve the 3% to 4% mortgage rates that they secured in the wake of the pandemic. 

This lock-in effect—homeowners refusing to sell and give up a low mortgage rate they locked in years ago—has allowed prices to continue rising, even as demand has sagged. The national median existing-home price in August rose 1.6% from a year earlier, to $429,100, an August record. That is despite sales falling to their lowest level and interest rates pushing to their highest point in more than a year.

Median down payments have increased a bit this year as the rise in mortgage rates has encouraged buyers to spend more money upfront to lower their monthly payments. The median down payment in January of this year was $23,053, according to Realtor.com. In August, it was up to $27,166. Over the same period, the median down-payment percentage has risen to 13.8% from 12.8%.

But Christina Beitler, who runs a mortgage brokerage firm in Austin, Texas, said the recent rise in rates has ground the market to a halt.

“We’ve all hit a wall. We’ve pretty much seen a very large stalling of activity,” she said. “I do think right now, buyers are taking a step back, taking a moment of pause.”

As the WSJ notes, even in the wake of the 2008 housing crash, when home sales sank, buyers with good credit could take advantage of lower mortgage rates than today and a fall in home prices. Supply benefited from lenders looking to unload millions of foreclosed homes. Beitler said she recently quoted someone a mortgage rate on a Monday, and by the time they went under contract on a Thursday, the rate had increased over half a percentage point. “They literally just said, ‘I can’t do this,’” she said, adding that the person terminated the contract.

As older homeowners often point out, before 2001, mortgage rates were just about always above 7%, and in the 1980s, they reached as high as 18.63%, according to Freddie Mac. As a result, housing affordability was even worse back then, but low home prices allowed buyers to put down larger-percentage down payments to help mitigate the higher rate. 

In 1980, the median home value was $47,200, while median household income was $17,710, according to the Census Bureau. Now, home values are up to $368,700, according to Zillow, outpacing income, which in 2025 was up to $87,460. That means that for many buyers, down payments have become far more of a financial burden.

Continued growth in down payments could be modest, mostly because many buyers are already putting down as much as they can and simply can’t afford to contribute any more, said First American Chief Economist Mark Fleming.

“For a lot of the affordability-constrained borrowers, they don’t have the option,” he said.

Tyler Durden Thu, 10/01/2026 - 15:46

Supertanker Ablaze After Iran Attack In Hormuz As US Deploys 10K More Troops & Third Carrier To Mideast

Zero Hedge -

Supertanker Ablaze After Iran Attack In Hormuz As US Deploys 10K More Troops & Third Carrier To Mideast

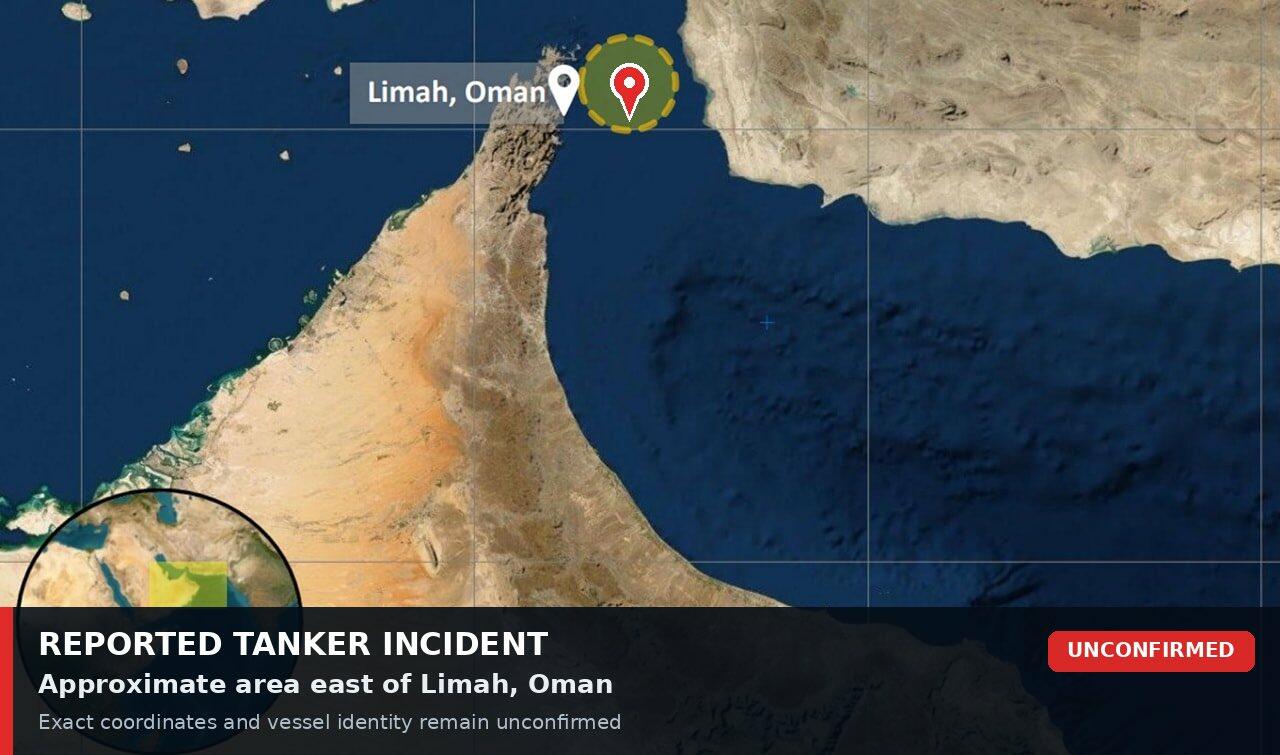
Update(1530ET): Iranians are apparently going back on the offensive, after it's been widely reported that US-protected oil transit through the Strait of Hormuz has been fast gaining steam. Iran state media says a supertanker is burning off the coast of Oman after coming under Iranian attack:

Local sources reported that a 2.5 million barrel capacity supertanker that was traveling through the Strait of Hormuz illegally was hit 8 kilometers off the coast of Oman and is burning, reports Fars

Earlier we reported that starting in mid-August (on Aug. 16), Iran’s Supreme National Security Council set October 1 as a deadline. It warned at the time that if Washington failed to lift its naval blockade of Iranian ports within 45 days, Tehran could resume attacks against US forces, and by implication step up attacks on foreign shipping.

Iran’s 45-day deadline for the United States has now expired. That deadline has now passed, potentially adding another layer of uncertainty to an already tense confrontation where Tehran may decide it must act 'preemptively' while facing more bombs by Trump (likely after the midterms).

*  *  *

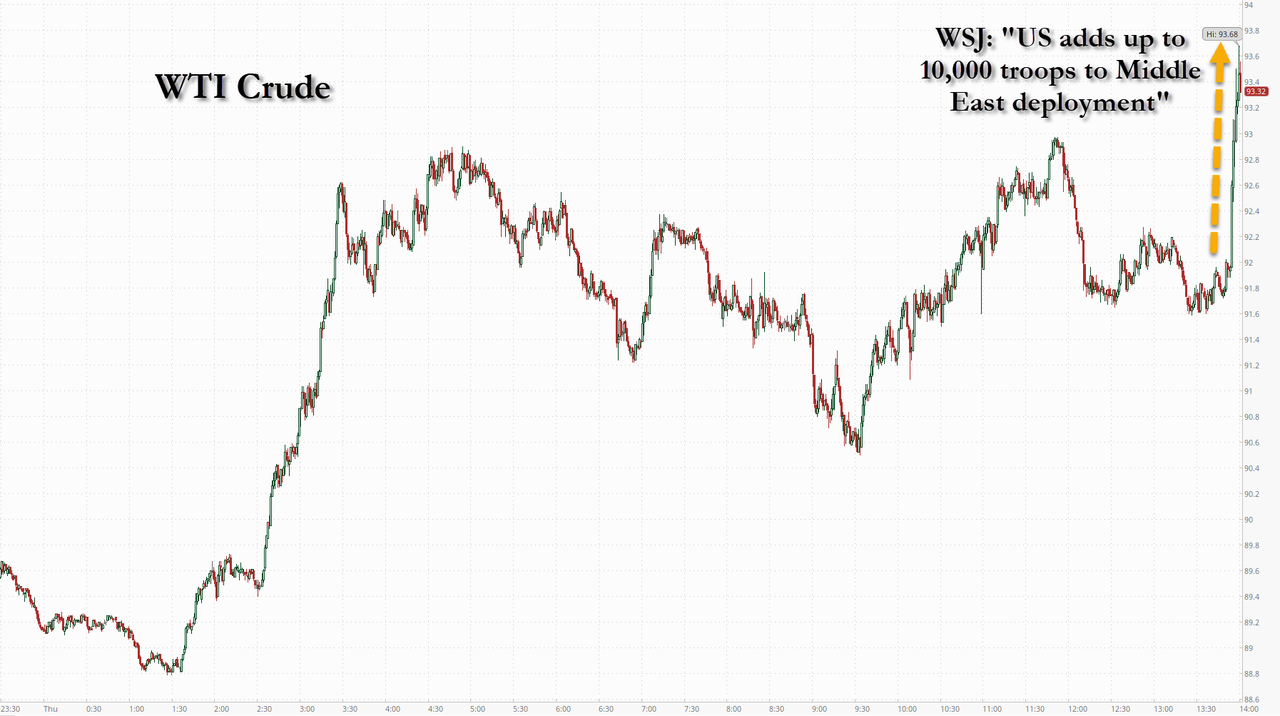
Signs of potential major escalation, or the next round at least (which Trump has hinted will come after the midterm elections), just hit The Wall Street Journal, and sent oil prices soaring. A quick summary:

  • The Pentagon is sending a third aircraft-carrier strike group and additional Marine Corps ships to the Middle East, adding 9,000 to 10,000 more troops to the region.
  • The ships, jet fighters, Marines and sailors will arrive in the region by the end of November, as President Trump considers renewing strikes on Iran after the midterm elections.
  • The additional servicemembers will add to the more than 50,000 troops already in the region, with the deployments coming after Trump rejected Iran's latest proposal for a seven-day ceasefire.

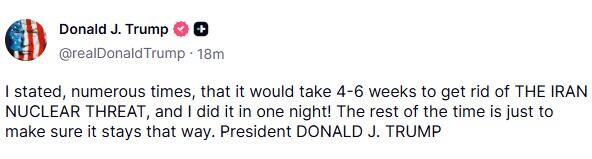
The Trump administration is deploying a third aircraft carrier to the Middle East along with additional Marines, an American official also told Israeli media on Thursday. And later, in the afternoon, Trump posted a new Truth Social message as follows:

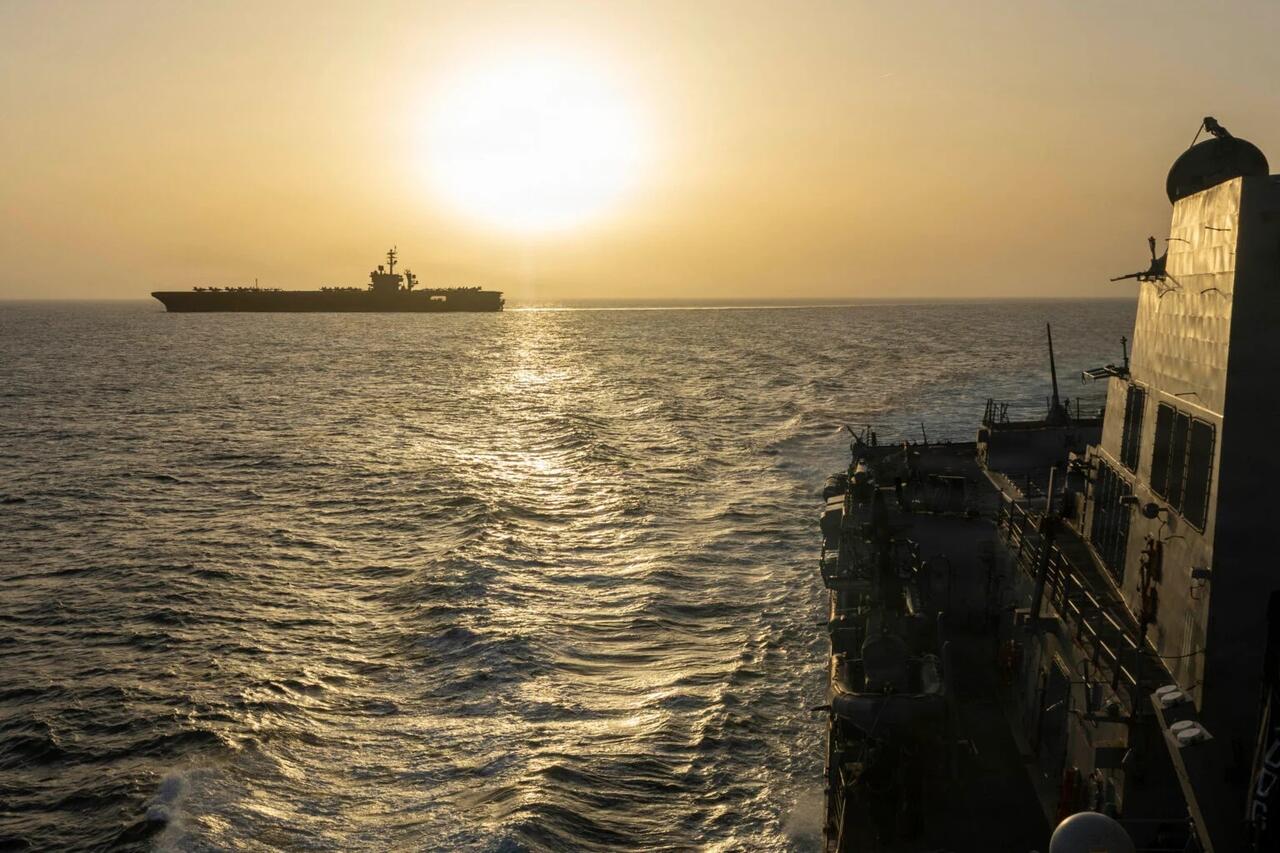
The USS Theodore Roosevelt is en route to US Central Command's (CENTCOM) area of operations after having just left San Diego this week. It is expected to relieve the Japan-based USS George Washington, which entered regional waters in mid-August.

But both carriers could also stay on extended deployments. The WSJ writes further:

The additional moves will further strain the U.S. Navy, however, which has experienced supply shortages and faced near-record deployments during the conflict. Iran has in recent weeks fired ballistic missiles at American warships. The crew of the Roosevelt is prepared for a longer-than-normal deployment as well, according to senior Navy officials.

Source: US Navy

Carriers which more frequently had Indo-Pacific deployments have been increasingly diverted to the Middle East in recent years, a trend which had only picked up steam amid tensions with Iran and the Houthis out of Yemen.

Also on Thursday Al Jazeera is newly reporting that three carriers will stay in regional waters, "By the end of November, three aircraft carriers and two landing groups will be deployed around Iran," a US official told the Qatar-based outlet.

And USNI News earlier detailed:

On September 28, USNI News reported that a U.S. defense official had confirmed the carrier’s departure from San Diego the previous day. Navy officials had also warned families that the deployment could exceed seven months, with eight months being used as the planning baseline.

Carrier Strike Group 9 includes Theodore Roosevelt, Carrier Air Wing 11, Destroyer Squadron 23, Information Warfare Squadron 9 and the Ticonderoga-class guided-missile cruiser USS Chosin (CG-65). Its embarked air wing brings together several combat and support aircraft. The strike component includes F-35C Lightning II fighters from VFA-86, F/A-18E Super Hornets from VFA-211 and VFA-25, and F/A-18F aircraft from VFA-154. VAQ-137 operates the EA-18G Growler for electronic warfare, while VAW-115 flies the E-2D Advanced Hawkeye for airborne surveillance and command and control.

Whether one of the carriers ends up leaving the theatre or not, the extra deployment does mean President Trump will have a wider range of options for more possible military actions against the Islamic Republic.

He has in a freshly published TIME interview this week reiterated that he may be escalating attacks on Iran after the November midterms if an acceptable deal can't be reached.

Tyler Durden Thu, 10/01/2026 - 15:30

Cantor: Almonty "Moving Seamlessly" Into Production As Korean Tungsten Mine Becomes Western Lifeline

Zero Hedge -

Cantor: Almonty "Moving Seamlessly" Into Production As Korean Tungsten Mine Becomes Western Lifeline

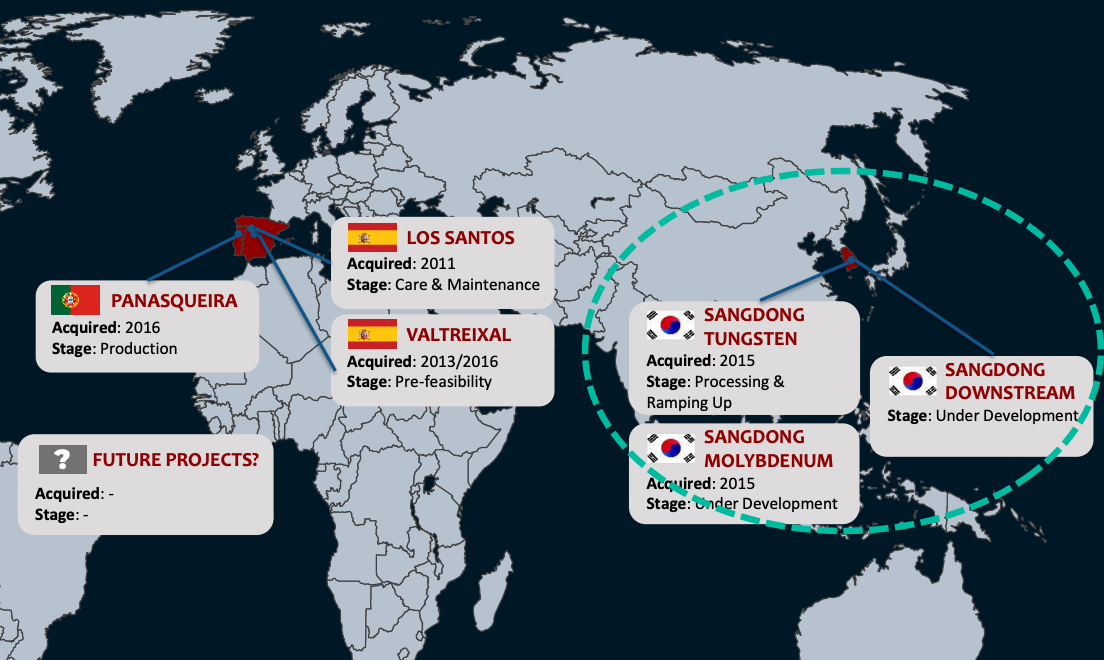
Cantor Fitzgerald metals and mining analyst Matthew O'Keefe provided clients on Tuesday with an update on Almonty Industries, citing a corporate update from CEO Lewis Black. The miner's crown jewel tungsten mine in South Korea has begun shipping concentrate as the West's answer to conflict-free tungsten supply comes online, playing into a bigger theme we've outlined called "owning the bottlenecks."

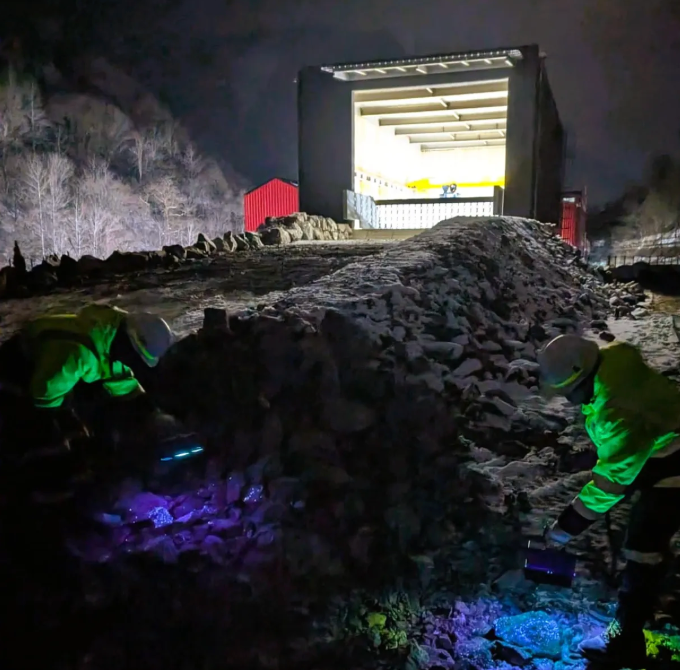
O'Keefe says the Sangdong mine has begun shipping concentrate, is moving toward 24/7 operations, and has about 4.6 months of stockpiled ore to support its ramp-up. Phase II expansion is also already underway, with completion expected in 2027.

O'Keefe outlined why Sangdong is critical to expanding Western-aligned tungsten supply and breaking China's "quasi-monopoly" grip:

A major source ex-China: Phase II would increase throughput to 1.2 million tonnes annually, potentially supporting more than 460,000 MTU of tungsten trioxide production per year at Sangdong.

The production inflection: Cantor’s detailed model forecasts consolidated output rising from 126,287 MTU in 2026 to 444,400 MTU in 2027, while all-in sustaining costs fall from $905 to $319 per MTU. These are forecasts, contingent on successful execution.

"This is a defining moment for Almonty and for Western supply chains: tungsten mined and processed in an allied nation is now a reality," CEO Black wrote in a statement. 

CEO Black added more color on the ramp-up of the South Korean mine:

Sangdong Phase II: The Next Chapter Is Already Underground

The stockpile on the surface does more than feed the mill. It buys us time, and we are putting that time to work. With enough ore on-hand to carry Phase 1 through ramp-up and early production, our mining teams have been free to turn their attention deeper into the mountain, where underground development for Phase II is already well underway.

While the drills advance below ground, the mill above it has gained an important partner. Metso, a global leader in minerals processing technology, is on site at Sangdong, working alongside our operators to support the Phase 1 ramp-up. The same engineers helping us fine-tune today's plant are laying the technical groundwork for tomorrow's future.

That brings me to the news many of you have been waiting for.

Phase II is officially a go.

Underground development is progressing, and we are placing orders with Metso for the equipment that will power the expansion, including new mills. The same partner that helped bring Phase 1 to life will now help build its successor. We expect Phase II to be completed in 2027, further ramping capacity to up to 1.2 million tonnes per annum and positioning Sangdong to potentially produce over 460,000 MTU annually, making it one of the largest tungsten mines outside of China and definitively the largest producing currently.

Sangdong's ramp-up comes as Stifel aerospace and defense analyst Jonathan Siegmann pointed out that the US strategic stockpile of tungsten has been nearly depleted. This is merely an indication that the Trump administration's push to secure conflict-free critical material supply chains will create massive tailwinds for the metals space, and those miners that can deliver today will be the big winners.

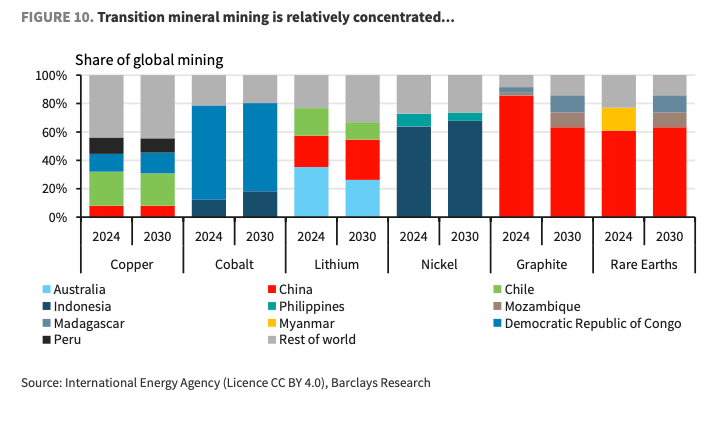
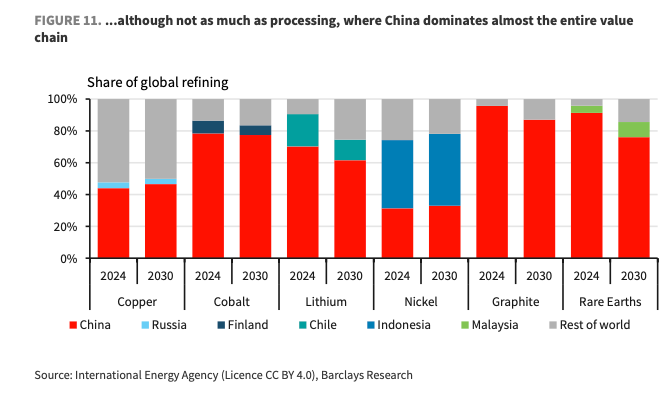
The most glaring problem is that China's control over critical materials mining and refining will remain in play through the end of this decade...

Adrien Rabier, Bernstein's equity analyst covering European aerospace and defense, outlined earlier this week that the rearmament cycle in Europe, and more broadly across the West, is already underway.

The problem is that missiles, bombs, drones, fighter jets, tanks, and just about everything else in the defense world require high-quality critical materials. Shortages could derail production lines, which is why the West is actively seeking to build out new supplies, making early movers such as Almonty and others that can deliver conflict-free supplies the winners.

O’Keefe reiterated a "Buy" rating on Almonty with a 12-month $25.50 target, implying about 93% upside from the previous close cited in the report. 

Tyler Durden Thu, 10/01/2026 - 14:40

What Zohran Mamdani Could Learn From His Father

Zero Hedge -

What Zohran Mamdani Could Learn From His Father

Authored by Peter Jacobsen via The Daily Economy,

Before Zohran Mamdani burst onto the scene of NYC politics with promises of cheap groceries, rent control, and calls to seize the means of production, his father, Mahmood Mamdani, was making important political contributions himself. The elder Mamdani's work is more academic in nature and generally more interesting than the "free stuff" brand of left-wing politics.

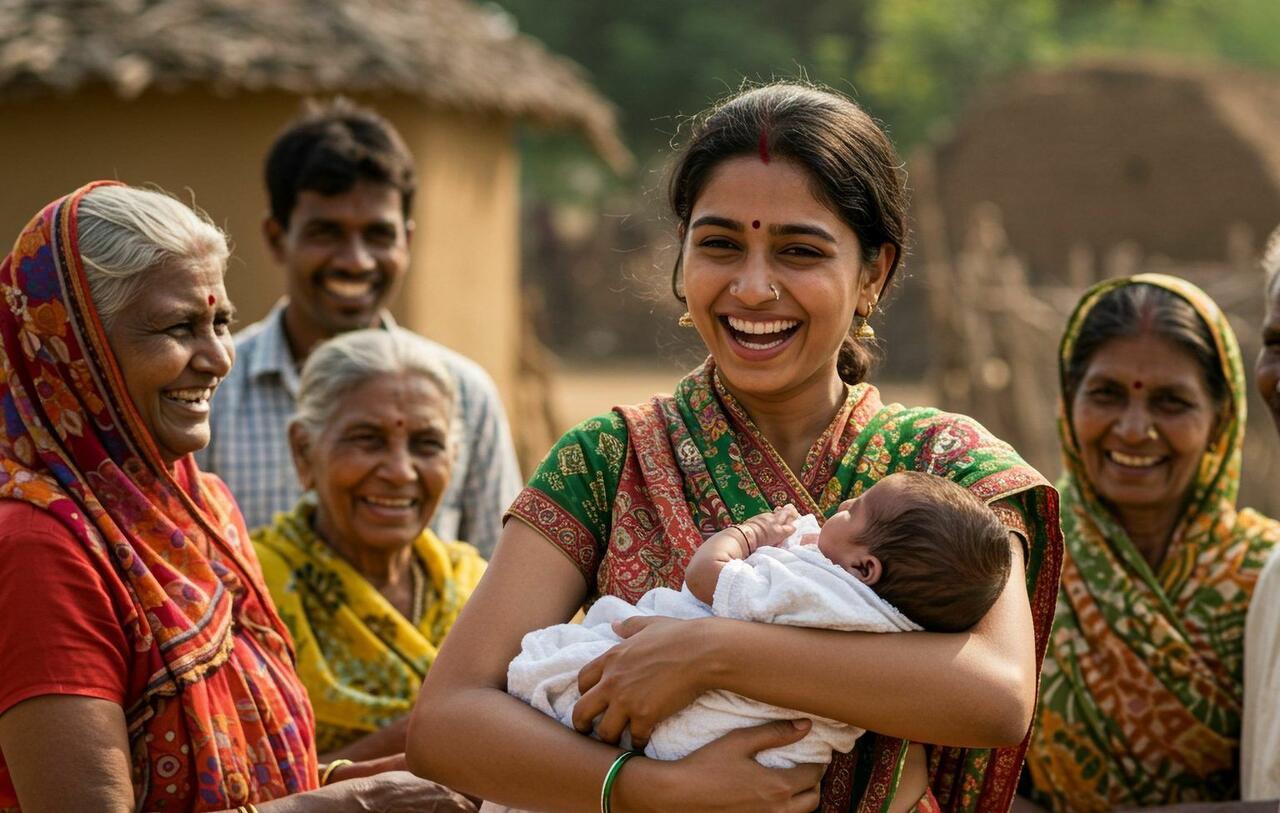
A family welcomes a new baby in rural India. Shutterstock.

In particular, Mahmood was decades ahead on one issue that other academics were getting extremely wrong in the 1970s - population.

In 1972, Mamdani published his book The Myth of Population Control: Family, Caste, and Class in an Indian Village. The book started with a (then) controversial claim: ecologist and population doomer Paul Ehrlich was wrong.

The Population Debate

Ehrlich was catapulted to popular fame after the success of his provocatively titled book The Population Bomb in 1968. Ehrlich's message was simple: the world was overpopulated. In his view, population growth would soon lead to mass famine throughout the world. His beliefs on this issue were so strong that he went as far as to claim England would collapse before the year 2000 due to food shortages.

Ehrlich's message was popular, and he wasn't the lone anti-population force. Around the same time, the United Nations formed its Fund for Population Activities (UNFPA), and USAID also began taking on major population aid projects. The theory shared by these groups was clear - if countries want to develop economically, they need to slow their population growth.

In hindsight, we know much of this thinking was both wrong and dangerous. Overpopulation concerns amounted to nothing, and anti-natal policy ended up having devastating impacts in developing countries. The UNFPA's first "population awards" were given to Indira Gandhi in India and Qian Xinzhong in China.

Both of these governments are now notorious for the coercive population policies they used to achieve the ends lauded by the UN. Both countries were engaged in aggressive campaigns of sterilization and compulsory abortion, with record rates of sex-selective infanticide. These terrible policies were no secret at the time: Nobel Prize-winning economist Theodore W. Schultz resigned his advisory position with the UNFPA in protest over these awards, calling them a "travesty."

Relatively few voices in the academic world spoke out against overpopulation hysteria. Among those were some economists like Julian Simon and P.T. Bauer. Joining arms in that intellectual fight was anthropologist Mahmood Mamdani.

These figures aren't exactly likely allies. Simon and Bauer could both be broadly construed as free market economists. Mamdani, on the other hand, is a political scientist and anthropologist who frequently publishes on the impacts of colonialism. Their shared humility, though, helped them understand Ehrlich's error.

Mamdani's Fieldwork

Mahmood Mamdani's 1972 Myth of Population Control examined one of the early notorious failures of attempted population policy: the Khanna study. The Khanna study was an attempt by the Rockefeller Foundation to test whether distributing birth control in rural India would reduce birth rates. Early results seemed promising: 90 percent of the local population favored free contraception. Yet birth rates did not fall. What explains this tension? Mamdani provides an answer:

But, in brief, there was only one reason for such behavior: politeness. As one of the villagers explained to me: 'Babuji, someday you will understand. It is sometimes better to lie. It stops you from hurting people, does no harm, and might even help them.'

In other words, the villagers enthusiastically accepted the gift of birth control to be polite! Policymakers and social engineers believed the acceptance of these methods signaled acceptance of lower population growth. Villagers were happy to "help" researchers by accepting their gifts, but had no interest in using them. Why? Mamdani clarifies this early on in his book.

To talk, as Ehrlich does, of 'overpopulation'"' is to say to people: You are poor because you are too many. As this essay will show, people are not poor because they have large families. Quite the contrary: they have large families because they are poor.

But why would the poor want large families? The answer becomes clear through Mamdani's interviews with locals. Mamdani gives one case which is particularly illustrative:

Milkha Singh has no desire to limit the size of his family. His reaction is again typical of the poor in Manupur: 'You think I am poor because I have too many children. [He laughs.] If I didn't have my sons, I wouldn't have half the prosperity I do. And God knows what would happen to me and their mother when we are too old to work and earn.'

The commissioners of the Khanna study simply didn't understand how different the context of rural India was. For Indians, children were necessary for help with daily work and for security in old age. Telling them they would be richer without children would be similar to telling Americans they would be richer if they didn't invest their money. The proposition was nonsensical.

Mamdani's study succeeded by simply allowing the people on the ground to explain themselves. Distant bureaucrats focused on a "population approach to development" simply tried to replicate the conditions that existed in richer countries (like lower birthrates) under the mistaken assumption that those conditions caused growth.

Centrally planned attempts to "solve" rural Indian problems without understanding rural Indian context naturally failed. As one review stated, the policies "have not had a major impact on people's attitudes, practice of contraceptives, or the average fertility rate."

Even if they had been successful, it's unlikely they would've brought development. This result is explained well by economist William Easterly in his book The Elusive Quest for Growth. In it, Easterly examines several "development panaceas" implemented in the twentieth century, of which population control was only one. He points out, "the general wisdom among economists from these [population] studies is that there is no evidence one way or the other that population growth affects per capita growth." In fact, for developing countries, the population growth slowdown in the late twentieth century was accompanied by an economic growth slowdown:

[P]opulation growth has slowed down by about 0.5 percentage point from the 60s to the 90s in the Third World. But, as we have seen, Third World per capita growth slowed down over the same period. Moreover, there is no association across countries between success at slowing population growth and success at raising per capita growth.

This is a terrible track record. Despite coercive policies that harmed millions of individuals, the societal impact was negligible for both the intended purposes: no reduction in population growth and no clear improvement in economic growth resulted from these programs. While China and India gather the most attention for the sheer size of their operations, campaigns of secretive, coercive, and unnecessary sterilizations are also recorded in Mexico, Chile, Bolivia, Peru, Indonesia, Bangladesh, Namibia, Canada and the United States, and as recently as this year.

The rural Indians understood their own lives in a way that would-be developers simply didn't. Economic prosperity cannot be engineered from the top down by changing certain parameters, as if the economy is simply one big equation.

Mahmood Mamdani's work helps to demonstrate the folly of central planning in the face of the complex realities of local communities. His son, New York City mayor Zohran Mamdani, should bring that same humility to his plans for the rest of the economy.

Peter Jacobsen teaches economics and holds the position of Gwartney Professor of Economics. He received his graduate education George Mason University. His research interest is at the intersection of political economy, development economics, and population economics.

Tyler Durden Thu, 10/01/2026 - 14:25

Watch Live: SpaceX To Launch Google AI Chips Into Orbit In Push For Space-Based Data Centers

Zero Hedge -

Watch Live: SpaceX To Launch Google AI Chips Into Orbit In Push For Space-Based Data Centers

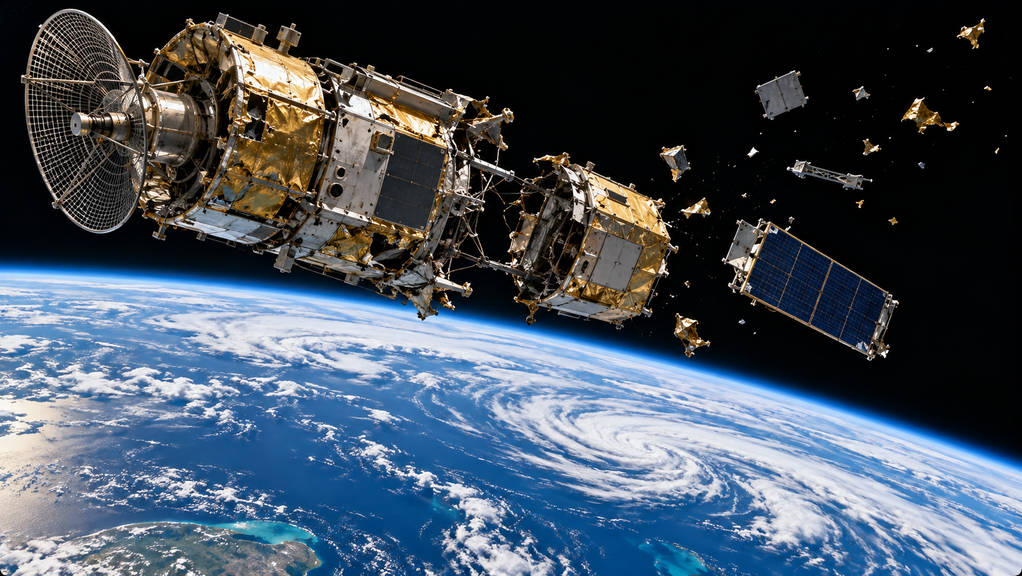
Specialized chips Google designed to run artificial intelligence workloads will be catapulted into low Earth orbit on Thursday afternoon atop a Falcon 9 rocket from California's Vandenberg Space Force Base, with hopes of making data centers in space a reality amid growing backlash on the ground that has sent many terrestrial projects into a tailspin.

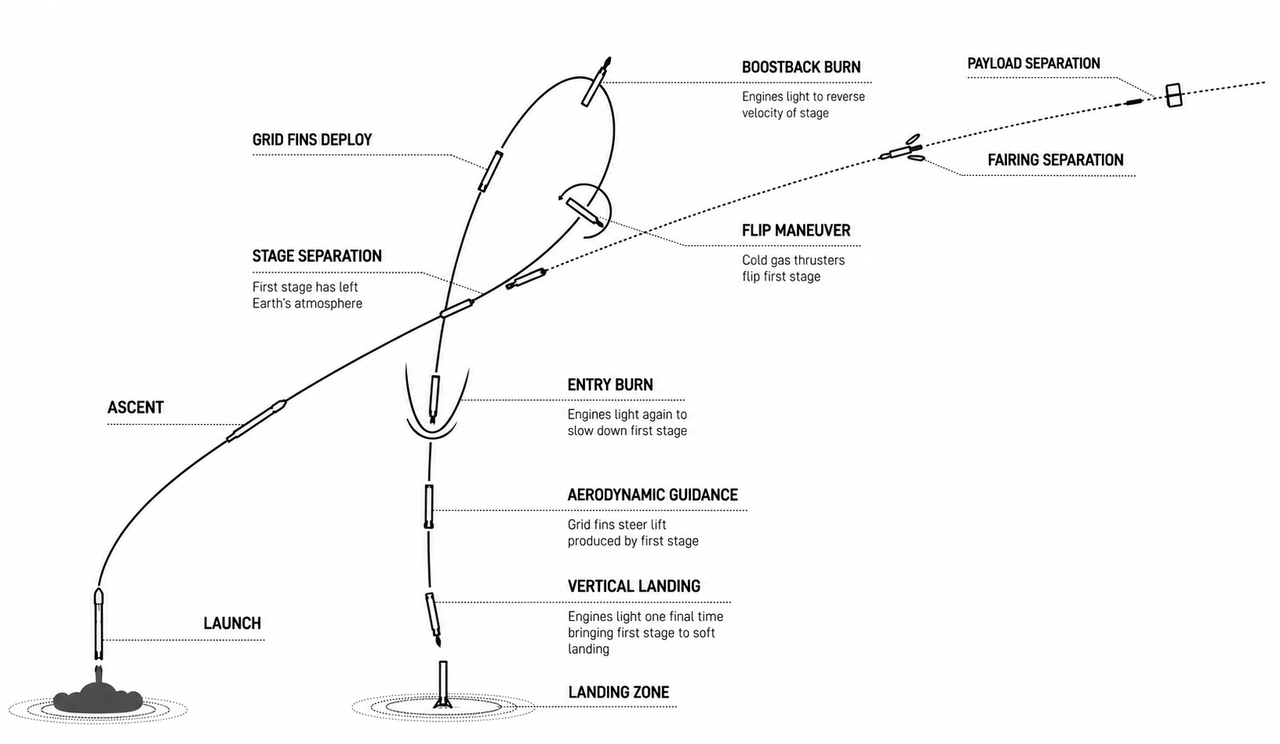
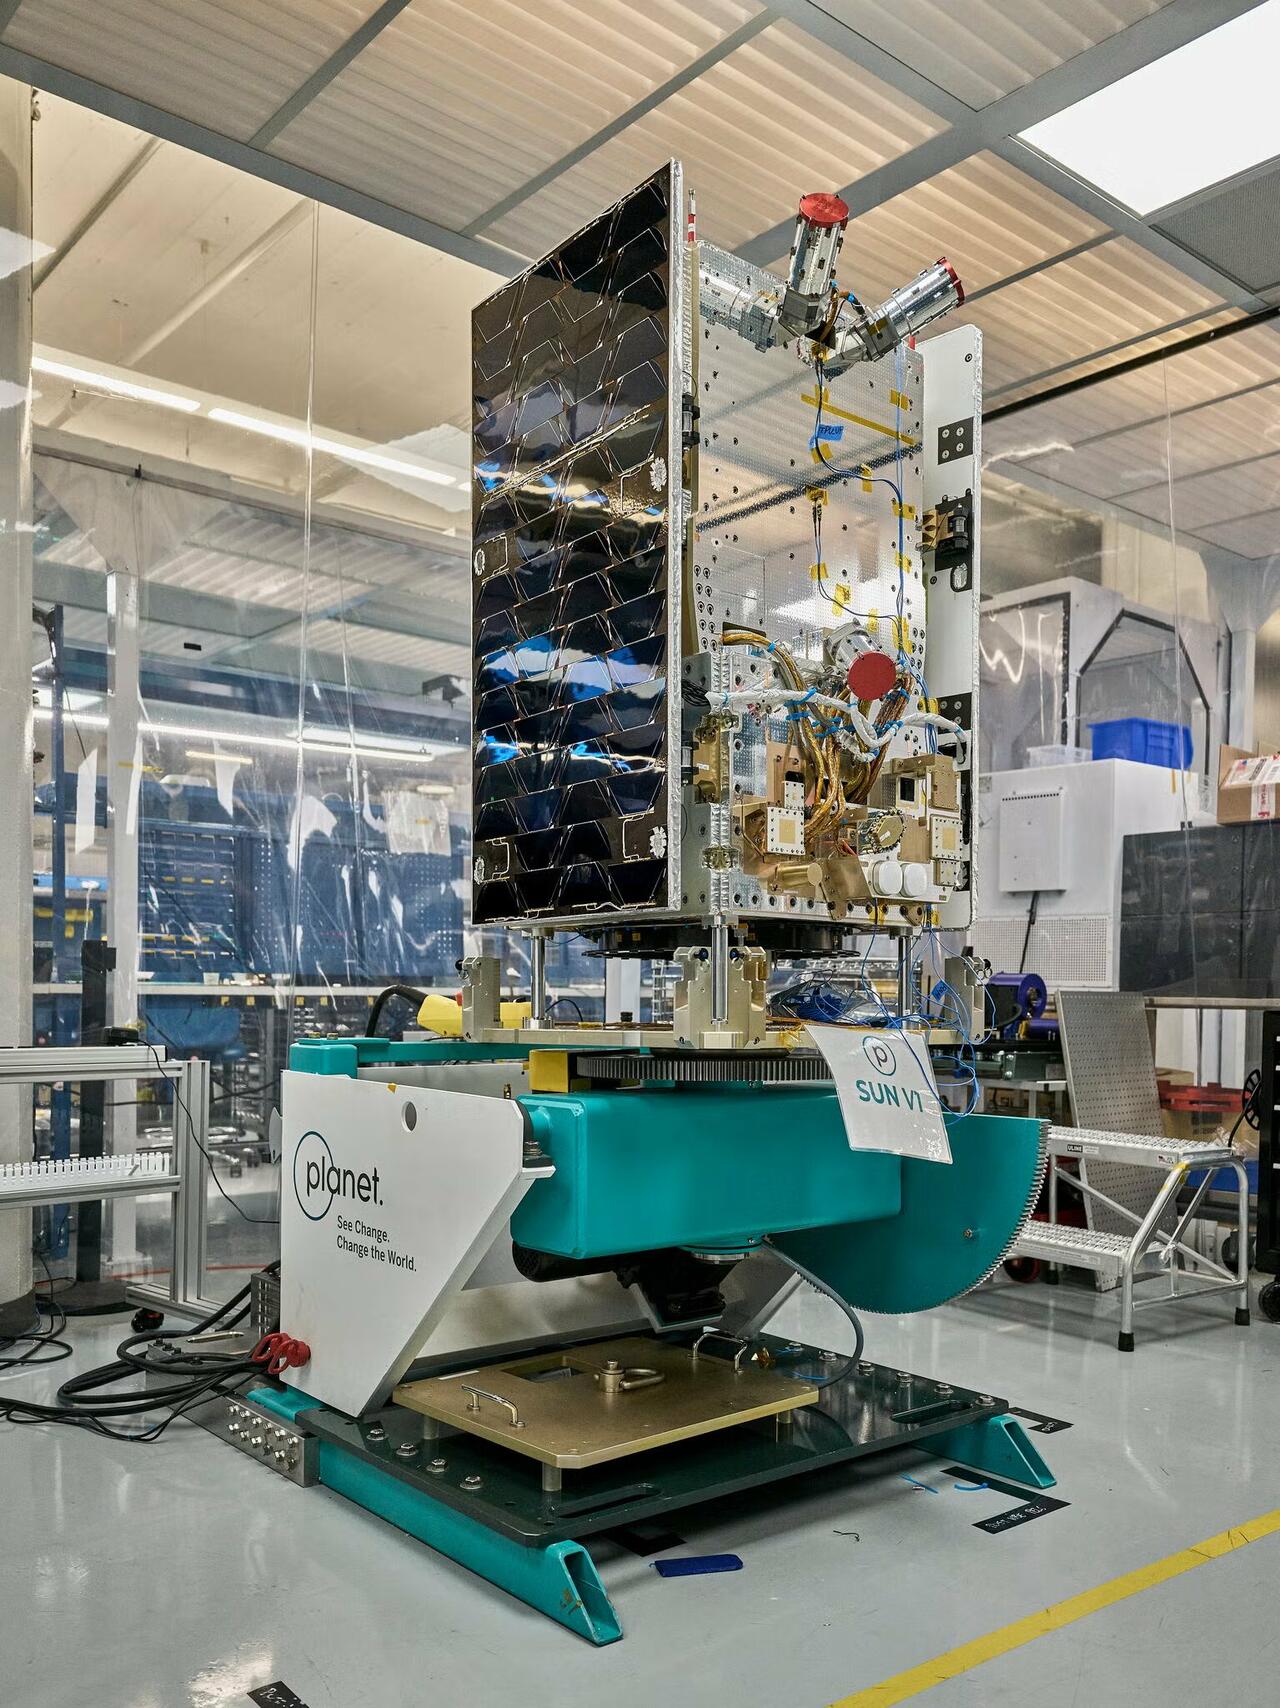
The Falcon 9 launch, scheduled for 2:18 pm Eastern time as part of the Transporter-18 mission, will carry a solar-powered satellite prototype equipped with Google's tensor processing units. This is the first orbital test for Project Suncatcher, Alphabet's effort to deploy data center satellites in low Earth orbit, where power is abundant and regulation is nonexistent.

In a pre-launch announcement, Alphabet said Project Suncatcher is a means of "exploring whether space could one day host scalable machine learning infrastructure."

"In low Earth orbit, satellites can access near-constant sunlight, generating up to eight times more solar power than on Earth. Eventually, it could be possible to link together multiple constellations of satellites, allowing them to manage larger AI workloads while in orbit," the tech giant said.

Alphabet has already tested its TPUs running AI workloads in a specialty lab at the University of California, Davis, but the real test of how its chips will perform in space is nearing and could mark the acceleration of a space-economy boom. The inflection point of the space economy has been the emergence of SpaceX and its rocket development, as well as its blockbuster IPO this summer. 

Much of the space economy hinges on economics, as the commercialization of SpaceX's Starship appears to be getting closer and will drive launch costs even lower.

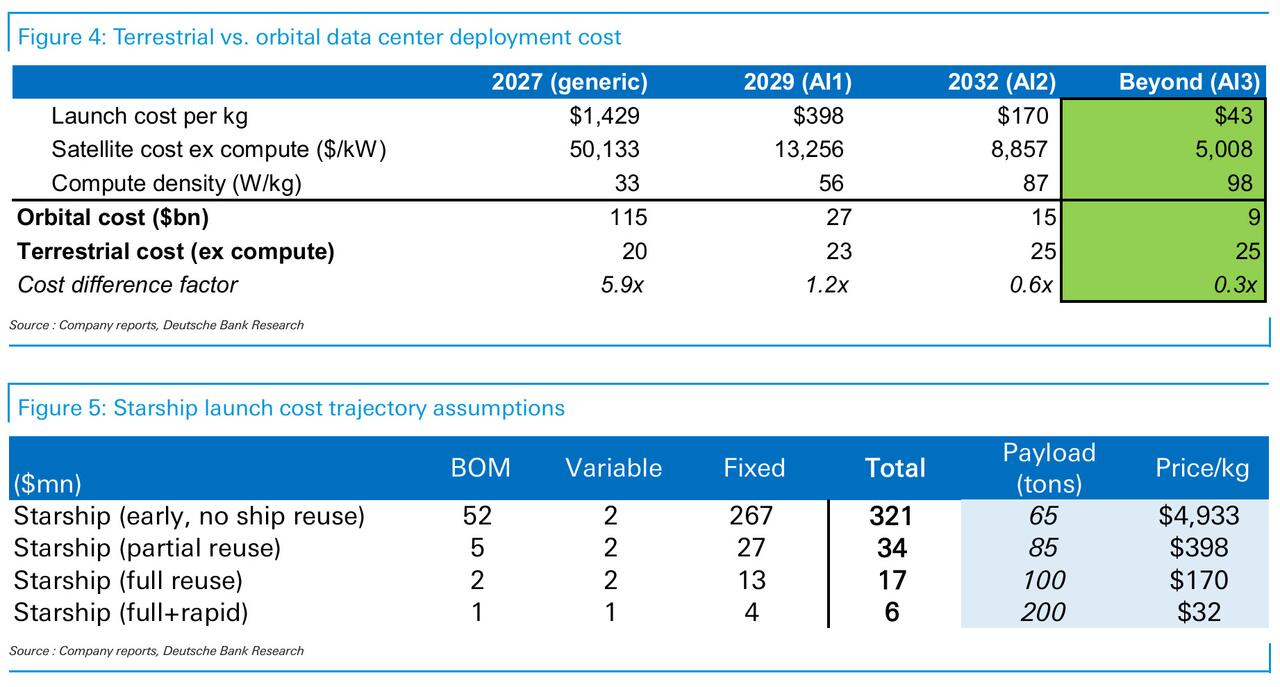
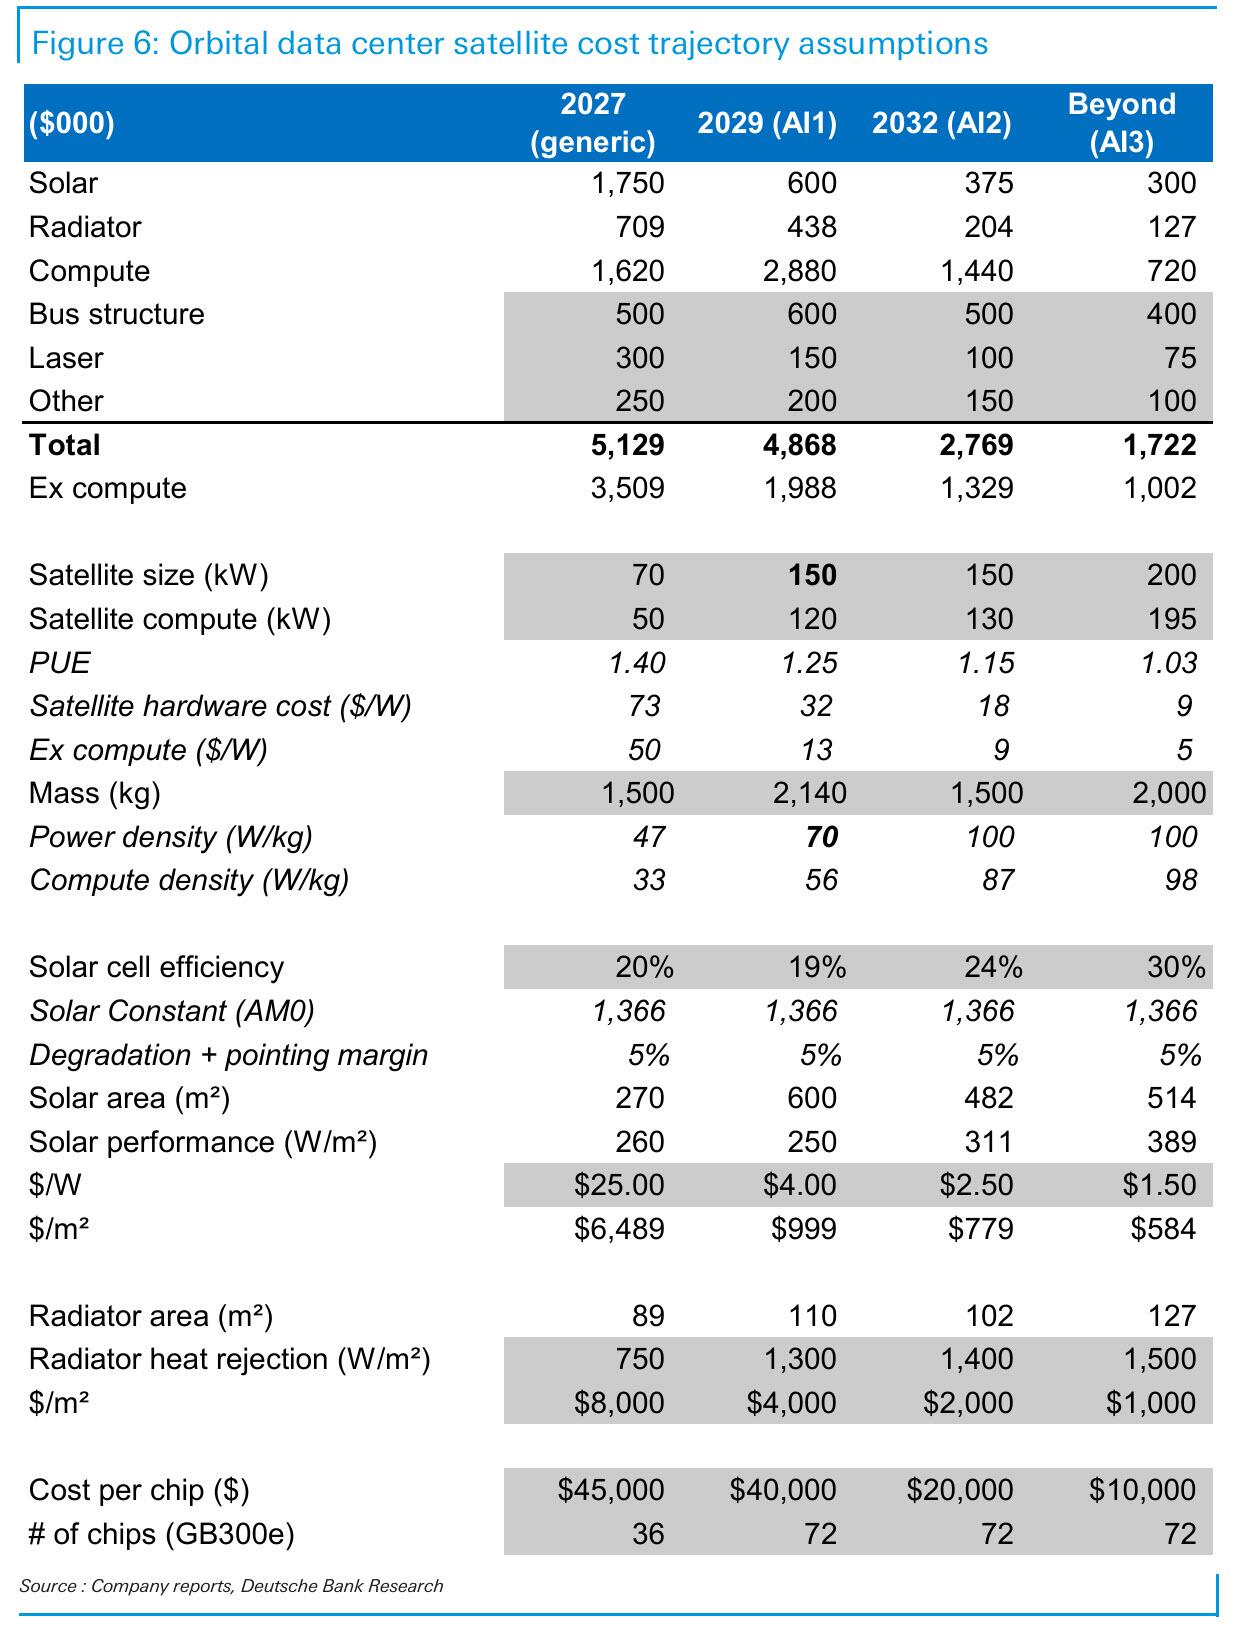
But as we previously highlighted, Deutsche Bank's research over the summer points to one major hurdle: orbital data centers still can't compete economically today with facilities on Earth, but that may eventually change at the end of the decade:

To set a baseline, DB's Edison Yu assumes upfront capex for 1 GW of AI compute on the ground is $38bn and requires $900mm in annual opex (power, maintenance, labor, etc…), translating into $42.5bn over 5 years (based on Epoch AI analysis). Of this amount, compute represents $21bn which carries over to orbital data centers at a 10% mark-up to account for overprovisioning in case of GPU failures. It is likely that GPU failures will not be addressed directly by maintenance but simply each satellite will just operate at lower power in the event of a failure. Therefore, the non compute costs for terrestrial are $21.5bn and ODC essentially has to break below this level post overprovisioning or $19.5bn to be at parity. Looking forward, DB assumes the cost of terrestrial increases going forward. To illustrate, NVIDIA's CEO Jensen Huang recently commented at GTC Taipei 2026 that a new 1 GW "AI factory" could approach $100bn in cost with roughly half being compute-related.

Using current SpaceX launch vehicles and satellite designs, DB estimates the near term cost of deploying a 1 GW space data center constellation would be 6x higher than terrestrial (ex-compute). This gap can narrow to 1.0-1.5x later by end of the decade and then eventually be cheaper in the early-mid 2030s. This reduction is primarily driven by Starship (rapid reusability) and aggressive optimization/scaling of the AI-series satellites (we also refresh the DB Orbital Data Center Model which goes deeper into the economic viability of launching AI infrastructure into orbit)

Even if orbital data centers become economically viable and cost-competitive with ground facilities, engineering challenges remain, such as managing temperature extremes and shielding chips from radiation. 

Watch Rocket Launch Live:

Tyler Durden Thu, 10/01/2026 - 14:03

Debt Crisis Back? European Bond Markets Crash, CDS Explode Amid France Budget Panic Contagion

Zero Hedge -

Debt Crisis Back? European Bond Markets Crash, CDS Explode Amid France Budget Panic Contagion

It's starting to smell awful sovereigny crisisy in Europe all over again.

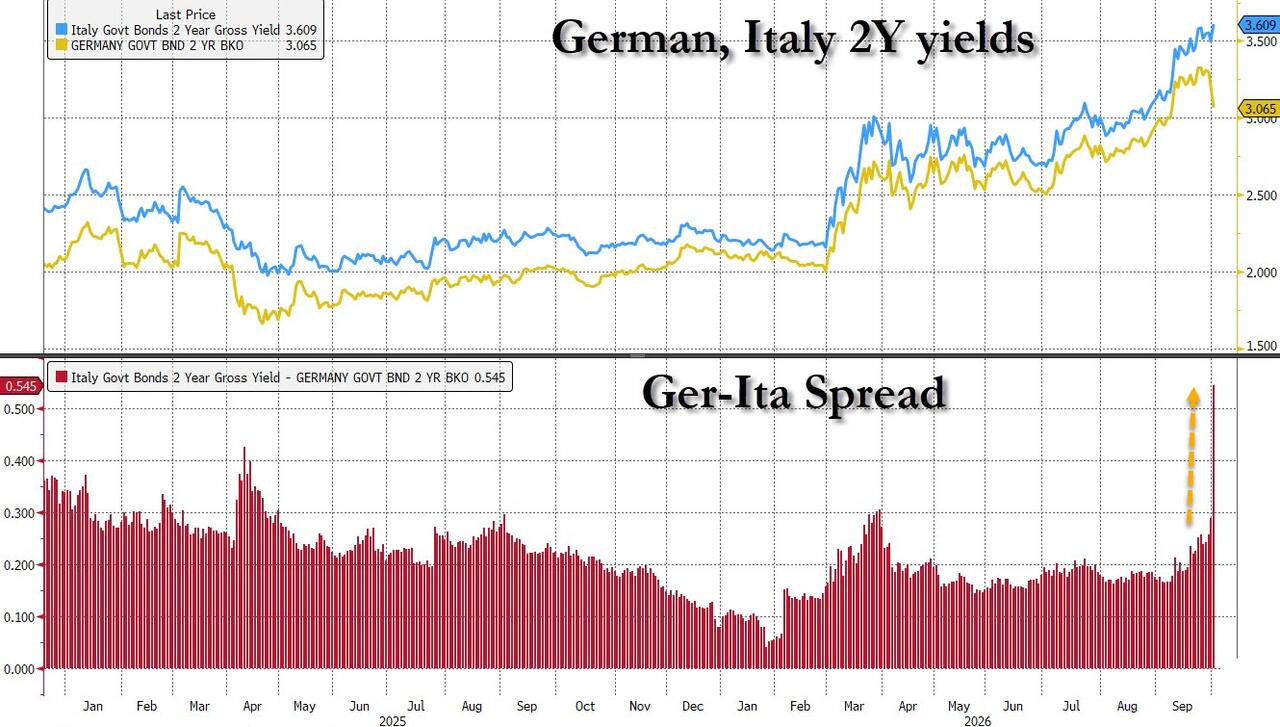
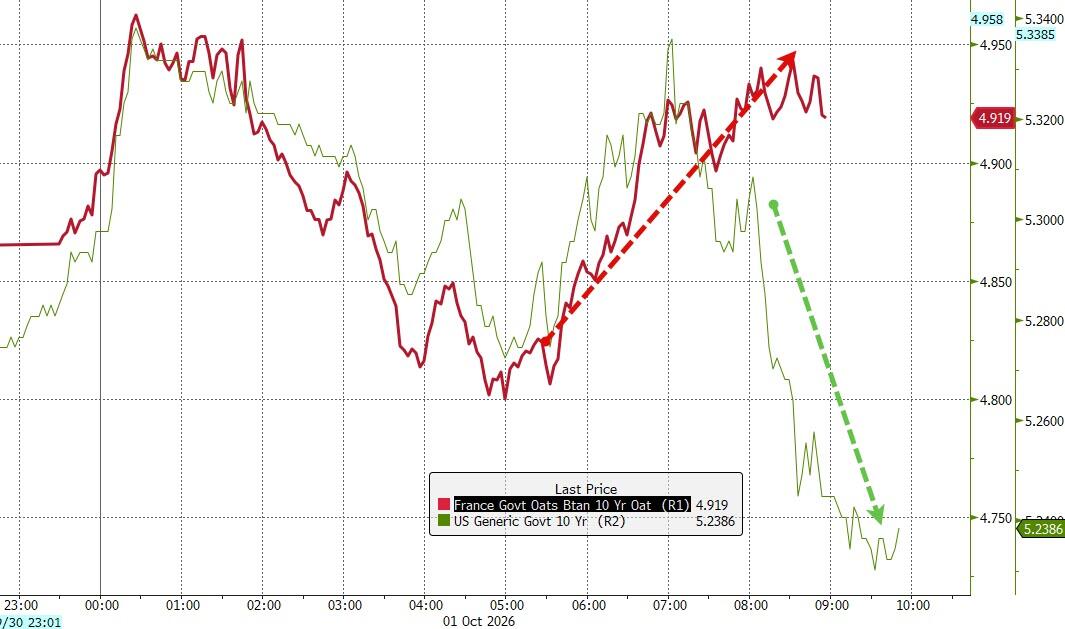
In a vivid deja vu to the peak European debt crisis days of 2010 (and 2011... and 2012... and 2015), credit spreads, credit default swaps and the risk premium in euro-area government bonds exploded on Thursday to levels not seen in over a decade, following a rout sparked by concerns around France’s fiscal and political situation which in addition to local social chaos, is starting to spill over into other markets.

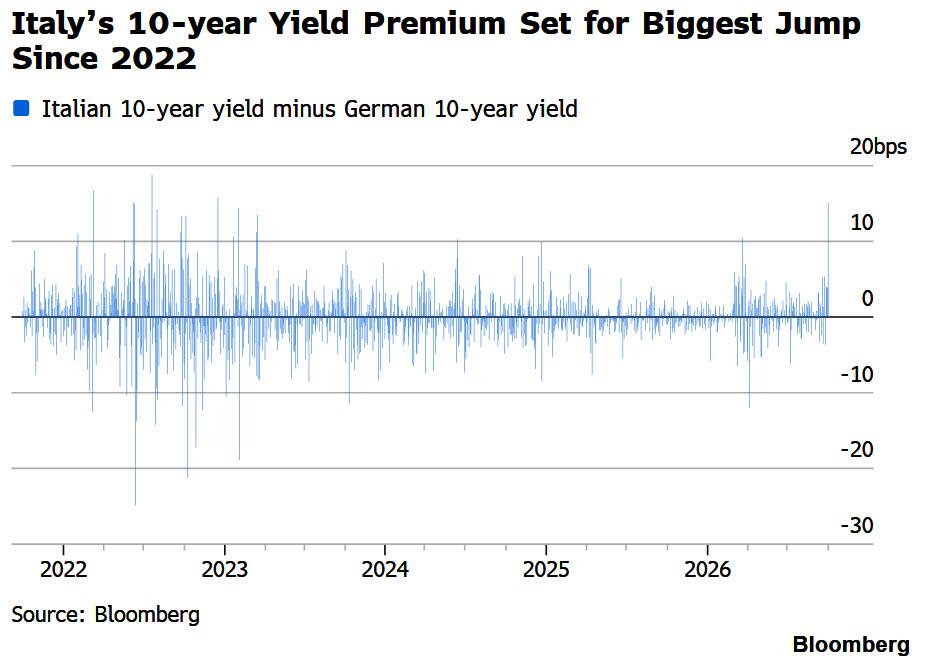
The spread between Italy and Germany’s two-year yields almost doubled to 55 basis points on Thursday, the biggest daily jump since 2020 on a closing basis.

The equivalent gap for France rose as much as 22 basis points, the most since 2012.

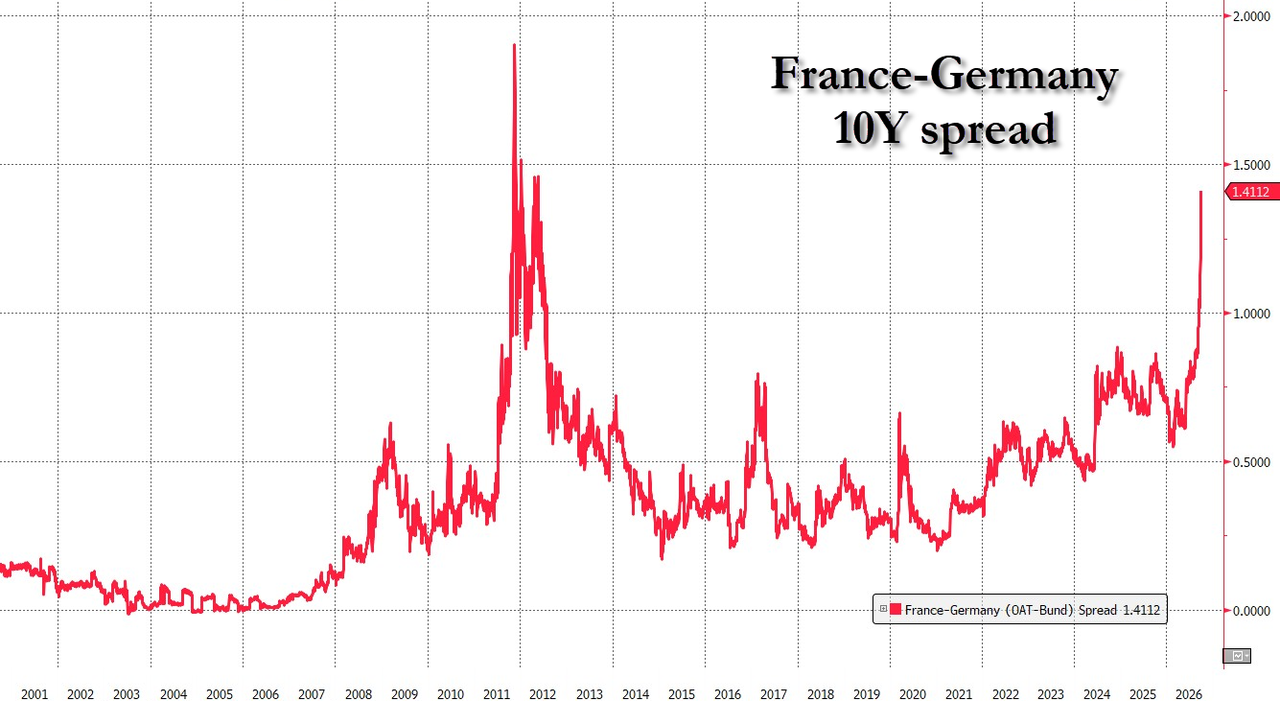
Meanwhile, the spread between 10Y French OATs and 10Y Bunds has soared to 1.41%, the highest going back to the 2012 European Sovereign debt crisis.

A measure of French bond risk reached another milestone this week as investors positioned for political upheaval next year and an ongoing deterioration in the country’s public finances. The widely watched spread between France and Germany’s 10-year yields jumped 14 basis points ... 

... to 141 basis points, already the widest since 2012.

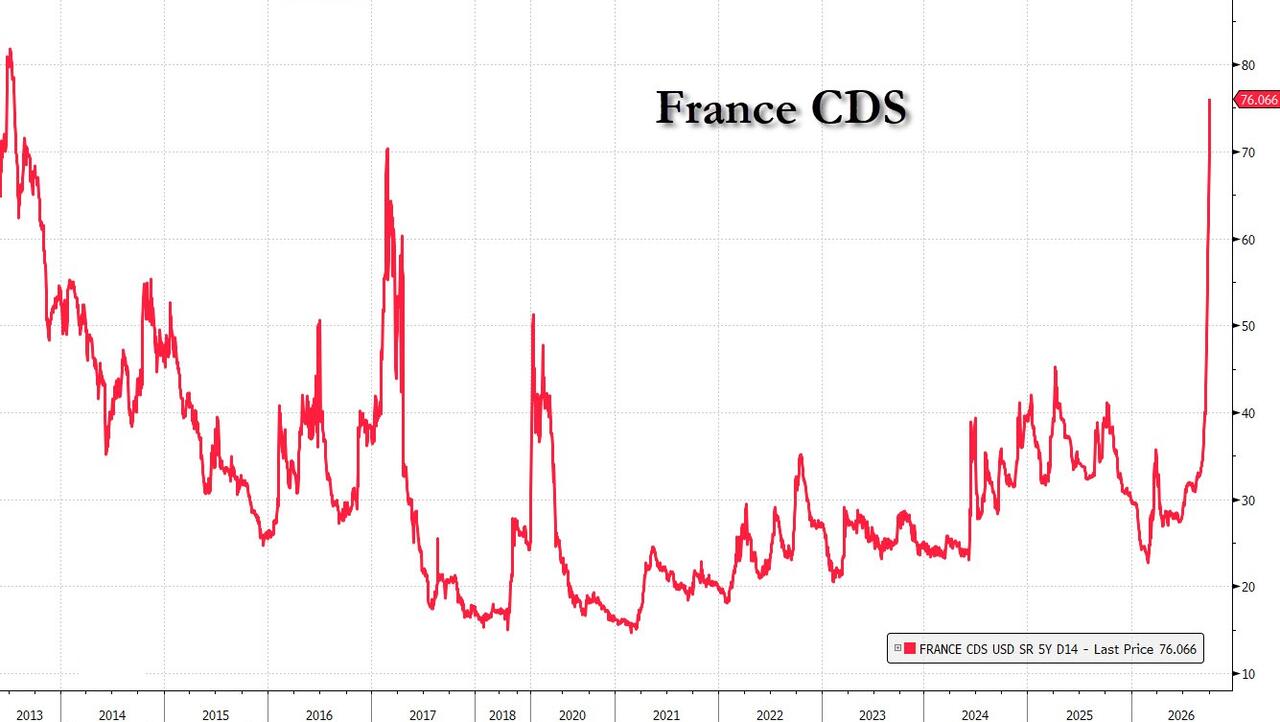
Amid the bond rout, French CDS has more than doubled in the past month on mounting fiscal viability fears. 

French credit got monkeyhammered ahead of today's French budget presentation, which plans to consolidate to a deficit of 5% for next year versus 5.4% expected this. This is how Goldman economist Alex Stott explained it: 

“Today is only the formal presentation of the budget. I am not expecting to learn much new relative to the interview Lecornu gave two weeks ago. The more important information will likely be RN's counter-proposal due next Tuesday, which will give us a sense of the concessions they will ask for in the bill, as well as their plans for the economy if they win the elections. Regarding the budget process, I am expecting it to be very drawn out, potentially lasting until mid-December or early next year. What could accelerate the timeline is if more acute market stress forces political parties to a quicker compromise”

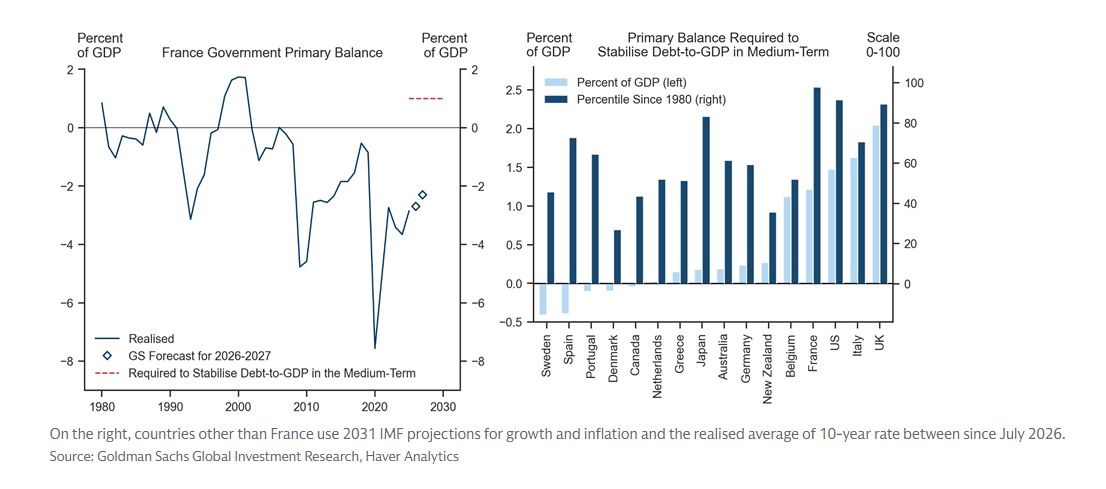
Alex has also modeled France's medium term debt-GDP path here, which Goldman sees rising to 125% at start of next decade.

In a nutshell, the issue with France is that:

  1. Average interest rate is set to rise to 3% from 2%
  2. The primary balance required to stabilise debt is +1% on Goldman's market forecasts; like many countries but one that France has rarely achieved (95th percentile over past 35 years)
  3. If you take market rates its even worse; would need to run a 2% primary surplus, something that has never been achieved
  4. We have elections and policy uncertainty.

As for why the OAT-Bund spread is moving now, some more from Stott:

“past few sessions of spreads widening have not come on the back of any fundamental news. Our current-quarter growth tracking has been pretty stable at 0.1% over the last month, the deficit and budget news were in line with expectations, and polls have been relatively stable too. But clearly have a difficult market backdrop with moves in energy/rates and election uncertainty. Plus would also note discussion around Melenchon’s rise in 1st round polls to second. Though our simulation give him little change of winning in second round (exhibit 7 here: https://tinyurl.com/msm344p9) his proposal to cancel French debt held at Banque de France is the kind of deep tail which can lead to bigger market moves even if his winning probability only shifts slightly”

French Primary Balance, and Balance Required to Stabilise Debt to GDP

Today's violent moves came as German bonds rallied sharply as investors rushed for the region’s "safest" asset (which is ironic for a country whose entire manufacturing sector has been gutted by China), while dumping everything else. Curiously, Treasury yields also surged during the European session, as locals dumped US paper alongside the periphery, although the selloff ended the moment Europe closed.

The nervousness suggests the selloff in French markets caused by the nation’s struggle to get a grip on runaway public finances is starting to sap risk appetite more broadly, as we first laid out two months ago in "France's €107 Billion Deficit Shock: The Next Euro Debt Crisis?"

“France has been slowly but steadily breaking,” said Mike Riddell, lead manager of Fidelity International’s Strategic Bond Fund. “But today feels like the first day that broader financial markets have noticed.”

He's right: 

  • ITALY-GERMANY TWO-YEAR BOND YIELD SPREAD WIDENS MOST SINCE 2020
  • GERMANY-FRANCE 10Y YIELD SPREAD CLOSES 14BPS WIDER AT 141BPS

There were also signs that markets are starting to price the toll from higher yields - which tighten financial conditions - on the economy. Traders slashed wagers on the extent of further interest-rate hikes from the European Central Bank, and swaps are no longer fully pricing three more quarter-point increases. As recently as Tuesday, they were betting on at least four more. 

“The price action is very unusual,” said Rohan Khanna, head of European rates strategy at Barclays. “We are reducing ECB rate hike expectations, yet the EGB complex, with the exception of Germany and the Netherlands, is selling off. It is reminiscent of periods when bond market fragmentation was a major concern, such as during the European sovereign debt crisis.”

In other words, it is reminiscent of when Europe was on the verge - or already in - a debt crisis. 

As Bloomberg notes, investors and strategists also said the moves suggested hedge funds have been forced to capitulate on positions as the market moved against them and losses piled up.

“One of the favorite hedge fund carry trades was to own short dated France versus swaps,” added Fidelity’s Riddell. “Some of these positions must have been reduced the past few weeks, but it feels like a capitulation.”

Tyler Durden Thu, 10/01/2026 - 13:44

Jensen, Zuck Gang Up On 'Doomer' Dario Behind Closed Doors At White House AI Summit

Zero Hedge -

Jensen, Zuck Gang Up On 'Doomer' Dario Behind Closed Doors At White House AI Summit

Tuesday's White House "Super Intelligence" luncheon was sold as a kumbaya moment. Tech titans flanked President Trump on the driveway after signing a voluntary, "morally binding" pledge to police themselves, and the cameras got their picture of a united industry calming the public's nerves.

Behind the scenes, it was a different story.

According to the Wall Street Journal, Nvidia's Jensen Huang was among a group of executives who confronted Anthropic CEO Dario Amodei after the East Room lunch. They wanted to know why he keeps going to such extremes in public about what AI models can do and how dangerous they might be. The exchange took place in the Roosevelt Room, where a smaller group of CEOs and White House aides were hammering out the final text of the principles.

Amodei apparently didn't fold. He told his fellow executives that the public deserves honesty about model capabilities, and that downplaying the risks isn't an option.

Meta's Mark Zuckerberg supplied the other half of the pincer during the lunch itself. When Amodei raised his safety concerns, Zuck reportedly answered that the way to address them was for the industry to follow through on the very principles everyone was about to sign and self-regulate (bitch!). 

Translation: Nice speech, Dario. Sign here.

Zuck Holds The Pen

Zuckerberg apparently played a central role in finalizing the accord, talking frequently with Trump and with Commerce Secretary Howard Lutnick. Lutnick's department runs a key government AI testing unit. It is also the department that, as we noted in July, cut off access to Anthropic's Fable 5 and Mythos 5 for about 2½ weeks before lifting the export controls.

The push for Tuesday's lunch reportedly began at last week's state dinner for Xi Jinping, where Zuckerberg sat next to House Speaker Mike Johnson and the two talked AI policy. From there, Zuck and Huang worked the phones to line up the CEOs while Trump and Johnson organized the event to build consensus.

Amodei skipped that state dinner and got his own private dinner with Trump on Sunday, his first face-to-face with the president.

Look at this: 

The Regulator That Wasn't

Over the summer, Anthropic, OpenAI and Google had rallied around a FINRA-style self-regulatory organization that the administration was considering, modeled on the body that polices brokerages. Huang, Zuckerberg and Elon Musk then told Trump that such a body would concentrate too much power in the hands of the leading labs. The idea was scrapped.

Many of the same concepts survived in Tuesday's principles anyway, including tougher internal model reviews during development and outside testing. The difference is that nobody now has the job of enforcing them. Trump has floated a 10-person committee to oversee the sector, but House Speaker Mike Johnson stressed the pledge is "voluntary on behalf of the industry," and House Minority Leader Hakeem Jeffries called it "entirely unenforceable."

Huang, Zuckerberg and Musk aren't the only ones making the capture argument. When Amodei published his We Must Pace the Frontier essay last month, former AI czar David Sacks fired back that Amodei and Sam Altman are the frontier, holding a de facto duopoly on frontier intelligence. Skeptics have long argued that a "pacing" regime run by the incumbents looks a lot like a moat. That argument gets louder when the company preaching caution is reportedly lining up an IPO at a valuation of around $2 trillion.

From Punching Bag To 'Outstanding People'

Watching the absolute drama between frontier AI companies and the Trump administration has been an exercise in whiplash. 

  • The Pentagon threatened to blacklist Anthropic over its guardrails on military use and then followed through. A federal appeals court upheld that blacklisting just last Friday.
  • Commerce forced the roughly 2½-week shutdown of Fable 5 and Mythos 5 over security concerns.
  • The pacing essay helped knock the legs out from under the AI trade, and the next day Trump went after Dario by name for "pretending to be a 'perfect little angel.'"

Yet on Tuesday, Amodei told reporters that the industry and the administration could win the AI race safely if they worked together. Asked why executives should be trusted to police themselves, Trump said: "Because they're outstanding people." Director of National Intelligence Jay Clayton, reportedly in line to become Trump's next AI czar, went further - calling the gathering "one of the most, if not the most, constructive and collegial industry meetings" he had ever seen.

Zuck's Glow-Up

Then there's Zuckerberg, who went from banning Trump after January 6 to helping write his AI policy. In Trump's second term, Meta settled the lawsuit over the suspension, rolled back its fact-checking, hired Trump-friendly executives and donated to the president's pet causes. On Tuesday, Zuck was all smiles beside Trump at the presser, saying the industry wants to give Americans confidence that the technology works as intended.

What a pack of whores, eh? 

Tyler Durden Thu, 10/01/2026 - 13:20

NANO Nuclear Buys The One Thing You Can't Speed Up: A Fuel-Cycle License

Zero Hedge -

NANO Nuclear Buys The One Thing You Can't Speed Up: A Fuel-Cycle License

Ask anyone in the nuclear business what holds up the "renaissance" and you won't hear much about reactor physics. You will hear about paperwork, fuel, and paperwork for fuel. The DOE's Deputy Secretary James Danly put it bluntly last week: "If we are going to have this nuclear renaissance, we are not going to be able to do it without fuel."

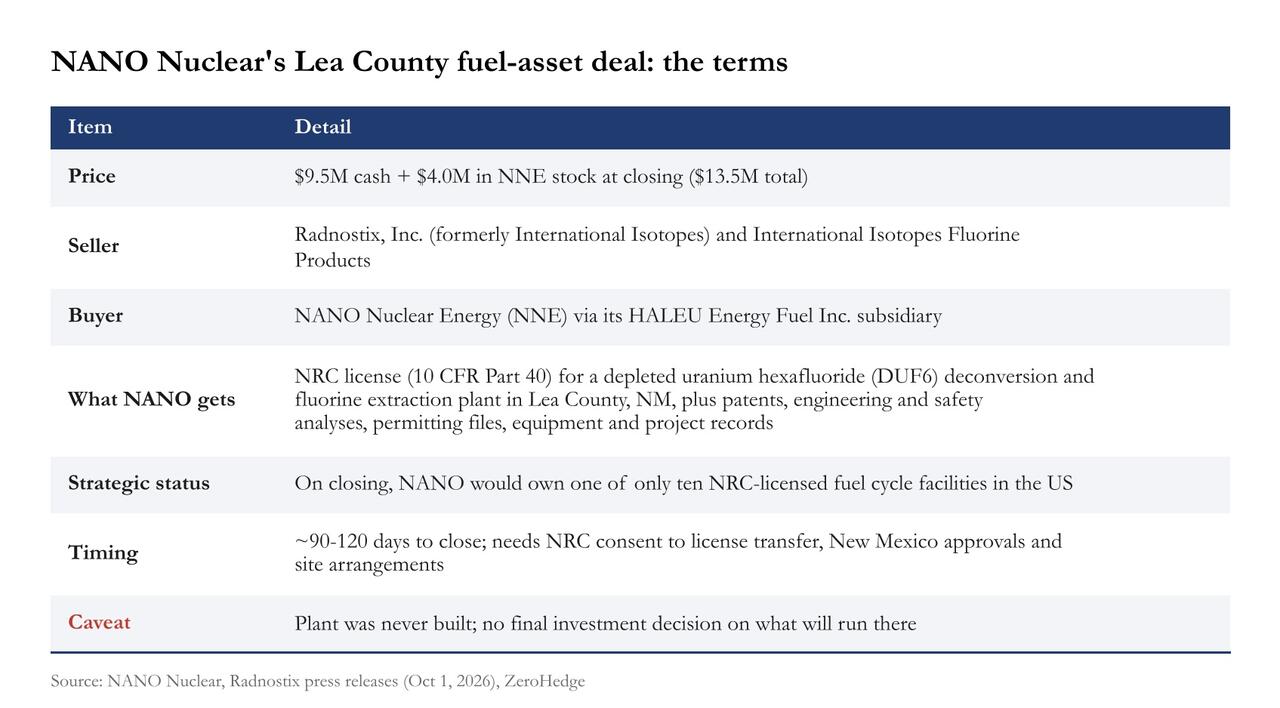
So it makes sense that the latest move from the NANO Nuclear (NNE), a company we have covered at length over the past year due to its leading position in the nuclear space, is a reactor-free one. This morning NANO and its subsidiary HALEU Energy Fuel signed a definitive agreement to buy the US nuclear fuel processing assets of Radnostix (formerly International Isotopes) and its subsidiary International Isotopes Fluorine Products.

The headline terms:

After rising 2.5% premarket, NNE stock is now lower on the day which is odd for a stock that jumped 13% on the similarly sized $13M Secured Transportation Services deal in May. That fits a market where, as Goldman's sector specialist put it in mid-September, "inbounds have been extremely light on the nuclear front" (we discussed this in "Uranium Term Prices Hit A Record... So Why Is Nuclear Getting Nuked?"). We would argue the market is underpricing this one.

What is NANO buying?

The asset is the old International Isotopes Fluorine Extraction Process and Depleted Uranium Deconversion (FEP/DUP) project near Hobbs, NM. According to the NRC, the license was issued on October 2, 2012, with a 40-year term. It was the first commercial license of its kind in the US, and the facility was "not yet constructed."

The plant was designed to take the depleted UF6 "tails" left over from enrichment, convert them into stable uranium oxide for disposal, and recover the fluorine as high-purity fluoride products, including anhydrous hydrogen fluoride, which goes into semiconductor and solar manufacturing. Put differently, it turns nuclear waste into chip-fab chemicals, which is about as 2026 as a business plan gets.

Location matters more than anything else here. The site is about 30 miles from Urenco USA in Eunice, NM, which, per the World Nuclear Association, is the main US commercial enrichment plant (4.3M SWU/yr), with a multibillion-dollar expansion planned. Urenco produces tails continuously. The NRC lists its DUF6 storage authorization at up to 251 million kg, and Urenco's long-term tails plan currently points to a facility in the UK. A licensed deconversion site next door is the obvious alternative.

So why did the plant sit idle for 13 years? According to a Fission Chain write-up, the main obstacles were a condition in Urenco's own license that blocked it from using deconversion plants producing anhydrous HF (removed in 2025), plenty of cylinder storage space at Eunice, and no committed buyer. In short, there was a license and no customer. The Russian uranium import ban, whose waivers end in January 2028, plus the federal push for domestic enrichment, have since changed that.

Why this matters more than the price suggests

The important line in NANO's release isn't about depleted uranium. It's this one: the existing license provides "a significantly more efficient regulatory pathway" to add other fuel-cycle processes through NRC license amendments rather than starting a new application from scratch. CEO James Walker said the deal gives NANO "multiple potential pathways to expand our domestic fuel cycle capabilities while preserving the flexibility to determine the development strategy."

Translation: NANO is paying $13.5M for a regulatory head start. Anyone who has watched an NRC fuel-cycle licensing proceeding (the Eunice license itself took years) knows the time saved is worth far more than the purchase price. That's especially true at a moment when, per the WNA, the US has one conversion plant (Metropolis, running at 50-70% of its 15,000 tU/yr license) and one commercial-scale enrichment plant.

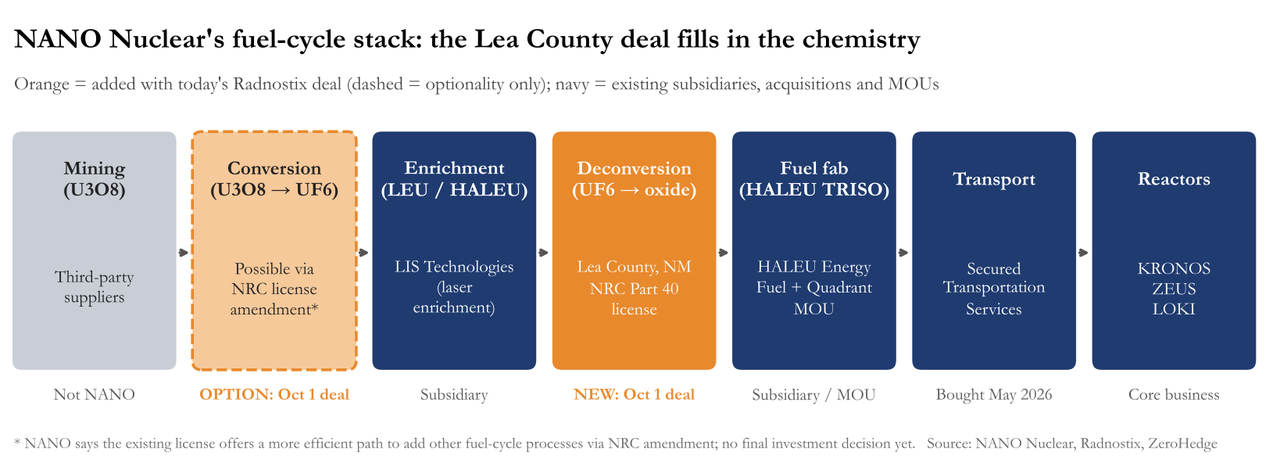
Readers who followed our September 5 piece should have seen this coming. When NANO signed its MOU with Enveniam, the lead project integrator for LIS Technologies' laser enrichment plant, one of the six workstreams listed was "conversion and deconversion." At the time we said NANO's vertical integration was moving beyond the "corporate slide deck." Four weeks later it has a licensed site for that workstream.

Source: NANO Nuclear, Radnostix, ZeroHedge

Laid out like this, the plan is clear. Since January NANO has put together, piece by piece:

  • Enrichment: LIS Technologies' laser enrichment, which founder Jay Yu has pitched as "significantly cheaper to operate as well as less capital intensive to deploy" (Feb 4, May 15), with Enveniam as integrator for the planned Tennessee plant.
  • Fuel supply and fabrication: the HALEU Energy Fuel subsidiary (today's buyer), plus the Aug 18 MOU with Quadrant Nuclear Industries on domestic HALEU supply.
  • Logistics: the HALEU transport package (Mar 16) and the $13M acquisition of Secured Transportation Services, which ran the largest single international HALEU shipment in NNSA history (1.7 MT from Japan) and turned NANO into a revenue-generating company.
  • Fuel handling: Fortil's work on the KRONOS fuel handling and storage system (Jul 24).
  • Reactors: KRONOS at UIUC, where the NRC has begun its technical review of the construction permit we flagged as "a defining moment" on Apr 2, along with ZEUS and the space-focused LOKI.
The sell side: fuel is where the money is

The best argument for NANO spending on fuel instead of only on reactors comes from Goldman, which says nothing about NANO directly.

When the bank's clean energy strategist Brian Lee initiated on Standard Nuclear (STDN) at Buy in August, he described a TRISO fuel supplier with a capital-light model, "significant pricing power in the early-stages of TRISO fuel adoption," EBITDA margins reaching ~65% by 2030, and revenue going from under $20M in 2026 to over $1BN by 2030. All of this rests on Goldman's forecast of ~15GW of cumulative SMR deployment by 2035, up from zero today, which would require about 100 MTU of fuel. Goldman added that STDN's ability to fund growth without more external capital makes it "unique amongst peers tied to the growth of SMRs."

That is the gap NANO is trying to close: a reactor developer has to raise money until first power, while a fuel supplier can charge everyone along the way (think of it as a debt-free neocloud charging others for the privilege of using its compute until AI becomes profitable). Northland's Jeff Grampp made the same point after last month's WNA symposium in London. He cut his NNE target to $22 from $37 to reflect higher costs of capital and a slower 2030-35 buildout, and said he prefers fuel and supply-chain names "that make money now" (BWXT, LEU, EU, URG). If the market pays fuel-cycle multiples and NANO keeps acquiring fuel-cycle assets, the conclusion follows.

Goldman's view on the macro backdrop got stronger overnight. Commenting on the US-Korea package announced after Tuesday's close, which includes $120BN for eight large US reactors (six AP1000s, two APR1400s), Lee said it reinforces "a constructive long-term backdrop for nuclear deployment and the broader fuel cycle," and that it is "likely to further exacerbate the anticipated uranium supply deficit in the 2030 time frame" (full note available to pro subs). Eight gigawatt-scale reactors need conversion, enrichment and, eventually, tails handling. That's more UF6 moving through a supply chain with very little spare capacity.

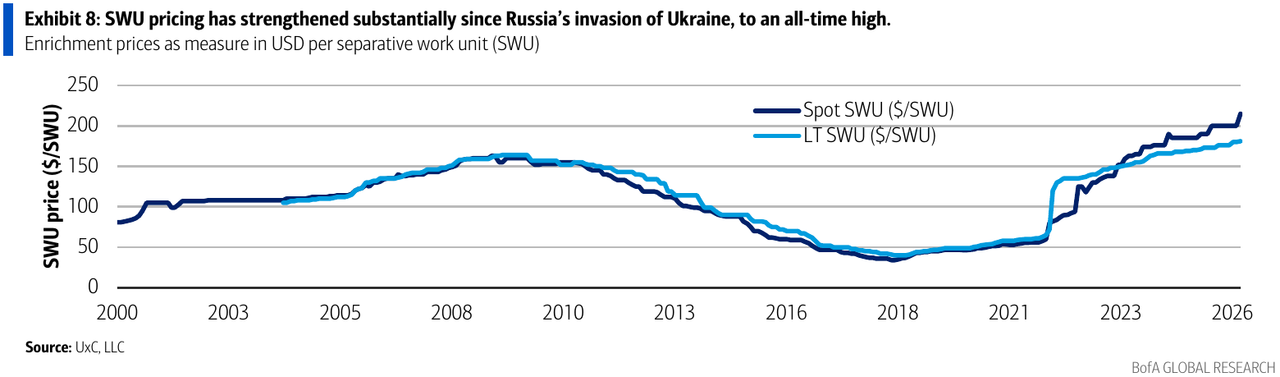
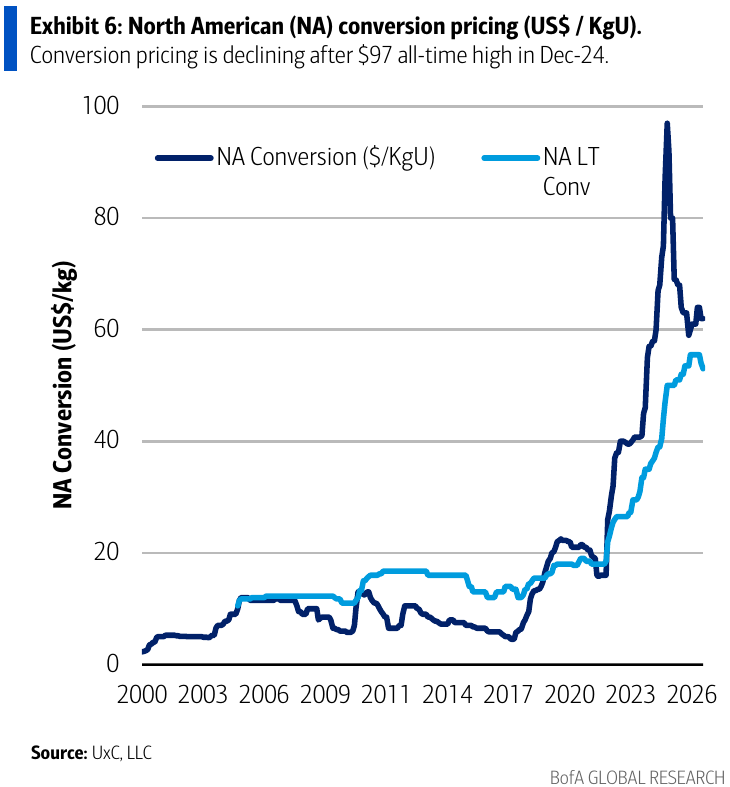
The prices already show it. BofA's charts from the WNA symposium show SWU prices at an all-time high and still rising, and North American conversion still at roughly 3x pre-2022 levels even after falling from the $97/kgU peak in December 2024:

Source: BofA Global Research, UxC

Source: BofA Global Research, UxC

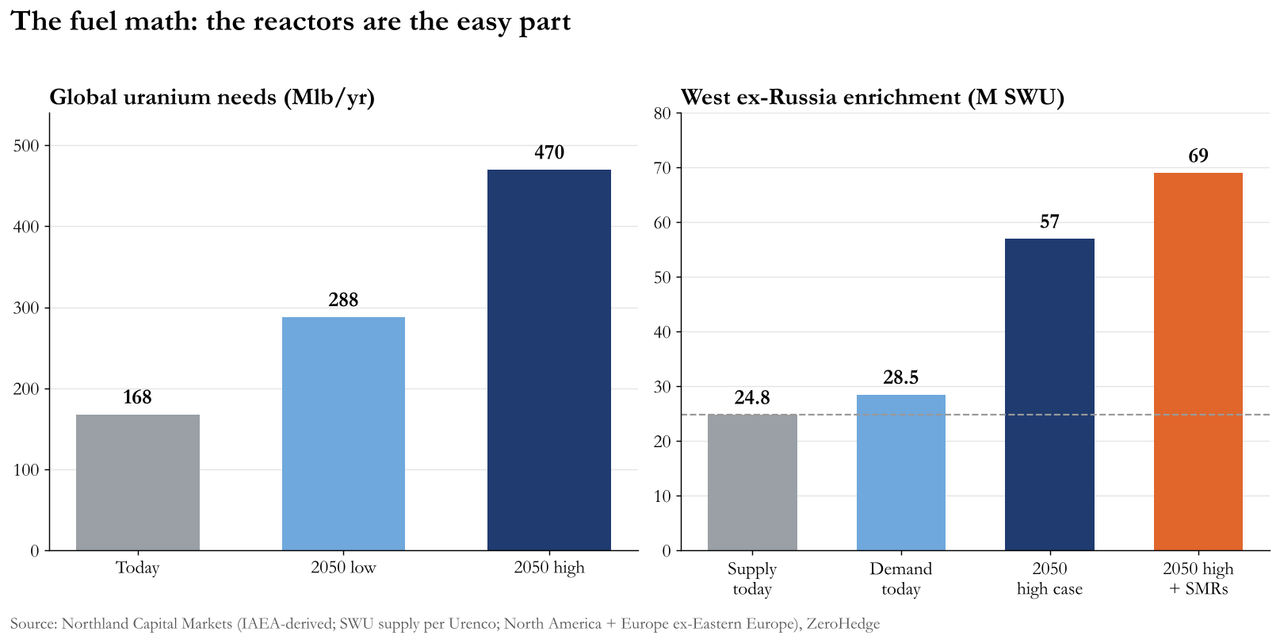
And the long-run math is worse. Northland's IAEA-based numbers show Western (ex-Russia) enrichment supply of 24.8M SWU against demand of 28.5M SWU today, which means the West is already short before a single SMR is built. In the 2050 high case with SMRs, demand rises to about 69M SWU:

Source: Northland Capital Markets (IAEA-derived), ZeroHedge

HALEU is the tightest part of all. Seaport notes Centrus is targeting 12 MT/yr of HALEU capacity with first new output in 2029, and that a single Oklo Aurora needs about 7 MT for its first core. That means America's flagship HALEU program can fuel about two reactors a year at the start. This is the main reason microreactor developers are moving down the fuel chain themselves.

Can NANO afford to be a fuel company?

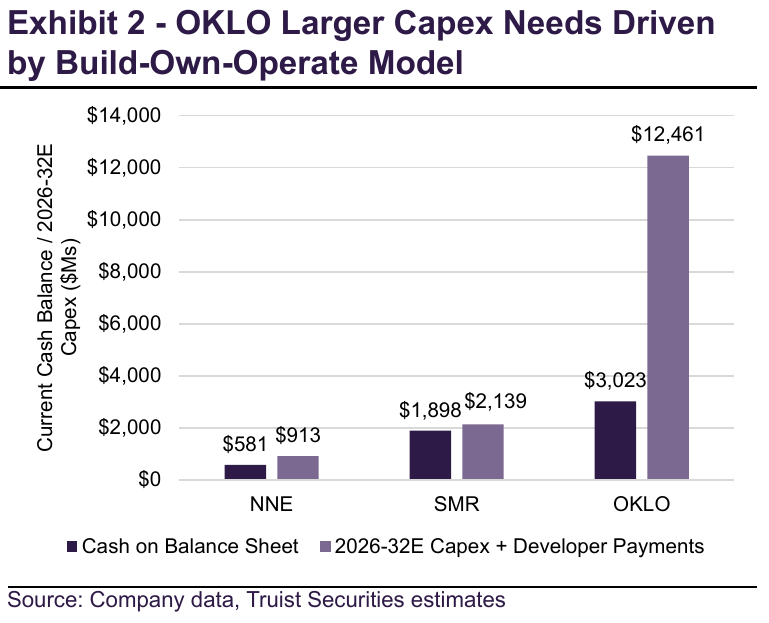
This is the obvious objection. Laser enrichment, fuel fabrication, a deconversion plant, a transport fleet, three reactor designs and a space reactor is a lot for a company with an ~$850M market cap (or maybe the market cap should be much bigger as the market doesn't see the big picture yet). On that, Truist has a useful chart. Comparing cash on hand with 2026-32E capex plus developer payments, NANO's gap is the smallest of the three listed SMR names: ~$581M of cash against ~$913M of needs, versus $3.0BN against $12.5BN for Oklo's build-own-operate model:

Source: Truist Securities (Sep 28, 2026)

At $13.5M, today's deal is about 2% of NANO's cash, and the $4M stock portion causes minimal dilution. The real cost is whatever NANO decides to build in Lea County, and since there is no FID yet, that figure doesn't exist. Bulls will call that optionality. Bears will say it's a blank check. Both have a point.

What could go wrong
  • Licenses aren't plants. This one has been unused for 13 years. A Part 40 source-material license for deconversion is useful, but adding conversion, or anything that touches enriched material, means amendments, NRC review and possibly a different licensing basis. "More efficient" doesn't mean "fast."
  • New Mexico. The deal needs approval from state officials. Lea County supports nuclear (it already hosts Urenco), but Santa Fe fought hard against Holtec's proposed interim spent fuel storage site in the same corner of the state. A deconversion plant is a very different animal, but expect the same activists to show up.
  • Focus. Each new business line adds another place where something can go wrong. The base case for NANO is still KRONOS at UIUC, with construction targeted for late 2027 according to Roth (Buy). A delay there won't be offset by a fluorine plant.
  • Sentiment. The market has been ignoring good nuclear news: term uranium is at a record ~$96/lb (UxC via TD Cowen), yet NLR is down 12% YTD while the AI ETF is up 25%, and Holtec pulled its IPO. NANO had 24% of float sold short as of May, so the stock can swing hard in either direction.
The big picture

We've argued for years that modular, behind-the-meter reactors are the only real long-term answer to AI's power demand. But a reactor without fuel is a very expensive paperweight, or as NANO's own pitch put it in May, "what good is a fancy new car if there's no gas stations to fill it?" Over the past nine months NANO has been building the gas stations, plus the refinery, the tanker trucks and now a licensed site to handle the waste.

The 2012 license was worthless while there was no market for domestic fuel. Then came the Russian ban with its 2028 waiver cliff, $2.7BN of federal enrichment awards, record SWU prices, Urenco expanding 30 miles down the road, and an $120BN reactor package that, in Goldman's words, makes the 2030 fuel deficit worse. With all that, a 40-year NRC fuel-cycle license looks very cheap at $13.5M. NANO paid about the same for a trucking company.

Whether NANO can turn a dormant license into a working plant is the next question, and the 90-120 day closing period followed by the first NRC amendment filing will be the first real test. Strategically, the deal makes sense. NANO is positioning itself to be the company that supplies the fuel, not just another reactor developer waiting for it.

Tyler Durden Thu, 10/01/2026 - 12:40

Sen. Marsha Blackburn Sues Former Special Counsel Jack Smith

Zero Hedge -

Sen. Marsha Blackburn Sues Former Special Counsel Jack Smith

Authored by Troy Myers via The Epoch Times,

Sen. Marsha Blackburn (R-Tenn.) on Wednesday sued former special counsel Jack Smith and the Department of Justice (DOJ) over a subpoena Smith's office issued for her phone records during his investigation of President Donald Trump's actions around Congress's certification of the 2020 election.

Blackburn alleged Smith violated her constitutional rights and was unlawfully appointed. She asked the U.S. District Court for the Middle District of Tennessee to order the Justice Department to destroy the records or return them.

The senator opened her lawsuit with the quote: "The prosecutor has more control over life, liberty, and reputation than any other person in America," from former attorney general and later Supreme Court justice Robert Jackson.

Blackburn claimed that Smith violated her First Amendment right of association and Fourth Amendment right against unreasonable searches and seizures.

She accused the former special counsel of violating the Speech or Debate Clause in the Constitution, which provides members of Congress and their aides with immunity from criminal prosecutions or civil suits stemming from their actions taken within their official duties.

The Supreme Court has previously said this legislation must not be interpreted literally but instead be construed broadly to accomplish the proper separation of powers it intends to make.

Blackburn also claimed former Attorney General Merrick Garland unlawfully appointed Smith, a private citizen, to special counsel, serving in that role from November 2022 to January 2025, in violation of the Appointments Clause, which gives authority to the president to name federal officials subject to the advice and consent of the Senate.

Blackburn said she never had the chance, as a senator, to offer her advice, consent, or rejection of Smith's appointment.

Furthermore, the Tennessee senator said Smith and the DOJ's actions in obtaining her phone records violated the constitutional provision of separation of powers.

"The facts alleged herein demonstrate that the Executive Branch ignored our Constitution's carefully constructed design and allowed a private citizen to wield enormous power that did not belong to him, resulting in egregious violations of personal liberty and constitutional rights," Blackburn's suit read.

Garland named Smith as special counsel to investigate the events leading up to Congress's joint session on Jan. 6, 2021, for certifying electoral votes from the 2020 presidential election. Smith alleged that Trump, who lost that election, was behind a suspected conspiracy to overturn the results. Trump said he was seeking to delay the certification in order to give states time to investigate claims of fraud and irregularities.

Trump was charged by a grand jury as a result of Smith's investigation and pleaded not guilty, but the charges were eventually dropped after he won the 2024 presidential election.

Blackburn says in the lawsuit that she seeks to prevent any future attorney general from making any "fictitious" appointment as Garland did for Smith.

"No president appointed him, nor did Congress confirm him to serve in that role," the lawsuit read. "Congress did not pass any law that authorized Attorney General Garland to appoint a Special Counsel."

The senator requested nominal damages from Smith in the amount of $1.

As part of the former special counsel's investigation into Trump, which was codenamed "Arctic Frost," Smith issued subpoenas for toll records for Blackburn's phone she used for legislative purposes. The investigation served as "the vehicle" for Smith to conspire and violate Blackburn's rights, the lawsuit alleged, along with the rights of other Republican lawmakers and Trump supporters.

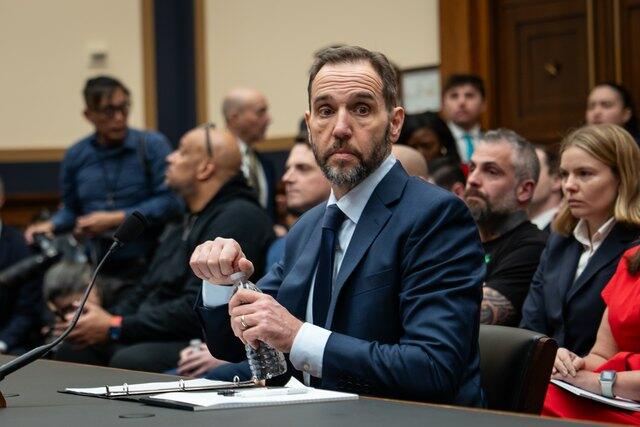
Smith defended his obtaining of GOP lawmakers' cellphone data during congressional testimony on Sept. 29, calling it "materially relevant" to his investigation.

"Given what had happened that afternoon [on] Jan. 6, in my view, added to the powerful evidence we had of Donald Trump's guilt, and the participation of his co-conspirators in his criminal scheme at his behest," Smith said.

In addition to Blackburn, Smith subpoenaed and received records from Ron Johnson (R-Wis.), Lindsey Graham (R-S.C.), Bill Hagerty (R-Tenn.), Josh Hawley (R-Mo.), Cynthia Lummis (R-Wyo.), Dan Sullivan (R-Alaska), and Tommy Tuberville (R-Ala.), and Rep. Mike Kelly (R-Pa.).

Smith also had obtained nondisclosure orders from a federal district judge that prevented the lawmakers from knowing that their phone records were being investigated.

The former special counsel maintained during testimony that his investigation showed Trump "engaged in a criminal scheme to overturn the results and prevent the lawful transfer of power."

Smith could not be reached for comment at the time of publication.

Tyler Durden Thu, 10/01/2026 - 12:20

Federal Judge Blocks $100,000 Fee For H-1B Visas

Zero Hedge -

Federal Judge Blocks $100,000 Fee For H-1B Visas

Authored by Joseph Lord via The Epoch Times,

A second federal judge has blocked the Trump administration from imposing a $100,000 fee on H-1B visas, which allow U.S. companies to hire high-skilled foreign workers.

U.S. District Judge Haywood Gilliam, based in Oakland, California, determined that the U.S. Citizenship and Immigration Services and the State Department did not adhere to proper federal rule-making processes before the implementation of the fee went into effect.

In the 35-page decision, Gilliam on Sept. 30 blocked the agencies from implementing the fee ordered by President Donald Trump in a Sept. 9, 2025, presidential proclamation. The block will remain in place until the federal rule-making process has been followed, the judge ordered, including a formal proposal for a rule change and a standard 30- to 60-day period for public comment.

In the initial lawsuit, the plaintiffs - a coalition of unions, employers, and nonprofit organizations - requested the court block the administration from imposing the new fee and require federal agencies to process H-1B visas in accordance with existing law.

They argued in a lawsuit that Trump has no authority to unilaterally impose fees, taxes, or other mechanisms to generate revenue for the United States.

"Here, the President disregarded those limitations, asserted power he does not have, and displaced a complex, Congressionally specified system for evaluating petitions and granting H-1B visas," the lawsuit said.

The plaintiffs, including Global Nurse Force and the American Association of University Professors, among others, claimed that the Trump administration failed to assess how the fees would affect hospitals, schools, churches, and universities that rely on the H-1B program.

"Without relief, hospitals will lose medical staff, churches will lose pastors, classrooms will lose teachers, and industries across the country risk losing key innovators," litigation and advocacy nonprofit Democracy Forward Foundation, representing the plaintiffs, said in a statement.

The group applauded the ruling.

"Today's decision ... protects a system that was thrown into chaos overnight," attorney Steve Bressler said.

The program offers 65,000 visas annually, with another 20,000 visas for workers with advanced degrees, approved for three to six years.

The White House did not immediately return a request for comment.

In past statements, the administration has defended the legality of its program reforms.

According to a White House fact sheet, the proclamation was to address the misuse of the H-1B program, which Trump said had been exploited by companies to replace American workers "with lower-paid, lower-skilled labor."

White House spokeswoman Abigail Jackson said the fee requirement is legal and that it was aimed at "discouraging companies from spamming the system and driving down American wages, while providing certainty to employers who need to bring the best talent from overseas."

In June, a federal judge in Boston also temporarily blocked the fee. In July, the First U.S. Circuit Court of Appeals declined to pause the ruling.

The U.S. Chamber of Commerce is also suing to challenge the fee. A district judge rejected its claims that Trump lacked the constitutional authority to set the fee, and the Chamber of Commerce is now seeking a review of that decision by an appeals court.

Tyler Durden Thu, 10/01/2026 - 11:40

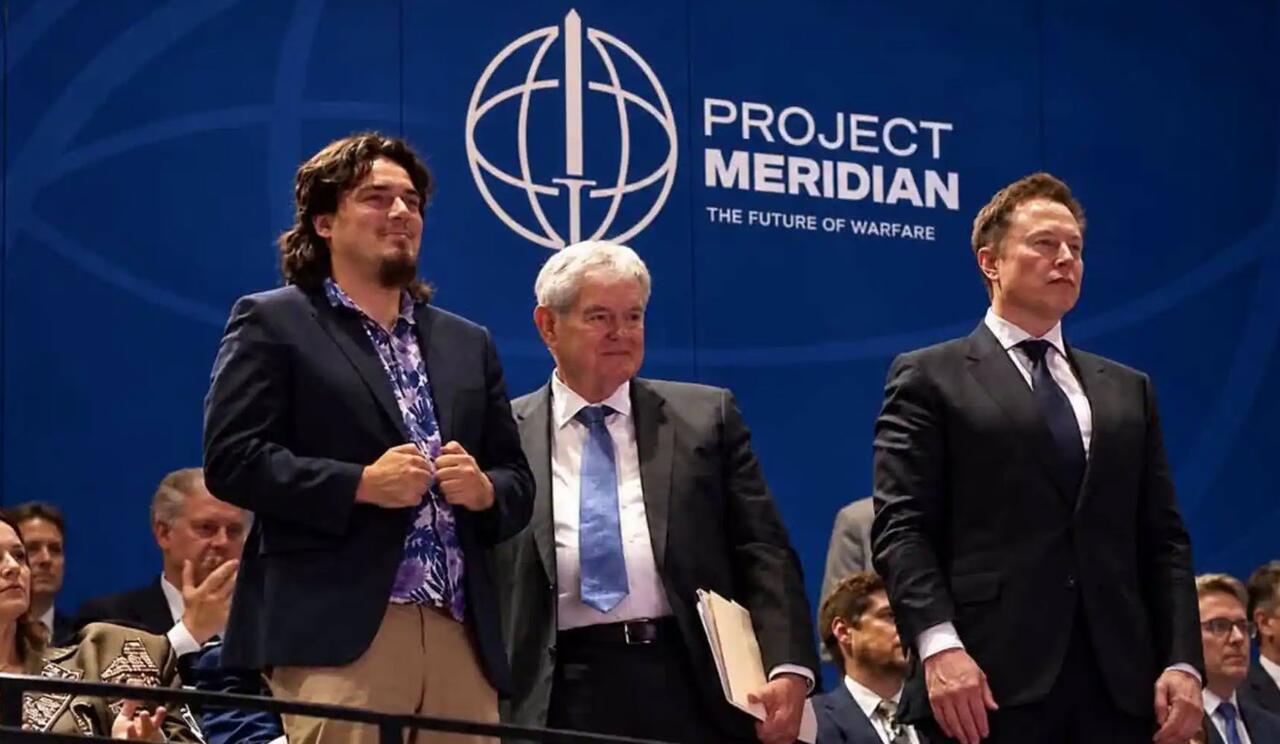
Musk, Luckey And Gingrich Walk Into The Pentagon: Hegseth Unveils "Project Meridian" As Defense Stocks Suffer Record Losing Streak

Zero Hedge -

Musk, Luckey And Gingrich Walk Into The Pentagon: Hegseth Unveils "Project Meridian" As Defense Stocks Suffer Record Losing Streak

What do you get when you put the world's first trillionaire, the man who builds killer drones in Ohio, and a former House Speaker in a room and ask them to design the next century of warfare? According to Pete Hegseth, you get "Project Meridian."

In a sprawling "State of the Force" address to junior officers and enlisted troops at Marine Corps Base Quantico on Wednesday, the Secretary of War announced that Elon Musk, Anduril founder Palmer Luckey and Newt Gingrich (all three were in the audience) will lead an initiative "focused on discovering, developing and fielding the weapons and systems that our children and our grandchildren will need in their lifetimes."

"Its purpose is to creatively look to the future and identify the domains that we must conquer and capabilities we must master," Hegseth said, adding that "the best forecasters of future conflict" do "not solely reside inside the Pentagon."

The project will be overseen by Emil Michael, the former Uber executive who is now the Pentagon's top technology official. Bloomberg said Hegseth offered no further details, although Axios reports that the trio is expected to deliver its findings within 120 days, in both a public and a classified version.

The Customer Asks The Suppliers What It Should Buy

One does not need to be a cynic (although it helps) to notice that two of the three people now advising the Pentagon on which "capabilities we must master" also happen to run two of the companies most likely to sell those capabilities.

Musk's SpaceX handles national security launches and has been a public company since its blockbuster June 12 IPO, which made Musk the planet's first trillionaire. Luckey's Anduril, meanwhile, has gone from defense upstart to prime-in-waiting in record time: it landed a $20 billion Pentagon contract in March, followed in May by a $5 billion raise at a $61 billion valuation, and it also builds the software for Golden Dome together with Palantir. As for Gingrich... Bloomberg notes he "has written a book on technology and entrepreneurism," which is presumably what counts as a defense credential in 2026.

Then there is the Musk comeback. More than a year after the ultimately unpopular DOGE effort and the very public falling out with Trump, which at one point had the administration weighing shutting SpaceX out of Golden Dome, Musk is baaaack. In the past week alone he attended the Trump-Xi state dinner and was slated for a White House AI lunch, and now has his first formal advisory role since DOGE. Some feuds age like milk, others like fine wine; this one appears to have aged like a Pentagon contract.

What Goldman Says About The "Affordable Mass" Pitch

To be fair, there is a real case for letting outsiders shake up how the Pentagon buys things, and few have laid it out better than Goldman's A&D analyst Noah Poponak, who sat down with Anduril's management in June. Goldman's diagnosis was that the legacy defense industry produces "low numbers of expensive, bespoke assets" that are hard to scale, while Anduril designs for "affordable mass" through selective vertical integration, common components across product lines, designs simple enough to automate, and flexible factories that can switch products quickly.

The economics also explain why everyone wants in. Per Goldman, Anduril targets a near 25% total company operating margin over time and gets roughly 70-80% of its revenue from fixed-price work, well above what the traditional primes earn. Poponak also saw "early signs of progress" in Pentagon acquisition reform, including multi-year frameworks and open-testing programs such as Drone Dominance. One of the architects of the "affordable mass" model will now help write the Pentagon's wish list, which is either the most efficient procurement reform in history or the most efficient sales pitch. Possibly both.

Goldman is also constructive on the listed drone names. In his AeroVironment notes this month, Poponak noted that funded backlog rose 37% y/y and 23% sequentially and that AVAV "has exposure to faster growing portions of the defense budget." He pointed to demand for its LOCUST directed-energy counter-drone system (first international order: more than $50mn) and the low-cost Freedom Eagle interceptor, which offers "a significantly lower-cost alternative to traditional missile defense systems."

Enter AutoWarCom

Meridian was not the only new acronym. Hegseth also unveiled a new four-star Autonomous Warfare Command (yes, "AutoWarCom") with "service-like authorities" over drones, AI and command-and-control. It is set to be operational by October 1, 2027. Until then, an interim effort called Project Agincourt will draw on the Defense Innovation Unit and the Drone Dominance program, pairing "operators with entrepreneurs in rapid adaptation cycles." Existing programs such as the Collaborative Combat Aircraft and the Navy's MQ-25 unmanned tanker are being folded in. Hegseth called it "the fastest peacetime shift in modern military history."

The money was already lined up. As we reported in April, the Pentagon's FY27 request seeks $54.6 billion for the Defense Autonomous Warfare Group, up from $225 million in FY26, a 243x increase that would make even a Silicon Valley VC blush.

Add the $1.1 billion Drone Dominance initiative to stockpile 300,000 sub-$5,000 attack drones by the end of 2027 (which sent drone stocks soaring in May), plus the Army's $500 million FPV award to Neros in July, and the direction of travel is pretty clear.

...So Why Are Defense Stocks Puking?

You would think a four-star command dedicated to drones, a 243x budget request and the world's richest man drafting the shopping list would be manna for defense stocks. Instead, the SPDR S&P Aerospace & Defense ETF (XAR) is down 22% from its August 14 peak and in a bear market, and as of Wednesday it is on track for a seventh straight weekly decline, the longest losing streak since the fund launched in 2011. XAR is now down 4.1% YTD while the S&P is up almost 12%.

The explanations are familiar to ZH readers:

  • First, peace is breaking out, or at least the possibility of it: on September 22 reports surfaced that Iran offered to reopen the Strait of Hormuz in exchange for an easing of US military pressure, while Trump floated a negotiated end to the conflict at the UN (that didn't quite work out as expected, although the downward momentum was already in there).
  • Second, the budget is stuck. Neither chamber has passed appropriations, and a stopgap through December 11 would freeze spending at 2026 levels. "The budget is stalled," said Bernstein's Douglas Harned, noting that defense stocks have gone from a 15% premium to the S&P 500 in February to a 12% discount.
  • Third, the midterms: as we wrote two weeks ago, UBS's Allyson Gordon said investors "remain reluctant to add exposure... until after the midterms," and the Polymarket odds on Senate control are the reason why. Whoever controls Congress controls appropriations.

But the most interesting part is who is getting hit. Goldman's US Industrials desk (Ryan Novak) put it bluntly in late August: defense tech "is definitely a tale of haves and have nots," and "the day to day in SPCX is having impacts on the broader 'space' but specifically drone names." The six weeks since have proved the point. The pure-play drone names have been crushed (Red Cat -42%, Kratos -34%, Unusual Machines -28%, AeroVironment -26%), while SpaceX and Palantir are both up roughly 8% since the sector peaked. In other words, the market has already picked its winners, and the biggest of them now has its CEO sitting at the Meridian table.

"Behind The Meter" Comes To Fort Bragg

Buried in the speech was one item ZH readers will recognize. Hegseth said he wants every major US military installation to generate its own power, so that bases keep running if a cyberattack takes down the grid. That will come in the form of nuclear microreactors, with the first targeted to be operational by September 2028 and Eielson AFB in Alaska leading the Air Force effort.

This has been building for a while. The Army launched its "Janus" microreactor program last October, and in August it picked five companies under agreements worth up to $2.2 billion: Antares (Fort Bragg), BWXT (Fort Campbell), General Atomics (Fort Hood), Radiant (Fort Benning) and Westinghouse (Fort Drum). Meanwhile, the Air Force has its own microreactor pairings at three bases and has also been working with NANO Nuclear: AFWERX gave the company a $1.25 million contract last September to study putting its KRONOS microreactor at Joint Base Anacostia-Bolling in Washington, and in July it followed up with a second award to adapt KRONOS for military installations more broadly.

Long-time readers know where we stand. Back in November we argued that every data center must have its own "behind the meter" onsite power generation, and in December we put it more simply: "Make 'behind the meter' mandatory." We have also long said that small modular reactors are the only real long-term answer to America's power crunch. It is nice to see the Pentagon get there too, even if it took the threat of a grid-killing cyberattack rather than a hyperscaler's electricity bill.

And The Rest

In case that wasn't enough for one morning, Hegseth also:

  • Confirmed that general and flag officer billets will be cut by 20%, double last year's 10% (as we previewed on Tuesday), with the reductions due by January 1, 2027;
  • Announced the first new US military base in four decades, a "Next Great American Base" for 15,000-plus troops built in "timeless classical architecture," with states invited to compete to host it, as the Pentagon weighs large troop cuts in Europe;
  • Created an Office of Religious Affairs reporting directly to the Secretary;
  • Launched new "corps of cadets" partnerships with Hillsdale, Liberty, LSU, Mississippi State and Tuskegee; and
  • Accused US media outlets of "treason" over their coverage of the Iran war, a few weeks after Thomas Massie forced a House vote on impeaching him.
  • Oh, and he clarified who may serve: "No fatties...No trannies...No beardos....No weirdoes...No wimps."

The bottom line: the Pentagon is reorganizing itself around drones, autonomy and AI, putting the people who build those things in charge of deciding what comes next, and asking for the budget to match. The market isn't buying it yet. Not because the story is wrong, but because nobody wants to own the stocks until Congress, the midterms and Iran give them a reason to. When that changes, the "haves" are already obvious. The have-nots, at 40% off, may turn out to be the more interesting trade... assuming Meridian's 120-day report leaves any room for them.

Tyler Durden Thu, 10/01/2026 - 11:20

Opposite What You're Told, Markets Don't Wait For The Fed

Zero Hedge -

Opposite What You're Told, Markets Don't Wait For The Fed

Authored by Shahid Islam via RealClearMarkets,

Financial commentary often makes monetary policy sound mechanical. The Federal Reserve raises interest rates, borrowing costs rise. The Fed cuts rates, borrowing costs fall.

History is considerably messier.

Beginning in June 2004, the Federal Reserve raised its federal-funds target 17 consecutive times, taking it from 1 percent to 5.25 percent.

What happened to the 10-year Treasury yield?

It averaged 4.73 percent in June 2004. By February 2007, after the Fed had raised its target by 4.25 percentage points, the 10-year yield averaged 4.72 percent.

Fed funds: 1.00% → 5.25%
10-year Treasury: 4.73% → 4.72%

Alan Greenspan famously called the unusual behavior of long-term interest rates a "conundrum." Federal Reserve researchers subsequently examined the episode and found that during the tightening cycle, long-maturity yields and forward rates actually fell for significant periods even as the Fed repeatedly raised its target.

Yet public discussion routinely compresses this complicated process into a simple phrase: "The Fed raised interest rates."

The distinction matters well beyond monetary history. Investors, homeowners and businesses care less about the overnight rate itself than about the market rates at which they actually borrow and invest. Mortgage rates can rise after a Fed cut or fall before one because markets are continuously revising expectations about inflation, economic growth and future monetary policy.

The Fed's principal policy rate is an overnight rate. A 10-year Treasury yield is something quite different. It is a market price incorporating expectations about economic growth, inflation, future short-term rates and the term premium investors require for holding longer-term securities.

Markets also anticipate the Fed. If investors expect the Fed to cut rates six months from now, bond yields can decline today even though the Fed hasn't acted. Similarly, a credible tightening today could lower long-term yields if investors conclude that it will reduce future inflation.

This isn't evidence that the Fed is irrelevant. It demonstrates something more subtle: markets continuously incorporate information - including expectations about what the Fed itself will eventually do.

Research by economists Cletus Coughlin and Daniel Thornton at the Federal Reserve Bank of St. Louis illustrates the distinction. Once the Fed began using the federal-funds rate as its policy instrument, the funds rate increasingly moved when policymakers changed their target, while the 10-year Treasury yield continued responding to incoming information. The correlation between changes in the two rates consequently fell effectively to zero.

Consider the opposite experiment. From June 2006 until September 2007, the Fed held its target at 5.25 percent. Long-term rates nevertheless continued moving substantially. An unchanged Fed rate didn't mean unchanged financial conditions.

The lesson isn't that markets lead and the Fed follows. Causality runs both ways.

Markets watch the Fed. The Fed watches markets. Both respond to information about inflation, employment, growth, credit conditions and expectations about the future.

But there is a fundamental difference.

The Federal Open Market Committee periodically announces its policy setting for an overnight rate. Financial markets continuously reprice trillions of dollars of securities as new information arrives from millions of investors, borrowers and lenders.

The Fed matters. Its announcements can move markets, and expectations about future Fed policy affect prices today. But that is different from saying the Fed mechanically determines the constellation of interest rates throughout the economy.

Perhaps our language should reflect that distinction. When the Fed changes its overnight policy rate, it hasn't simply "raised interest rates" or "cut interest rates." It has changed one important price inside a much larger price system.

Markets watch the Fed. The Fed watches the markets.

But only one reprices continuously.

Markets don't wait for the Fed.

Tyler Durden Thu, 10/01/2026 - 11:00

Global Crop Prices Log Biggest Quarterly Jump Since Ukraine Invasion As Sticky Inflation Hits Grocery Bills

Zero Hedge -

Global Crop Prices Log Biggest Quarterly Jump Since Ukraine Invasion As Sticky Inflation Hits Grocery Bills

The Bloomberg Agriculture Spot Index (BCOMAGSP) posted its largest quarterly gain since Russia invaded Ukraine in early 2022, as Black Sea disruptions, a crisis in the Strait of Hormuz, and mounting El Niño risks have formed what could be considered a perfect storm poised to drive food prices higher.

BCOMAGSP, which tracks 10 major crops including corn, soybeans, wheat, coffee, sugar, cotton, cocoa, and others, jumped 13% in the third quarter.

Among individual movers, corn and wheat each climbed 15%, while soybeans gained 13%.

Beyond the Russia-Ukraine fighting and disruptions to grain shipments from the Black Sea region, the next big threat to the crop space is a strengthening El Niño, on track to rank among the strongest on record. This puts various types of crops in major growing belts around the world at risk and has sent harvest yields plunging. 

Already, India's weakest monsoon season in a decade has added to concerns about harvests and food prices.

El Niño global impacts:

In August, BCOMAGSP recorded its largest monthly surge since the Arab Spring riots era, as the number of Wall Street desks warning about a food crisis next year continues to rise.

Our coverage:

For central banks already grappling with a deepening global bond rout, surging diesel and crop prices threaten to make inflationary pressures rather sticky. The refined-products crisis is raising the cost of producing and transporting food, while higher crop prices risk feeding through to grocery bills next year.

Tyler Durden Thu, 10/01/2026 - 10:40

US Warns Europe: Release Emergency Diesel Supplies Or Face Export Ban

Zero Hedge -

US Warns Europe: Release Emergency Diesel Supplies Or Face Export Ban

The refined products crisis remains unresolved as the Northern Hemisphere winter approaches. 

Speaking in the Oval Office on Wednesday, President Trump said he holds discussions "every day" about a potential diesel export ban, blaming Russia's war in Ukraine for fueling the supply squeeze. His administration is now pressuring European governments to release emergency diesel inventories to contain further price surges and reduce the risk of an economic shock in the coming months. 

Reuters reports that the Trump administration has asked Germany and France to release emergency diesel inventories to help create a buffer against the supply squeeze in the industrial fuel or face a potential US diesel export ban.

The total request calls for the release of 120 million barrels of diesel over the next six months, according to a source in a European capital cited by the outlet. That would be equivalent to about 660,000 barrels a day of additional supply.

"It is in Europe's best interest to work with the United States as we pursue multiple pathways to boost the supply of refined products and lower costs for consumers," one source, a US official, told Reuters.

Trump warned yesterday in the Oval Office that an export ban would "have a negative impact on gasoline" prices but could lower diesel costs. He warned that Russia's war with Ukraine is the main driver of soaring prices. Russia recently extended an export ban on the industrial fuel.

Goldman analysts Yulia Zhestkova Grigsby, Alexandra Paulus and Daan Struyven noted earlier this week that estimated "dark exports" have helped boost Persian Gulf oil exports to 23.3 million barrels a day over the past week, back to prewar levels. Still, refined product exports remain at just half of their 2025 averages.

Goldman energy analyst Nikhil Bhandari warned last month that the refining crisis would persist through 2027 and prolong the pain at the pump.

Elevated diesel prices across the West risk triggering an economic shock, according to Bloomberg Intelligence senior commodity strategist Mike McGlone. He said that shock could be similar to what happened during the 2008 energy crisis.

Perhaps the first domino has already fallen: trucking companies with the weakest balance sheets fall first.

Bloomberg commodities expert Javier Blas wrote earlier on X, "Europe is finding itself sandwiched from all sides when it comes to refined products ... diesel in particular (some of the damage is due to the US-Iran war; some is due to Ukraine-Russia; some is due to China, and a lot is self-inflicted). Policy response: Head in the sand."

US Energy Secretary Chris Wright said Wednesday that the Trump administration expects announcements from Europe very soon about tapping emergency diesel supplies.

Tyler Durden Thu, 10/01/2026 - 09:54

The Data Center Boom Faces Mounting Obstacles

Zero Hedge -

The Data Center Boom Faces Mounting Obstacles

By Brian Martucci of UtilityDive,

The U.S. data center boom has entered a new, contradictory phase.
On the one hand, both data center construction activity and credible forecasts for near-term capacity additions to the electric grid to serve data centers remain robust. The Electric Power Research Institute, for example, said in February that data centers will represent up to 17% of U.S. electricity demand in 2030 and as much as 20% in 2035.
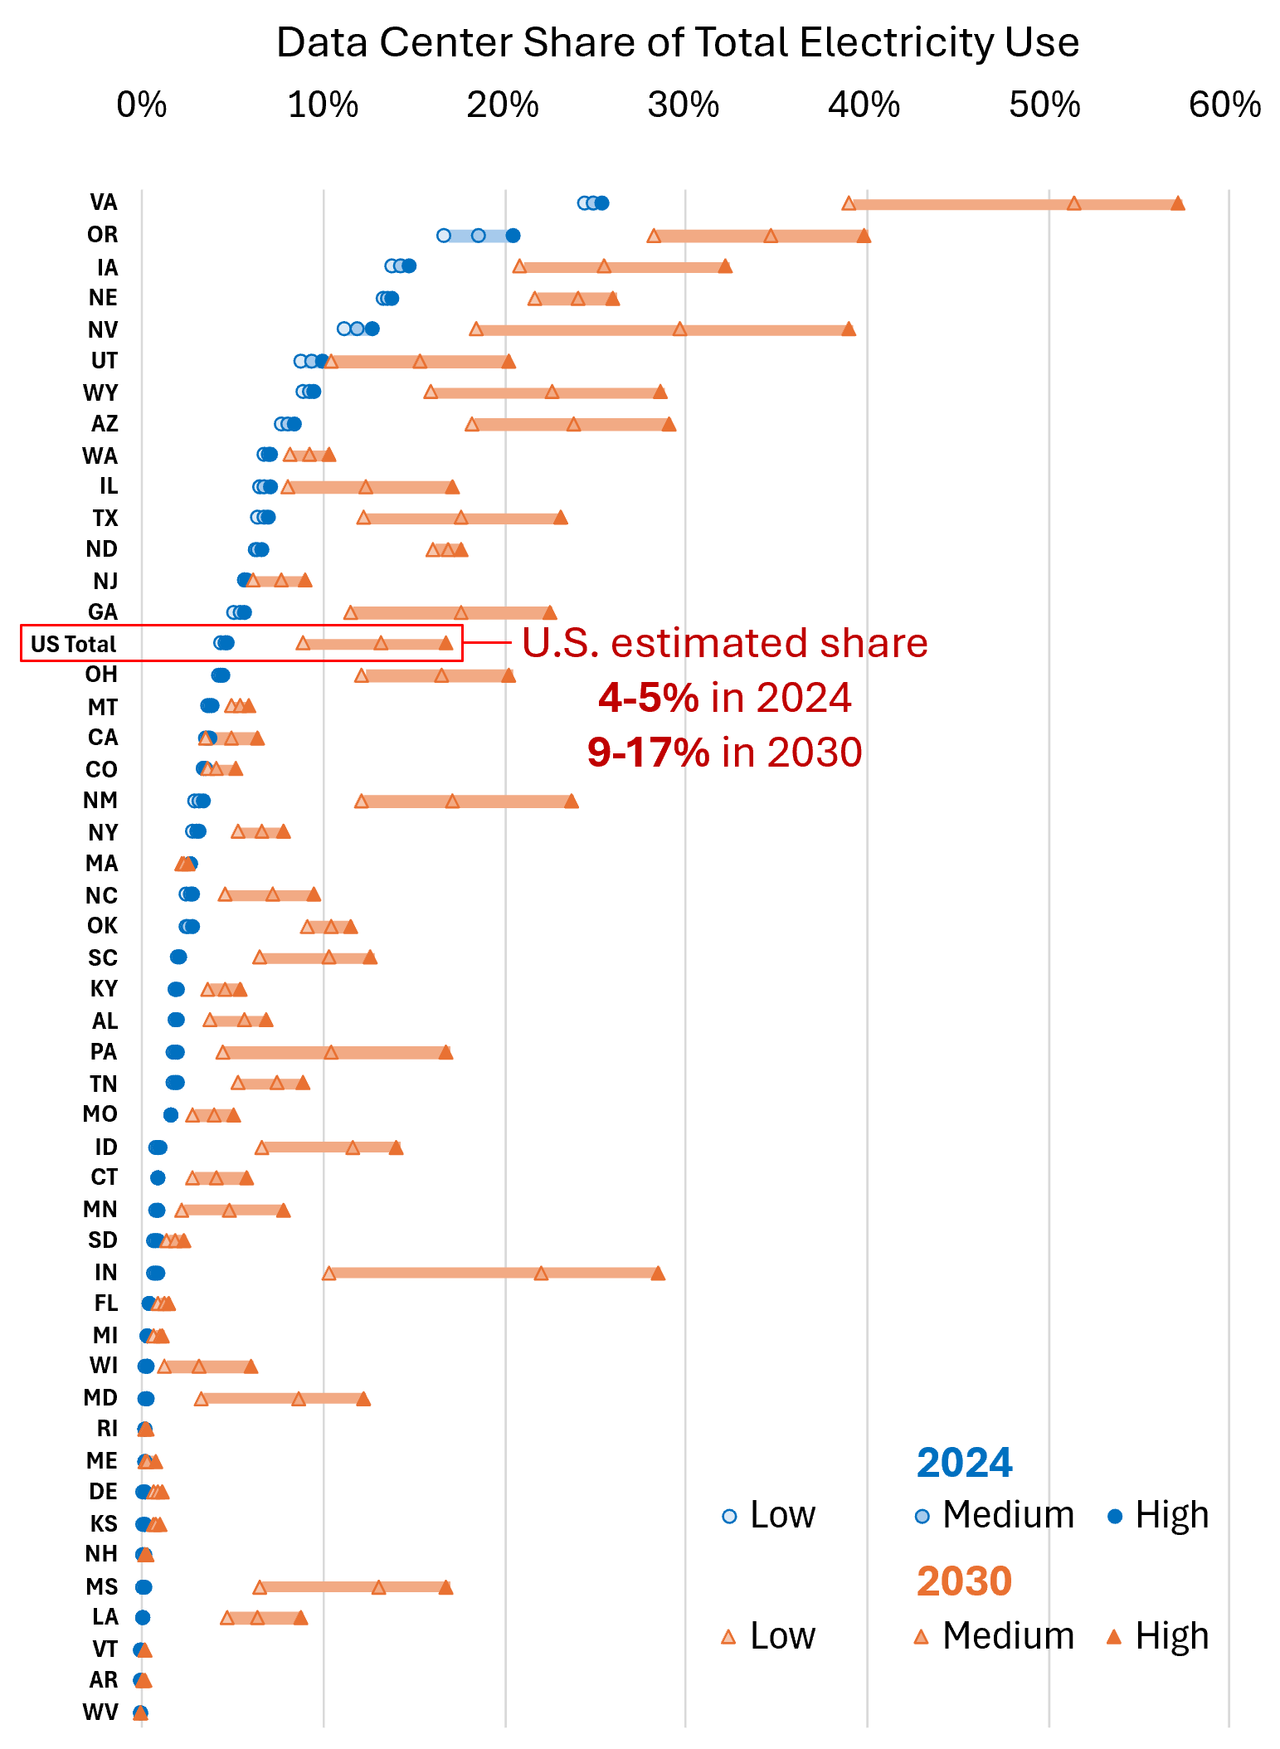
On the other hand, data center and utility infrastructure projects face a host of challenges. These include both physical constraints, such as equipment and labor shortages, as well as mounting public opposition driven by concerns about large-scale computing facilities’ impact on water supplies, the cost and reliability of power and natural gas supplies, and the quality of life in host communities. 

The upshot is that even some data center development projects advanced enough to appear in utility load forecasts with a named hyperscaler attached are not certain to move forward. 

Near Grand Rapids, Michigan, for example, a Microsoft data center touted by Consumers Energy faces an uncertain future amid local permitting delays. Another Microsoft-backed data center in Vineland, New Jersey, was recently hit with a $1 million fine for running dozens of gas-powered generators without the proper permits, and ordered to obtain them within 45 days or shut down.

A proposed Google data center that would interconnect in Xcel Energy’s Minnesota territory faces a court-ordered work stoppage to allow time for environmental review. 

​Even projects that sought to circumvent interconnection delays by building off-grid generation have seen setbacks. Last week, Oracle moved to protect itself financially from the delay or cancellation of Project Jupiter, a massive, 2.5-GW data center campus planned for Doña Ana County, New Mexico, after state regulators blocked a gas pipeline proposed to serve it.

Data center opposition “has reached a pitch I have never seen before in my 20-plus years in development,” Blake Nixon, president and CEO of Geronimo Power, told Utility Dive in an interview. 

This spring, officials in Nobles County, Minnesota, shot down a proposal by Geronimo to build a 400 MW “data park” there, despite the company’s efforts at community outreach. Now, Nixon said his team is considering alternative sites in nearby communities.

“[Data centers] are running into physical problems that are manifesting as market problems, political problems, regulatory problems and ultimately problems down on the ground,” he said.

In May, Goldman Sachs said only 50%-60% of planned data center capacity will come online as expected in the next two years amid delays and cancellations. 

And while the 36 GW of capacity added to the development pipeline in the first quarter of 2026 sounds impressive, that’s down 19% from the last quarter of 2025 as developers “continue to shift their focus to existing … pipelines in the face of an increasingly challenging development and regulatory environment,” Caitlin Connelly, a senior analyst with Wood Mackenzie, said in a July note.

Experts say these developments raise questions about just how much data center load will come online in the near term — injecting unwelcome uncertainty into utility planning cycles that must look years, even decades, into the future.

Working around grid constraints with flexibility, BYO capacity

It’s increasingly difficult for developers of large-scale data center campuses to find sites with the hundreds of megawatts, let alone gigawatts, of spare grid capacity they expect their projects to need at full build-out.

In the PJM Interconnection, real or perceived power scarcity is a major driver of both local opposition and top-down political backlash to the industry. The independent market monitor in July blamed data centers for 38% of charges at the most recent capacity auction.

The Democratic governors of Pennsylvania, Virginia and New Jersey have taken action in recent months to push regulators to require data centers to bring more generation and transmission capacity online.

These moves are not only in PJM states with Democratic governors. Power scarcity and cost concerns have triggered organized opposition and political backlash to data centers in places developers until recently believed were sympathetic to their cause, like Texas and Utah.

Texas Gov. Greg Abbott, R, successfully pushed for a sweeping pause on data center grid interconnections that threatens up to 20% of the total U.S. development pipeline, BloombergNEF said earlier this month.

Utilities and data centers are responding in several ways. 

The most straightforward is through “bring your own capacity” arrangements in which computing facilities colocate with new generation or finance local capacity additions (see "Bring Your Own Power Plant: Goldman Now Sees Behind-The-Meter Powering 25% Of All Data Centers By 2030").

Some of these arrangements are massive: OpenAI agreed earlier this month to take 8 GW of the capacity from a planned 10 GW power generation project in Ohio that includes 9.2-GW gas assets. The facility, which is being pursued by Japan’s SoftBank Group and the U.S. Department of Energy, would be the country’s largest generation source if built. 

If not, that title would go to Amazon’s proposed 7.7-GW gas-fired power plant in West Texas, which would also be larger than the current titleholder, Washington state’s 6.8-GW Grand Coulee hydroelectric dam.

Smaller-scale capacity procurements are also in the works, like Google’s “first-of-its-kind” deal with Voltus for 100 MW of virtual power plant capacity in PJM.

Elsewhere, utilities and data centers are pursuing asset-light alternatives using software to find previously untapped headroom on the grid or to ramp down computing loads during periods of peak demand. 

Last fall, for example, Portland General Electric said that by using GridCARE’s AI-powered load modeling tool, it had freed up 80 MW of interconnection headroom  — about a fifth of the 400 MW of data center load it expects to add by 2029. 

“We are seeing more interest from both data center developers and regional stakeholders (utilities, regulators, policymakers) to embrace flexible loads, which can accelerate the interconnection process,” Anuja Ratnayake, EPRI’s emerging technologies executive, said in an email. Ratnayake leads EPRI’s DCFlex initiative, which aims to standardize data center designs and utility programs around flexibility.  

And the United States still has load pockets with headroom to spare — no flexible interconnection or software wizardry required — though they’re increasingly rare. 

Data center developers and prospective tenants are looking past mature, power-constrained markets like Northern Virginia and toward renewables-rich regions with relatively low wholesale power prices, such as the northern Plains states. 

Some utilities and developers are also moving towards smaller data centers that could potentially soak up spare capacity without requiring much if any new generation, Louis Finkel, senior vice president of government relations for the National Rural Electric Cooperative Association, said in an email.

“Some co-ops are actively seeking these types of loads,” Finkel said. “A smaller-scale facility could be sited where there is excess capacity on the system, increasing grid utilization and potentially putting downward pressure on rates.”

Behind the meter or in front, projects face same equipment backlogs

In places without sufficient grid headroom, some data centers are looking to avoid multiyear interconnection queues and power up off-grid, at least temporarily. 

Cleanview, a grid data platform, counted more than 90 GW of behind-the-meter capacity across 59 large-scale data center projects earlier this year. As much as 13 GW of that total could come online by the end of 2027, Cleanview says.

But Andrew Maxson, an EPRI program manager, told Utility Dive these projects remain at the mercy of stretched supply chains for power and electrical equipment. These backlogs are continuing years after the COVID-19 pandemic first pushed them to the breaking point, and the delays affect both grid-connected and behind-the-meter projects, he said.

The typical customer now waits two to three years for standard power transformers — which must be custom-built — and generator step-up units, according to Fluxco, an electrical equipment marketplace. The situation is unlikely to improve before 2027, when significant new U.S. manufacturing capacity is expected to come online, Fluxco said.

The story is much the same for power generation equipment. GE Vernova, the top U.S.-based gas turbine manufacturer, is quoting delivery dates in the early 2030s for a backlog exceeding 100 GW. The backlogs at Mitsubishi Heavy Industries and Siemens Energy, the other two major gas turbine manufacturers, are slightly shorter but still measured in years rather than months.

Customers are responding with “[gigawatt]-scale procurement announcements for technologies such as fuel cells and engines, once considered unwieldy for large-scale deployment,” Maxson said in an email.

Share prices of Caterpillar, an industrial conglomerate with a fast-growing gas and diesel engine business, have doubled since last July. Bloom Energy, a fuel cell manufacturer, has seen its stock rise tenfold over the same period.

Unlike larger combined-cycle generating units, which require high-voltage transformers, smaller generating units can connect to the grid at medium voltages, Nina Sadighi, founder of Eradeh Power Consulting, said on a June 3 webinar organized by Wood Mackenzie.

The units themselves are less supply-constrained, with orders being booked today for 2028 delivery by customers looking to power up before receiving firm interconnection, she added.

Two-year waits are not ideal for data center users focused on speed to power above all else, but they’re preferable to longer waits for a grid connection, even after accounting for the higher cost of setting up what’s effectively an always-on microgrid, Sadighi said.

“You need to factor … the cost of a facility coming online a year late,” she said.

BloombergNEF’s most recent count of 74 GW of announced on-site gas power capacity at U.S. data centers would serve about 48 GW of facility load after accounting for equipment redundancy, said Mark Daly, the research provider’s head of technology and innovation.

“If the grid can only connect around 10 GW of new data center demand per year (near the current record in the US), then our data center demand forecast sees enough data center power demand for all this onsite gas to have something to serve,” Daly said in an email.

“Whether it is actually built on that timeline is a different question,” he added.

Labor constraints, public opposition complicate forecasts

Generating capacity, electrical supply chains and grid headroom aren’t the only meaningful constraints on data center development, however. Even after mitigating those issues, utilities face additional barriers to accurate near-term load and resource forecasting. 

Finding qualified people to build computing facilities and install the massive amounts of computing and electrical equipment needed to run them is a big challenge, for example. 

Associated Builders and Contractors, a construction industry trade group, said in 2024 — before the AI-fueled data center building boom began in earnest — that the U.S. was short about 500,000 construction workers.

Though data centers earn more media attention than other types of large construction projects, they’re competing for specialized workers like electricians and pipefitters with semiconductor factories, battery plants and even power generation projects — often “in the same regions and during the same construction windows,” EPRI’s Maxson said.

“Skilled labor shortages have … emerged as a binding constraint on data center development and the energy infrastructure that serves it, rivaling land availability, permitting and energy supply as a top concern,” he said.

Those issues are colliding with stiffening public pushback to create a challenging development environment, according to recent polling. 

Seventy-one percent of Americans would oppose a data center being built nearby, according to a Heatmap News poll fielded in May — up nearly 30 percentage points from September. By Heatmap’s count, local opposition killed at least 20 proposed data center projects in the first quarter of 2026, the most of any quarter on record.

Organized opposition to data centers and related infrastructure has reached places — and political leaders — that were previously welcoming to data center development. 

Utah Gov. Spencer Cox, R, in May called on data center developers to increase their efforts to safeguard air quality, water resources and other utility ratepayers in his state. The celebrity investor behind a controversial 9-GW project in northern Utah subsequently slimmed down his proposal as the host county enacted a six-month moratorium on data center builds.

In Texas, Abbott directed state regulators in June to ensure data centers “fully fund the costs of electric infrastructure needed to serve their operations, preventing those costs from being passed on to residential ratepayers.” Weeks later, the governor effectively halted new data center interconnections until an audit of the queue could be completed. 

As with labor and supply chain bottlenecks, both grid-connected and behind-the-meter data centers face state and local permitting challenges, EPRI’s Maxson said.

“Permitting is layered with federal, regional, and local constraints,” he said. These constraints “may be more difficult down that chain, meaning that regional constraints are on top of federal ones, and then local ones are on top of both of those.”

Tyler Durden Thu, 10/01/2026 - 09:00

Mystery Shrouds Destruction Of US Spy Satellite

Zero Hedge -

Mystery Shrouds Destruction Of US Spy Satellite

A mysterious breakup of a decades-old American spy satellite has sent debris hurtling through low-Earth orbit, with the U.S. Space Force now tracking the fragments for potential threats to other spacecraft, according to Space-Track.

The satellite, known as USA 32, came apart on September 13 at approximately 5:13 p.m. ET, according to U.S. Space Forces-Space. Officials have not publicly determined what caused the nearly 40-year-old spacecraft to suddenly fragment.

"All tracked debris are being incorporated into routine conjunction assessment screenings to support spaceflight safety," U.S. Space Forces-Space said in a notice. "No immediate threats have been identified; further analysis is ongoing."

USA 32 had been circling Earth since the final years of the Cold War.

The National Reconnaissance Office satellite blasted into space aboard a Titan II rocket on September 5, 1988. Public records identify the spacecraft as an electronic and signals intelligence satellite designed to collect information from orbit.

USA 32 has also been identified as FARRAH III, part of a secretive family of American intelligence satellites whose name was inspired by actress Farrah Fawcett.

The satellite was traveling in an orbit roughly 480 miles above Earth when it broke apart. Officials have yet to disclose how many fragments were produced.
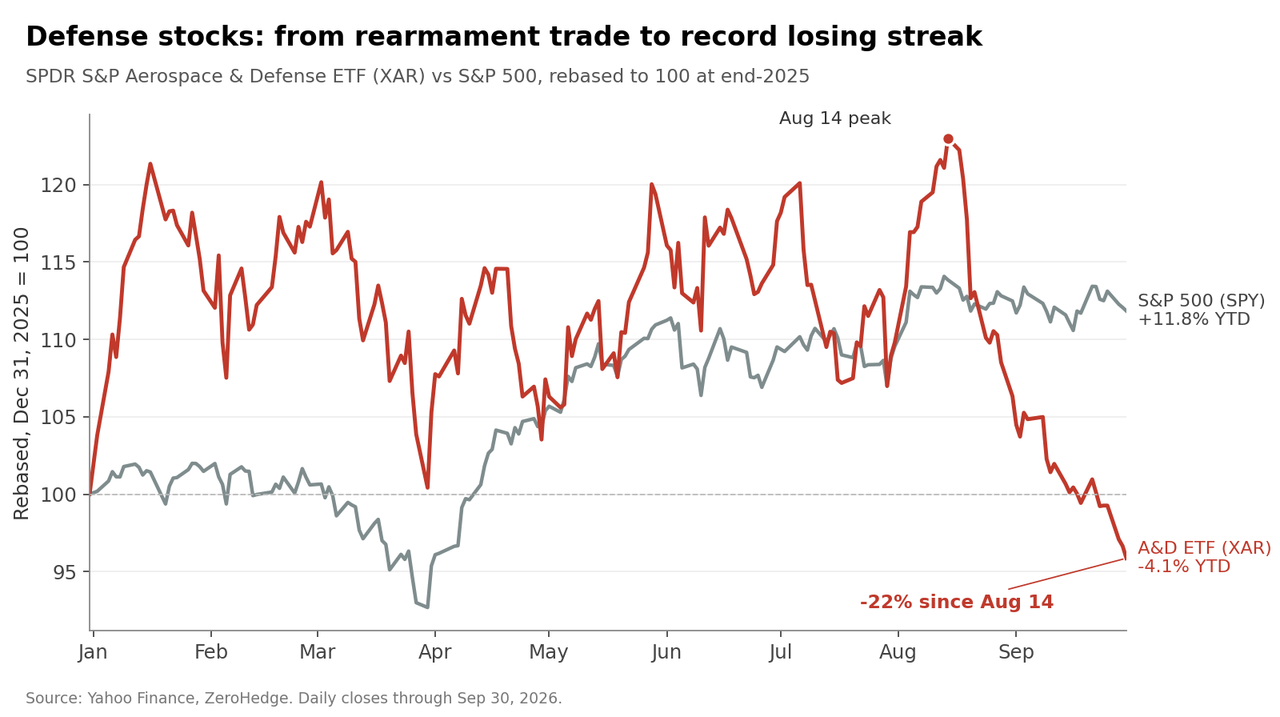
That uncertainty matters because debris traveling at orbital speeds can pose a hazard to functioning satellites even when the individual pieces are relatively small. Space Force tracking systems routinely monitor objects around Earth and screen their trajectories for possible collisions.

Exactly what happened to USA 32 remains a mystery.

A collision with an untracked object is one possible explanation for an unexpected satellite breakup. Aging spacecraft can also fragment because of failures involving batteries, pressurized tanks or other components. There is currently no public evidence establishing any of those scenarios as the cause of USA 32's demise.

Tyler Durden Thu, 10/01/2026 - 08:29

Amazon Secures 20 Years Of Nuclear Power From Constellation As Goldman Sees Industry-Wide Win

Zero Hedge -

Amazon Secures 20 Years Of Nuclear Power From Constellation As Goldman Sees Industry-Wide Win

Goldman analyst Carly Davenport views Amazon's nuclear power deal with Constellation Energy as "positive for industry broadly" as the "Powering Up America" theme and nuclear theme continue as Big Tech scrambles for the cleanest form of stable power to fuel data centers chip stacks. 

Davenport said Constellation Energy's 20-year deal to supply Amazon with 690 megawatts from Maryland's Calvert Cliffs nuclear plant is positive for both the utility and the broader power complex. 

Calvert Cliffs has two nuclear reactors, with a combined generating capacity of about 1,790 megawatts, enough to power 1.3 million homes. The deal unlocks power to Amazon's data centers across the 13-state grid overseen by PJM Interconnection. 

The deal also supports more than $3 billion in infrastructure investment at the nuclear power station, including upgrades adding 190 megawatts of generating capacity between 2030 and 2032. It also provides Constellation with revenue certainty. 

Davenport explained the deal:

Terms of the agreement: CEG and Amazon signed a 20-year PPA for nuclear power at the Calvert Cliffs Clean Energy Center, Maryland’s largest carbon-free energy facility and only nuclear plant.

Amount of capacity: The PPA is for 690 MW of total capacity, which includes a 190 MW of uprates scheduled to come online between 2030 and 2032.

Capital commitment: The agreement enables $3 bn+ in infrastructure investment to fund state-of-the-art upgrades across the entire 1,790 MW facility.

PJM implications: All electricity from Calvert Cliffs will continue to flow into the PJM regional grid. The parties have entered a separate but related retail supply agreement to support Amazon’s operations across the 13-state PJM market.

Beyond the agreement: The company highlighted the contract provides the long-term revenue certainty necessary for Constellation to pursue a 20-year license extension for the facility and explore further development of new clean energy power plans on-site.

Financial implications: While the release provides no color around pricing, we would point to the company’s disclosures which include a sensitivity on FCFbG upside from data center PPAs. CEG noted that 1 GW Nuclear PPA at a $20-$50/MWh premium to the PTC floor would translate to $125M-$325M FCFbG upside, implying FCFbG uplift of ~$86mn-$224mn if applied to the total 690 MW contract with Amazon.

Davenport added, "We view the PPA announcement as a solid update for the company and industry especially given it is for capacity in PJM, which has been a challenging environment recently due to regulatory uncertainty within the market, and investor confidence has been low in incremental data center PPAs being announced in the near term." 

"This agreement demonstrates how private investment can strengthen critical energy infrastructure," said Constellation CEO Joseph Dominguez.

Because of the AI data center buildout, nuclear power is getting new life, and grid upgrades will help buffer the fragile PJM region during peak demand. 

More importantly, the added capacity may help Maryland after years of 'climate-friendly' policies transformed the grid into a mess that collided with the era of data centers and electrification. One has to ask what the Democrat-run state was thinking over the years as it focused on everything but preparing the state for the next evolution of the modern economy. 

Constellation shares were up nearly 4% in pre-market trading. Davenport maintains a "Neutral" rating on the utility, with a 12-month price target of $305.

Tyler Durden Thu, 10/01/2026 - 08:15

Pages